
As grandparents, you have the unique opportunity to play a pivotal role in your grandchildren’s future by contributing to their education. One of the most effective ways to do this is by setting up a college savings account. With rising tuition costs and the growing importance of higher education, starting early can make a significant difference in alleviating the financial burden on your family. In this guide, we will explore the best college savings accounts available, tailored specifically for grandparents. We will delve into the features, benefits, and considerations of each option, empowering you to make informed decisions that will help secure a brighter future for your loved ones. Whether you’re looking for tax advantages, flexibility, or growth potential, this article will equip you with the knowledge to choose the right path for your family’s educational goals.
Understanding the Importance of College Savings Plans for Grandparents
For grandparents, setting up a college savings plan is more than just a financial gesture—it’s an investment in your family’s future. By taking proactive steps today, you ensure that your grandchildren have the resources they need to pursue higher education without the burden of student loans. Here are a few compelling reasons why these savings plans are vital:
- Tax Benefits: Many college savings plans offer tax advantages, allowing your contributions to grow tax-free or providing tax deductions for your contributions, depending on your location.
- Financial Security: By contributing to a college savings account, you help secure your grandchildren’s education, giving them the freedom to choose the best school without financial constraints.
- Family Legacy: Investing in education is an enduring legacy. It reflects a commitment to learning and growth, ensuring that your family values continue through the generations.
Understanding these benefits helps underscore the critical role grandparents can play in their grandchildren’s educational journey. It’s a gift that lasts a lifetime, fostering opportunities and paving the way for future success.
Key Features to Look for in a College Savings Account
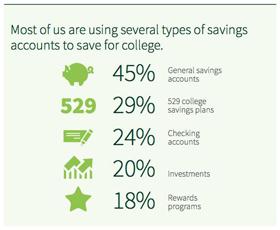
When selecting a college savings account, grandparents should focus on several key features that can maximize the benefits for their grandchildren’s education. Tax Advantages are crucial, as certain accounts, like 529 plans, offer tax-free growth and withdrawals for qualified education expenses. This can significantly boost savings over time. Flexibility is another important factor. Look for accounts that allow funds to be used for a variety of educational expenses, not just tuition, providing more comprehensive support for the student’s needs.
Additionally, consider the Contribution Limits and whether they align with your financial goals. Some accounts have higher limits, allowing more substantial contributions each year. Investment Options are also worth evaluating; diverse and robust options can help grow the savings more effectively. Ease of Management is essential, especially for grandparents who may prefer straightforward, user-friendly account management features. Ensuring that the account can be easily monitored and adjusted can make a significant difference in maintaining its effectiveness over time.
Top College Savings Accounts Tailored for Grandparents
Grandparents play a pivotal role in shaping the future of their grandchildren, and one of the most impactful ways they can contribute is by investing in their education. When considering college savings accounts, several options stand out for their flexibility and potential tax benefits. 529 Plans are a popular choice, offering tax-free growth and withdrawals for qualified educational expenses. They also provide the added advantage of allowing grandparents to maintain control over the funds, ensuring that their contributions are used as intended.
Another great option is a Coverdell Education Savings Account (ESA). Although contributions are limited to $2,000 per year per beneficiary, Coverdell ESAs offer a wide range of investment choices and can be used for both K-12 and higher education expenses. For grandparents looking to invest more broadly, Custodial Accounts under the Uniform Transfers to Minors Act (UTMA) or the Uniform Gifts to Minors Act (UGMA) can be a strategic choice, providing the flexibility to use funds for any purpose that benefits the grandchild, not just education. When planning, consider the unique advantages of each account type to make an informed decision that aligns with your financial goals and your grandchild’s educational needs.
Expert Tips on Maximizing College Savings Benefits
Grandparents looking to make the most of their college savings contributions can benefit greatly from strategic planning. 529 Plans are often the go-to option due to their tax advantages and flexibility. These plans allow your contributions to grow tax-free, and withdrawals for qualified education expenses are also tax-free. Some states even offer additional tax deductions or credits for contributions. However, it’s crucial to understand the specific rules of your state’s plan, as they can vary significantly.
- Understand state-specific benefits: Each state’s 529 plan may offer unique tax advantages or matching grants. Researching these can maximize your savings.
- Consider prepaid tuition plans: These plans allow you to lock in current tuition rates, potentially saving a significant amount as tuition costs rise.
- Evaluate gifting strategies: Contributions to 529 plans are considered gifts, so be aware of the annual gift tax exclusion limits. This can help you manage your contributions effectively.
Additionally, Coverdell Education Savings Accounts (ESAs) offer another savings avenue, albeit with a lower contribution limit. The advantage here is the flexibility to use the funds for K-12 expenses, not just college. Understanding the nuances of these options can help grandparents optimize their contributions and support their grandchildren’s education more effectively.