
Buying a home is one of the most significant financial decisions you will ever make, and having a clear, step-by-step plan can transform what often seems like a daunting process into an achievable goal. Whether you’re a first-time buyer or looking to upgrade, understanding the intricacies of the home-buying journey is crucial to making informed decisions. This guide will walk you through each stage of the process with confidence, from setting a budget to closing the deal. By the end, you’ll be equipped with the knowledge and strategies needed to navigate the real estate market successfully and secure the home of your dreams.
Understanding Your Financial Landscape and Setting a Realistic Budget
Embarking on the journey to homeownership begins with a clear understanding of your current financial situation. Start by taking a close look at your income, expenses, and any existing debts. Assessing your financial landscape helps you identify how much you can realistically allocate towards a home purchase. Begin by listing all sources of income and then outline your monthly expenses, categorizing them into essentials like housing, utilities, and groceries, as well as discretionary spending such as entertainment and dining out. Don’t forget to account for any outstanding debts, like student loans or credit card balances, which could impact your borrowing capacity.
Once you have a comprehensive overview of your finances, it’s time to set a realistic budget for your home purchase. Here are some key considerations:
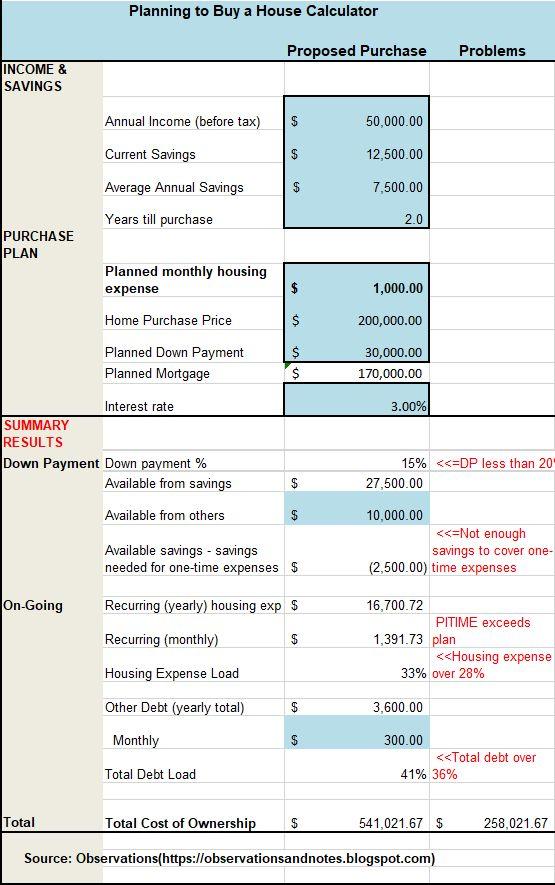
- Down Payment: Determine how much you can save for a down payment. Typically, this ranges from 5% to 20% of the home’s purchase price.
- Monthly Mortgage Payment: Calculate a monthly mortgage payment that fits comfortably within your budget, taking into account interest rates and loan terms.
- Additional Costs: Plan for additional expenses such as property taxes, home insurance, and maintenance costs.
- Emergency Fund: Ensure you have a buffer for unexpected expenses to avoid financial strain after purchasing your home.
By carefully analyzing your financial situation and setting a well-thought-out budget, you pave the way for a successful home buying experience.
Researching the Market and Identifying Your Ideal Location
Before embarking on your home-buying journey, it’s crucial to research the market thoroughly and pinpoint the location that aligns with your lifestyle and needs. Start by analyzing the real estate trends in areas you’re interested in. Look at factors such as the average home prices, historical appreciation rates, and market demand. This will give you a sense of whether a particular area is a sound investment. Additionally, consider the local amenities such as schools, parks, shopping centers, and public transport options, as these can significantly influence your daily life and the long-term value of your property.
- Explore neighborhood crime rates and safety statistics.
- Investigate potential future developments that might affect property values.
- Visit the areas at different times of the day to gauge the environment and community vibe.
- Engage with local forums or social media groups to gather insider information.
Once you have a comprehensive understanding of the market and have identified a few ideal locations, prioritize your criteria. Decide what’s non-negotiable for you in a neighborhood, whether it’s proximity to work, quality of schools, or access to leisure activities. This will help you narrow down your options and focus on areas that truly match your vision of the perfect home.
Navigating the Mortgage Process and Securing the Best Deal
Securing a favorable mortgage deal requires strategic planning and a keen understanding of the financial landscape. Begin by evaluating your credit score, as it significantly influences the interest rates you’re offered. If your score needs improvement, focus on paying down existing debts and ensuring timely payments. Next, gather essential documents like proof of income, tax returns, and bank statements to streamline the approval process.
Research different mortgage lenders to compare interest rates, fees, and terms. Consider reaching out to a mortgage broker who can offer insights into the best deals available. It’s also crucial to decide between a fixed-rate and an adjustable-rate mortgage based on your long-term financial goals. Remember to account for additional costs such as closing fees, property taxes, and insurance in your budget. By approaching the mortgage process methodically, you enhance your chances of securing a deal that aligns with your financial objectives.
- Evaluate and improve your credit score
- Gather necessary financial documents
- Research and compare mortgage lenders
- Consult with a mortgage broker
- Decide on the type of mortgage: fixed or adjustable-rate
- Include additional costs in your budget
Conducting Thorough Home Inspections and Making a Smart Offer
Once you’ve identified a potential home, it’s crucial to ensure it meets your standards and is free from major issues. Start by scheduling a professional home inspection. This will help you uncover hidden problems that could lead to costly repairs. During the inspection, pay attention to key areas such as:
- Foundation and Structure: Look for cracks or signs of settling that might indicate structural issues.
- Roof and Attic: Check for leaks, damaged shingles, and proper ventilation.
- Electrical and Plumbing Systems: Ensure wiring and pipes are up to code and in good condition.
- Heating and Cooling Systems: Confirm they are functioning efficiently and are well-maintained.
Once the inspection is complete, review the report thoroughly. If significant issues are found, consider negotiating repairs or a lower price with the seller. Crafting a smart offer involves balancing your budget with the home’s true value and any potential future expenses. Remember, a well-informed offer can give you leverage and protect your investment.