
In today’s rapidly evolving world, the value of a quality education cannot be overstated. Yet, with the rising costs of tuition and educational resources, preparing for this crucial investment requires foresight and strategic planning. Building a solid education savings plan from scratch might seem daunting, but with the right guidance, it can become a manageable and rewarding endeavor. This article will equip you with the essential tools and insights to construct a robust financial strategy, ensuring that the pursuit of knowledge is both accessible and sustainable. Whether you’re a parent planning for your child’s future or an individual seeking personal advancement, this guide will instill the confidence needed to navigate the complexities of educational funding and secure a brighter tomorrow.
Understanding the Basics of Education Savings
Embarking on the journey of saving for education requires a clear understanding of the fundamental principles that will guide your efforts. At its core, education savings is about setting aside funds to ensure that future educational expenses are met without financial strain. Here are some key components to consider:
- Start Early: The earlier you begin saving, the more time your money has to grow. This can significantly reduce the financial burden when the time comes to pay for educational costs.
- Set Clear Goals: Determine the estimated costs of education and establish specific, achievable savings targets. This clarity will keep you motivated and focused.
- Understand Your Options: Familiarize yourself with different savings vehicles, such as 529 plans, Coverdell ESAs, and custodial accounts. Each option offers unique benefits and tax advantages.
- Consistency is Key: Make regular contributions to your education savings plan. Even small, consistent deposits can accumulate over time and lead to substantial growth.
By grasping these basics, you lay a strong foundation for building an education savings plan that aligns with your financial goals and educational aspirations.
Choosing the Right Savings Accounts and Investment Options
When embarking on the journey of establishing a solid education savings plan, it’s crucial to identify the financial tools that best align with your goals. Savings accounts are often the first step for those seeking a low-risk, accessible option. Look for accounts with competitive interest rates, minimal fees, and user-friendly online banking features. Consider a high-yield savings account to maximize your returns while keeping your funds easily accessible. Alternatively, money market accounts might be a suitable choice if you prefer slightly higher interest rates with check-writing capabilities.
For those ready to explore investment options, diversifying your portfolio is key. Consider the following avenues:
- 529 Plans: Tax-advantaged savings plans designed specifically for education expenses. Many states offer tax deductions or credits for contributions.
- Coverdell Education Savings Accounts (ESA): These accounts allow for tax-free growth and withdrawals for qualified education expenses, though contribution limits are lower than 529 plans.
- Mutual Funds and ETFs: These provide a diversified investment portfolio and can be tailored to your risk tolerance and time horizon.
- Custodial Accounts: Consider UGMA/UTMA accounts for greater flexibility in investment choices, keeping in mind they transfer control to the beneficiary at a certain age.
Balancing savings with investments tailored to your risk tolerance and time horizon ensures a robust plan capable of adapting to future education needs. Choose wisely to lay a solid foundation for educational success.
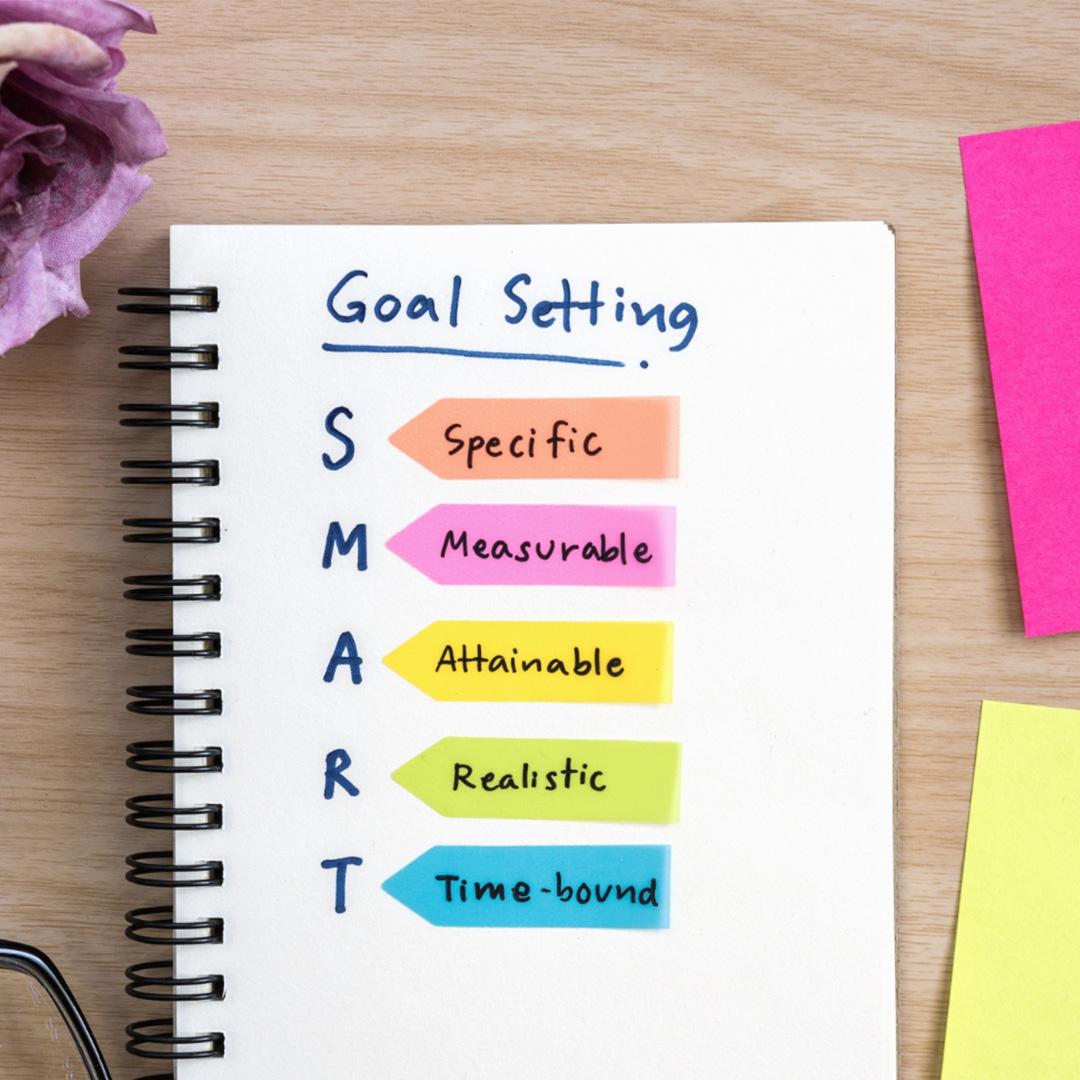
Setting Realistic Goals and Creating a Savings Timeline
Embarking on the journey of building an education savings plan requires setting achievable milestones and mapping out a strategic timeline. Start by determining your financial target, which should reflect the estimated cost of education, including tuition, books, and other related expenses. Break down your ultimate goal into smaller, manageable objectives to avoid feeling overwhelmed and to celebrate incremental achievements.
To craft a feasible savings timeline, consider these key factors:
- Current Financial Situation: Assess your income, expenses, and existing savings to understand how much you can realistically set aside each month.
- Time Horizon: Calculate the number of years until the education funds are needed, allowing you to adjust your monthly savings contributions accordingly.
- Inflation and Education Cost Trends: Stay informed about rising education costs and inflation rates to ensure your savings grow at a pace that matches or exceeds these increases.
By aligning your goals with a clear and actionable timeline, you create a robust foundation for your education savings plan, paving the way for financial security and educational success.
Maximizing Contributions and Taking Advantage of Tax Benefits
To ensure your education savings plan is both effective and efficient, it’s essential to fully leverage the tax advantages available to you. Maximizing contributions is a strategic move that not only accelerates your savings growth but also optimizes the benefits offered by various education savings accounts. Here’s how you can make the most of these opportunities:
- Utilize 529 Plans: These plans allow your contributions to grow tax-free, and withdrawals for qualified education expenses are also tax-exempt. Many states offer tax deductions or credits for contributions, so be sure to check your state’s specific benefits.
- Consider Coverdell ESAs: While contributions are limited to $2,000 per year, per beneficiary, Coverdell Education Savings Accounts offer the flexibility to pay for a broader range of educational expenses, from elementary to higher education, with tax-free growth.
- Max Out Annual Contributions: Take full advantage of the annual contribution limits for each type of account. Consistently maxing out contributions can significantly increase your investment growth potential over time.
- Gift Contributions: Leverage the annual gift tax exclusion by contributing up to the exclusion amount without incurring gift taxes, which can substantially boost the account balance over time.
By strategically navigating these tax benefits, you can enhance the financial support available for education, ensuring that your savings plan remains robust and sustainable in the long run.