
Navigating the financial landscape of major life events—whether it’s buying a home, starting a family, or planning for retirement—requires more than just a basic understanding of money management. It demands a strategic approach to setting financial priorities that can guide you through both expected and unexpected expenses. In this article, we will explore the essential steps to effectively prioritize your financial goals, ensuring that you are well-prepared to tackle these significant milestones with confidence. By understanding how to allocate your resources wisely and make informed decisions, you can lay a solid foundation for your financial future, turning life’s pivotal moments into opportunities for growth and stability.
Identifying Your Life Event Goals and Their Financial Implications
Understanding the financial implications of significant life events is crucial to setting effective priorities. Start by identifying key milestones that you anticipate, such as:
- Getting married: Consider costs for the wedding, honeymoon, and potential joint financial planning.
- Starting a family: Factor in expenses like healthcare, childcare, and education.
- Buying a home: Include down payments, mortgage costs, and maintenance expenses.
- Career transitions: Account for potential income changes, relocation costs, or further education.
- Retirement planning: Prepare for long-term savings, investment strategies, and potential healthcare needs.
Once you have a list, evaluate each event’s priority and potential impact on your financial resources. Prioritize based on timelines and importance to your overall life goals. Allocate resources accordingly, ensuring that you are not overextending yourself financially. By doing so, you not only prepare for these events but also ensure a balanced approach to your financial health.
Creating a Realistic Budget Aligned with Your Priorities
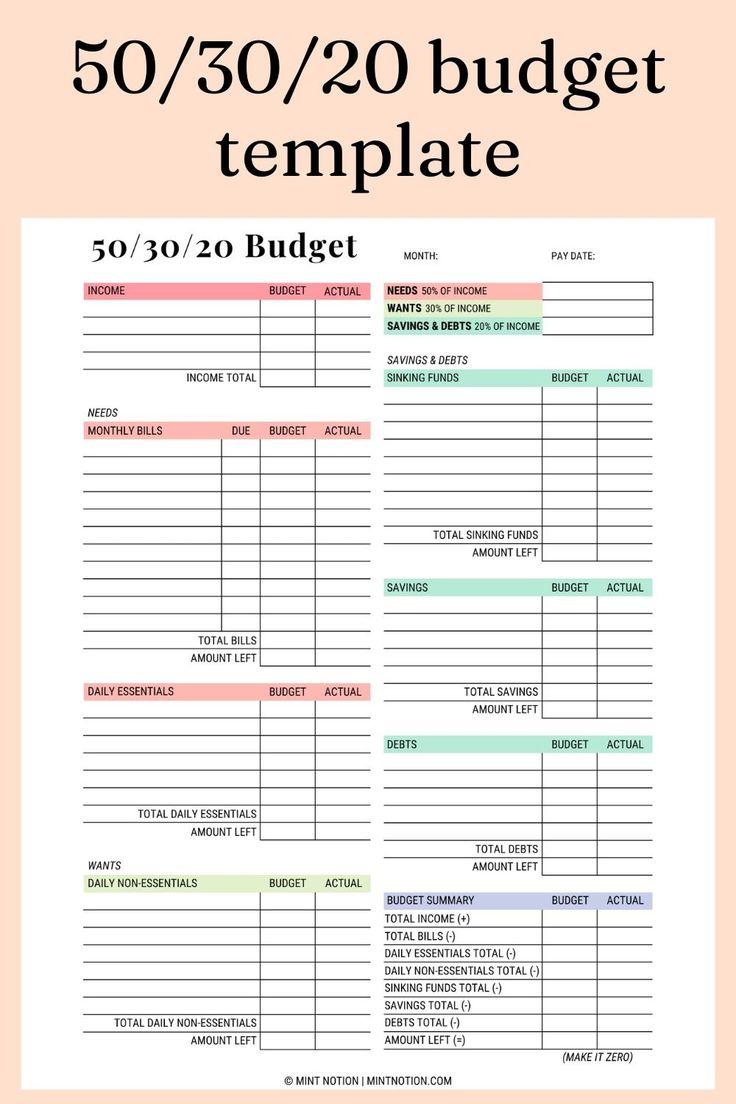
When planning for significant milestones, it’s crucial to align your budget with what truly matters to you. Start by identifying your core values and financial goals. Ask yourself, “What is most important to me in this stage of life?” This could range from buying a home, funding education, or saving for retirement. Once you have clarity, categorize your expenses to reflect these priorities. Here’s how you can structure your budget:
- Essentials: Allocate funds for necessities like housing, utilities, and groceries. Ensure these are covered before moving to other categories.
- Financial Goals: Prioritize savings and investments. Consider setting aside a fixed percentage of your income for retirement funds, emergency savings, or debt repayment.
- Lifestyle Choices: Budget for activities and purchases that enhance your quality of life, such as travel, hobbies, or dining out. Remember, these should not compromise your essentials or financial goals.
By aligning your spending with your values, you not only manage your finances more effectively but also ensure that your financial decisions support your long-term aspirations.
Strategically Building an Emergency Fund to Safeguard Against Uncertainties
Building a robust emergency fund is a cornerstone of financial resilience. Start by determining the ideal size of your fund. A good rule of thumb is to aim for three to six months’ worth of living expenses. This buffer provides a safety net against unexpected events like job loss or medical emergencies. Consider your unique circumstances: if you’re self-employed or have dependents, you might aim for the higher end of that range.
To strategically build your fund, incorporate it into your financial plan as a non-negotiable goal. Allocate a specific percentage of your income each month towards this fund. Automate your savings by setting up a separate savings account and scheduling automatic transfers. This approach not only simplifies the process but also reinforces the habit of saving. Additionally, periodically review your expenses and adjust your savings rate as needed. Embrace a mindset of financial prudence by identifying areas where you can cut back, such as subscriptions or dining out, and redirect those funds to your emergency savings.
- Prioritize high-interest debt repayment while maintaining contributions to your emergency fund.
- Reevaluate your fund’s adequacy annually to account for lifestyle changes or inflation.
- Avoid dipping into your fund for non-emergencies to ensure its availability when truly needed.
Exploring Investment Options to Enhance Financial Security
When preparing for significant milestones like buying a home, starting a family, or retiring, it is crucial to strategically allocate your resources to bolster your financial security. Investment diversification is a fundamental step in safeguarding your financial future. Consider spreading your investments across a variety of asset classes, such as:
- Stocks: Potential for high returns, but with increased risk.
- Bonds: Generally lower risk, providing steady income.
- Real Estate: Offers potential for rental income and long-term appreciation.
- Mutual Funds: A diversified mix of stocks and bonds, managed by professionals.
Align your investment choices with your personal risk tolerance and time horizon. For instance, if retirement is decades away, you might favor a higher proportion of stocks for growth potential. Conversely, if a major event like purchasing a home is imminent, a more conservative approach, with a focus on liquidity and capital preservation, might be advisable. Remember, regularly reviewing and adjusting your portfolio can help you stay on track towards your financial goals.