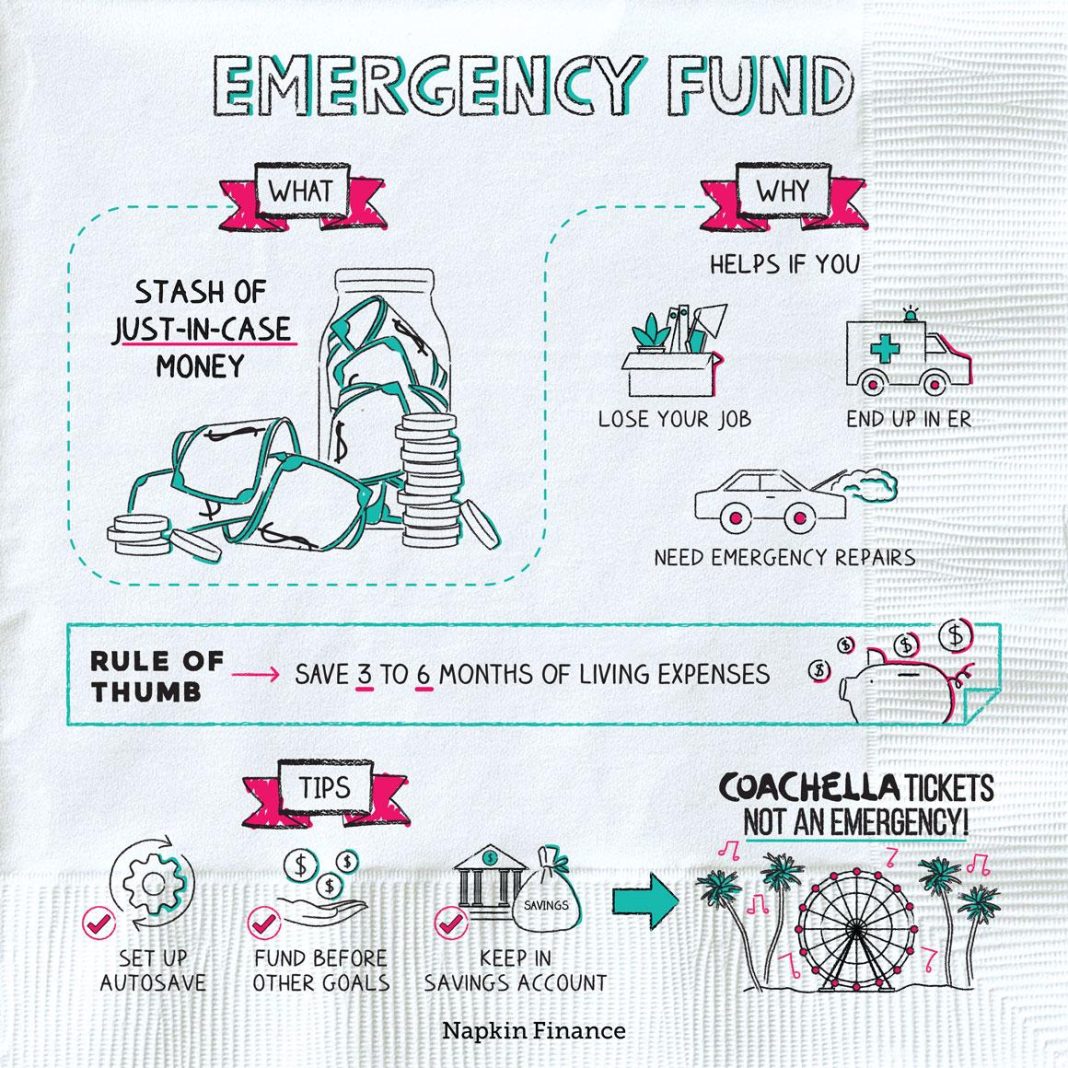

In today’s unpredictable world, financial security is more crucial than ever, especially when it comes to safeguarding your family’s well-being. While many families understand the importance of having an emergency fund, the challenge often lies in building it without sacrificing their current lifestyle or essential expenses. This article serves as a comprehensive guide to achieving that delicate balance. By implementing strategic financial practices and leveraging innovative saving techniques, you can effectively prepare for unforeseen circumstances without the need to compromise on your everyday comforts. With the right approach, building a robust family emergency fund becomes a manageable and rewarding endeavor, ensuring peace of mind and stability for your loved ones.
Establish a Dedicated Emergency Fund for Peace of Mind
Building a reserve specifically for unforeseen circumstances can provide a significant sense of security without disrupting your current lifestyle. To begin, consider automating a small portion of your income to be transferred directly into a separate savings account each month. Automating savings ensures consistency and minimizes the temptation to spend that money elsewhere. It can be as simple as setting up a direct deposit from your paycheck or scheduling a monthly transfer from your checking to your savings account.
Additionally, look for creative ways to boost this fund without feeling the pinch. Consider the following strategies:
- Round up purchases: Use apps that round up your purchases to the nearest dollar and deposit the difference into your emergency fund.
- Cashback rewards: Allocate cashback rewards from credit cards or online shopping portals directly into your savings.
- Review subscriptions: Periodically review and eliminate unused subscriptions, redirecting those funds into your emergency account.
By employing these methods, you can gradually build a robust safety net while maintaining your current spending habits.
Identify and Leverage Passive Income Opportunities
In the quest to safeguard your family’s financial future without tightening your current budget, exploring passive income streams can be a game-changer. Passive income, by definition, is the money you earn with minimal effort after the initial setup. It’s about making your money work for you, creating a safety net without compromising your lifestyle. Here are some ideas to get you started:
- Dividend Stocks: Investing in dividend-paying stocks can yield regular payouts, providing a steady income stream.
- Rental Properties: Owning real estate can generate ongoing rental income. Consider short-term rentals through platforms like Airbnb for increased flexibility.
- Peer-to-Peer Lending: Platforms like LendingClub allow you to earn interest by lending money to individuals or small businesses.
- Digital Products: Create and sell e-books, courses, or other digital products. Once created, these can generate income with little ongoing effort.
- Affiliate Marketing: Promote products you believe in and earn a commission on sales through your blog or social media channels.
By tapping into these opportunities, you can build a financial cushion that supports your family’s needs without sacrificing your current expenses. The key is to start small, learn as you go, and gradually expand your passive income portfolio.
Utilize Budgeting Tools to Optimize Savings
In today’s digital age, leveraging technology to manage finances can significantly enhance your ability to save for unexpected family emergencies. Budgeting tools offer a systematic approach to track expenses, identify spending patterns, and highlight potential savings opportunities. By integrating these tools into your financial routine, you can ensure a more disciplined approach to saving without sacrificing other essential expenditures.
- Automated Expense Tracking: Many budgeting apps automatically categorize your transactions, providing a clear picture of where your money is going. This feature allows you to quickly identify areas where you can cut back without impacting your lifestyle.
- Goal Setting and Alerts: Set specific savings goals within these tools and receive alerts to keep you on track. This not only motivates you to stick to your plan but also ensures that you are consistently contributing towards your emergency fund.
- Customizable Budgets: Tailor your budget to fit your family’s unique financial situation. Adjust categories and set spending limits that align with your priorities, ensuring that necessary expenses are covered while still allocating funds for savings.
By adopting these budgeting tools, you can maintain financial stability and prepare for unexpected events without having to compromise on your current lifestyle. Embrace these technologies to take control of your finances and secure your family’s future.
Explore Community Resources and Support Systems
When it comes to preparing for family emergencies, tapping into local community resources and support systems can be a game-changer. Many communities offer financial literacy workshops and emergency savings programs that can guide you in building a financial safety net without compromising your current lifestyle. These resources often provide free or low-cost access to professional advice, helping you navigate the complexities of budgeting and saving effectively. Additionally, community centers frequently host support groups where families share strategies and success stories, providing both motivation and practical tips.
Consider leveraging online community platforms that focus on financial education and support. Websites and forums often have sections dedicated to sharing resources like emergency fund calculators, budget templates, and saving challenges. These tools can help you set realistic goals and track your progress. Don’t overlook local credit unions and non-profit organizations, which sometimes offer special savings accounts with higher interest rates specifically for emergency funds. By engaging with these community-driven resources, you can enhance your financial resilience without the need to sacrifice your existing expenses.