
In an era marked by economic uncertainty and fluctuating markets, securing your family’s financial future may seem daunting. Yet, there is a straightforward and effective strategy that has consistently proven to yield long-term growth: investing in low-cost index funds. These financial instruments, which track the performance of a market index, offer a unique blend of diversification, low fees, and historical resilience, making them an attractive option for families aiming to build wealth over time. This article delves into the mechanics of index funds, elucidates their advantages over other investment vehicles, and provides a roadmap for integrating them into a robust financial strategy. With a confident grasp of these insights, you can embark on a journey to enhance your family’s financial stability and prosperity with assurance and clarity.
Understanding the Basics of Low Cost Index Funds
Low cost index funds are a powerful tool for building wealth, offering a simple yet effective investment strategy. By investing in a broad range of securities that mirror a specific index, these funds provide diversification, reducing the risk associated with individual stock picking. One of the primary advantages of index funds is their cost-efficiency, often boasting lower expense ratios compared to actively managed funds. This cost advantage translates into more of your money being invested, rather than spent on management fees, ultimately enhancing long-term returns.
Key features of low cost index funds include:
- Diversification: Spreads investment across a wide array of assets, minimizing risk.
- Cost-effectiveness: Low fees mean more of your money stays invested.
- Transparency: With clear, predictable holdings, investors know exactly what they own.
- Performance: Historically, index funds have outperformed many actively managed funds over the long term.
By integrating these funds into your family’s financial plan, you can leverage their benefits to foster growth and stability in your investment portfolio.
Strategic Allocation for Long-Term Growth
When considering investment strategies for long-term growth, it’s crucial to focus on strategic asset allocation that aligns with your family’s financial goals and risk tolerance. Low-cost index funds can be a pivotal part of this strategy, offering broad market exposure and minimizing fees. This approach helps in spreading risk across various sectors and geographies, ultimately aiming for steady growth over time.
To optimize your allocation, consider the following:
- Diversification: Allocate your investments across different asset classes such as equities, bonds, and real estate to reduce risk.
- Rebalancing: Periodically review and adjust your portfolio to maintain your desired level of risk.
- Cost Efficiency: Opt for funds with low expense ratios to maximize your returns over the long term.
By thoughtfully selecting a mix of index funds and maintaining discipline in your investment approach, you can create a robust foundation for your family’s wealth that is designed to endure market fluctuations and capitalize on growth opportunities.
Mitigating Risks with Diversified Portfolios
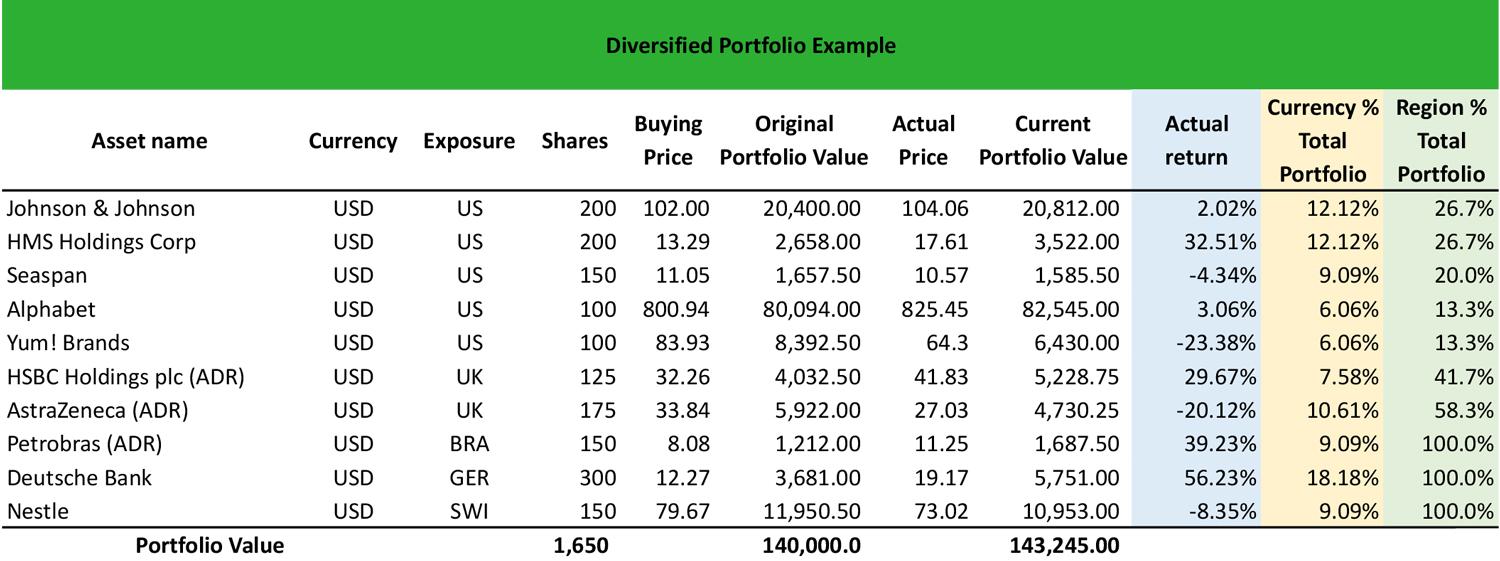
In the pursuit of growing your family’s wealth, embracing a diversified portfolio is a strategic approach to mitigate risks effectively. By spreading investments across a variety of asset classes, such as stocks, bonds, and real estate, you reduce the impact of any single asset’s poor performance on your overall financial health. Diversification allows you to capitalize on growth opportunities in different sectors while maintaining a balanced risk profile. Index funds are a powerful tool in this strategy, offering broad market exposure and reducing the need for constant portfolio management.
- Broad Exposure: Index funds inherently provide diversification by tracking entire market indices, reducing the volatility associated with individual stock picking.
- Cost-Effective: With lower management fees compared to actively managed funds, index funds help maximize returns by minimizing costs.
- Consistent Performance: Historically, index funds have shown reliable performance over time, aligning with long-term wealth-building goals.
Utilizing index funds within a diversified portfolio can safeguard your family’s financial future while pursuing growth, allowing you to sleep better at night knowing your investments are strategically managed.
Maximizing Returns through Consistent Contributions
One of the most effective strategies for growing your family’s wealth is through consistent contributions to low-cost index funds. This approach leverages the power of dollar-cost averaging, where you invest a fixed amount regularly, regardless of market conditions. This method not only mitigates the risks associated with market volatility but also ensures that you purchase more shares when prices are low and fewer when prices are high. Over time, this strategy can lead to significant growth in your investment portfolio.
- Set a schedule: Commit to investing a specific amount each month, treating it as a non-negotiable expense.
- Automate your investments: Use tools provided by most brokerage firms to automate transfers from your bank account to your investment account.
- Stay disciplined: Avoid the temptation to time the market; trust the process and stick to your plan.
By maintaining a disciplined approach and focusing on regular contributions, you position your family to benefit from the long-term growth potential of the market. This method is both simple and effective, allowing you to build wealth steadily and confidently over time.