
In today’s financial landscape, managing debt effectively is crucial for maintaining a healthy credit profile and achieving long-term financial goals. One of the most powerful tools at your disposal for tracking debt repayment progress is credit reporting. By leveraging detailed insights from your credit report, you can gain a clearer understanding of your current debt situation, monitor changes over time, and make informed decisions to accelerate your path to financial freedom. This guide will walk you through the essential steps to utilize credit reporting effectively, empowering you to take control of your debt repayment journey with confidence and precision. Whether you’re tackling credit card balances, student loans, or any other form of debt, understanding how to interpret and act on the information in your credit report is key to making steady, measurable progress.
Understanding Your Credit Report to Monitor Debt Repayment
When aiming to keep tabs on your debt repayment, it’s crucial to understand the intricate details of your credit report. This document provides a comprehensive overview of your financial history, including your current debt levels and payment patterns. Key elements to focus on include:
- Account Balances: Keep a close eye on the balances of your credit accounts. This helps you identify which debts are decreasing as you make payments.
- Payment History: This section reflects your consistency in making timely payments. Regularly check for any missed or late payments that might affect your credit score.
- Credit Utilization: Understand the ratio of your current credit card balances to your credit limits. Lowering this ratio by repaying debt can positively impact your credit score.
Regularly reviewing these components allows you to track your debt repayment journey effectively. By ensuring accuracy and addressing any discrepancies promptly, you can maintain a healthy credit profile and achieve your financial goals with confidence.
Key Metrics to Watch for Effective Debt Management
When managing your debt, it’s crucial to keep an eye on certain key metrics that can help you evaluate your repayment progress effectively. These metrics not only guide you in making informed decisions but also ensure you stay on track with your financial goals. Here are some essential metrics to monitor:
- Credit Utilization Ratio: This is the percentage of your total available credit that you’re currently using. A lower ratio indicates better debt management, ideally keeping it below 30% to improve your credit score.
- Debt-to-Income Ratio (DTI): Calculate your DTI by dividing your total monthly debt payments by your gross monthly income. A lower DTI suggests you have a good balance between debt and income, with a ratio under 36% being optimal.
- Payment History: Your track record of making timely payments significantly impacts your credit score. Ensure consistent on-time payments to build a positive credit history.
- Interest Rates: Keep an eye on the interest rates for each of your debts. Understanding which debts have higher rates can help you prioritize payments, potentially saving you money in the long run.
Regularly reviewing these metrics through your credit report can provide valuable insights into your debt repayment journey, helping you make strategic adjustments as needed.
Leveraging Credit Score Changes to Gauge Repayment Success
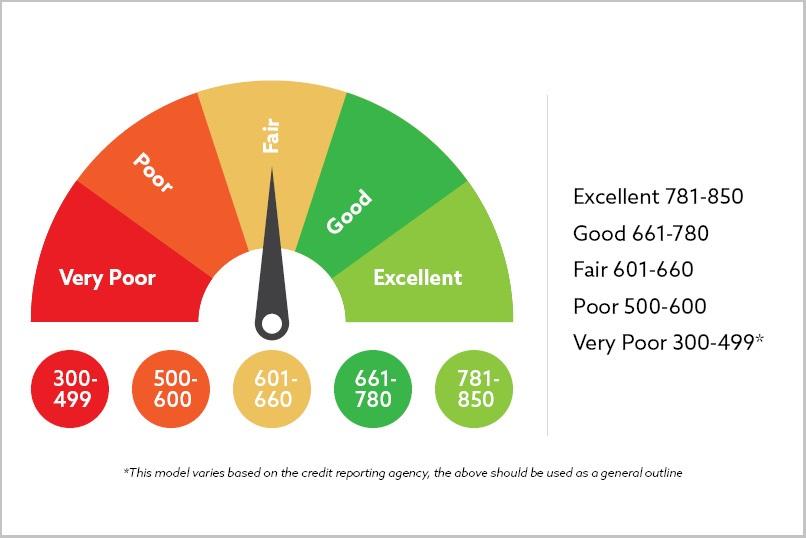
In the realm of debt management, understanding the nuances of your credit score can provide a powerful lens through which to assess repayment success. A change in your credit score can often signal how well you are managing your debt obligations. By actively monitoring these changes, you can gain insight into your financial health and adjust your strategies accordingly.
- Identify Positive Trends: An upward shift in your credit score may indicate successful debt repayment and responsible credit usage. This is a clear sign that your efforts to reduce outstanding balances or improve payment history are yielding results.
- Spot Potential Issues: Conversely, a declining credit score might be a red flag. It could suggest missed payments or an increased credit utilization ratio, prompting you to reassess your repayment plan or seek financial advice.
- Set Achievable Goals: Use credit score milestones as targets. Whether it’s reaching a particular score or maintaining a steady increase, these goals can serve as motivation and a measure of your progress over time.
Regularly reviewing your credit report allows you to not only celebrate your financial victories but also proactively address any setbacks. By embracing these insights, you can fine-tune your debt repayment approach, ultimately leading to a healthier financial future.
Strategies for Using Credit Reports to Stay on Track with Debt Goals
Utilizing credit reports effectively can be a game-changer in managing and achieving your debt repayment goals. To start, make it a habit to regularly check your credit report from all three major credit bureaus. This ensures you’re aware of any discrepancies or unauthorized activities that could derail your progress. Keeping a close eye on your credit score can also serve as a motivational tool, as you witness the positive impact of your repayment efforts.
Incorporate these strategies into your financial routine:
- Set clear milestones: Use your credit report to establish specific, achievable targets for reducing debt, such as paying off a certain percentage within a set timeframe.
- Identify high-interest debt: Pinpoint and prioritize debts with higher interest rates, as these can significantly impact your overall financial health if left unchecked.
- Monitor credit utilization: Aim to keep your credit utilization ratio below 30% to positively influence your credit score, which can lead to better loan terms in the future.
By leveraging these strategies, you can transform your credit report from a static document into a dynamic tool for tracking and achieving your debt goals with confidence.