In today’s dynamic economic landscape, multi-income households have become increasingly prevalent, presenting unique financial challenges and opportunities. As families navigate the complexities of managing multiple income streams, the importance of financial goal alignment has emerged as a critical factor for achieving long-term financial stability and success. Understanding how to harmonize diverse financial aspirations within a household is not merely an exercise in effective budgeting; it is a strategic approach to fostering unity, reducing financial stress, and maximizing the collective financial potential of all household members. This article delves into the pivotal role of financial goal alignment in multi-income households, offering practical insights and strategies to help families synchronize their financial objectives and create a cohesive path towards shared prosperity. By embracing a unified financial vision, households can not only enhance their financial well-being but also strengthen the bonds that underpin their collective economic journey.
Understanding the Importance of Financial Goal Alignment in Multi Income Households
In multi-income households, achieving financial harmony is not just a matter of combining paychecks but aligning each individual’s financial aspirations and objectives. Financial goal alignment serves as the backbone for a harmonious financial journey, where all household members work collectively towards shared ambitions. This alignment ensures that resources are allocated efficiently, minimizing conflicts and enhancing financial stability. It also fosters transparency and mutual understanding, allowing each member to contribute to a cohesive financial plan that respects individual priorities while prioritizing the household’s long-term vision.
To effectively align financial goals, households should focus on a few critical strategies:
- Open Communication: Regularly discuss financial objectives and progress to ensure everyone is on the same page.
- Shared Vision: Develop a unified financial plan that incorporates both joint and individual goals.
- Role Assignment: Clearly define financial roles and responsibilities to leverage each member’s strengths.
- Flexible Planning: Be prepared to adjust plans as circumstances change, maintaining alignment despite life’s uncertainties.
By embracing these strategies, multi-income households can create a balanced financial ecosystem where every member’s goals are respected and achieved collectively.
Strategies for Achieving Harmonious Financial Planning Among Multiple Earners
In households where multiple members contribute to the income pool, achieving financial harmony requires careful alignment of goals. Communication stands as the cornerstone of this process. Establishing regular financial meetings helps ensure everyone is on the same page and can express their aspirations and concerns openly. This not only builds trust but also paves the way for collaborative decision-making.
Prioritizing shared objectives is essential. Begin by identifying common goals such as saving for a vacation, investing in property, or funding education. Once these are established, develop a plan that aligns individual contributions with these shared ambitions. Consider the following strategies:
- Allocate roles: Determine who will manage budgeting, who will track expenses, and who will oversee investments.
- Create a unified budget: Develop a comprehensive budget that incorporates all incomes and expenditures.
- Set periodic reviews: Schedule regular check-ins to assess progress and adjust strategies as needed.
By employing these strategies, households can not only achieve their financial goals but also foster a sense of unity and shared purpose.
Practical Steps to Foster Financial Unity and Cooperation
Achieving financial unity in a household with multiple income streams requires a blend of communication, planning, and commitment. Start by organizing a regular family financial meeting where all contributors openly discuss their financial goals and concerns. This creates a platform for transparency and ensures everyone is on the same page. Emphasize the importance of shared objectives, such as saving for a vacation, paying off debts, or investing in education. This common ground fosters a sense of teamwork and accountability.
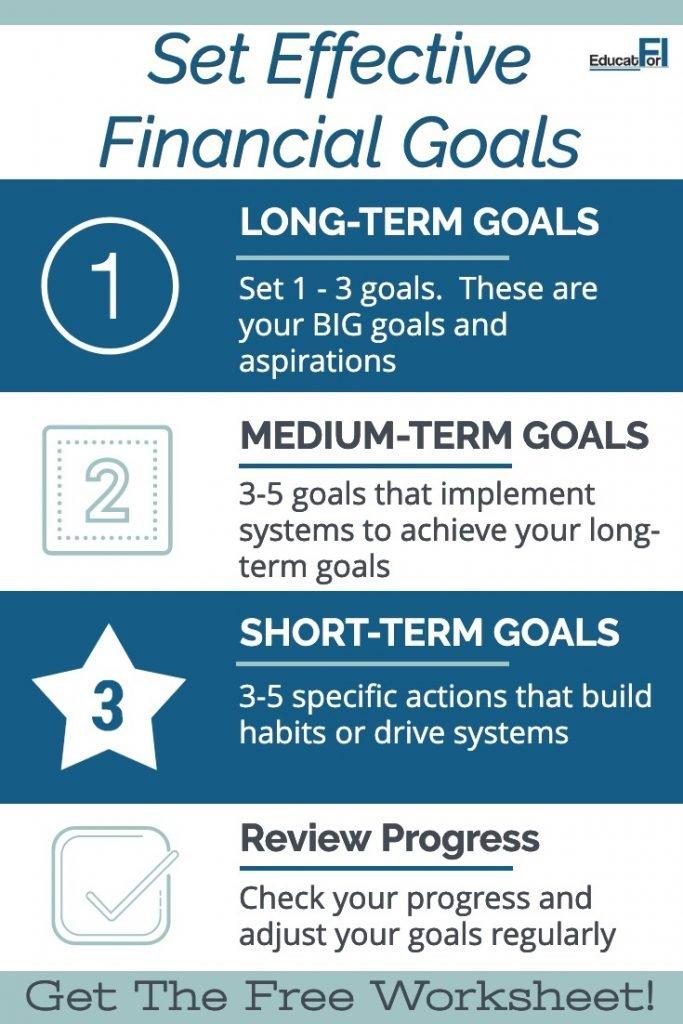
- Set joint financial goals: Identify short-term and long-term objectives that align with everyone’s priorities.
- Create a unified budget: Develop a household budget that reflects the agreed-upon goals and considers all income sources.
- Track progress together: Use budgeting apps or spreadsheets to monitor expenses and savings, encouraging collective responsibility.
- Celebrate achievements: Recognize milestones and successes to maintain motivation and strengthen financial cooperation.
Empowering Multi Income Families with Effective Goal Setting Techniques
In households where multiple streams of income converge, aligning financial goals can be a transformative strategy. Financial goal alignment involves a collaborative approach to setting and achieving financial objectives, ensuring that all members of the household are on the same page. This unified direction not only minimizes conflicts but also maximizes resource allocation. Consider the following techniques to enhance goal alignment:
- Regular Financial Meetings: Schedule monthly or quarterly meetings to discuss progress, setbacks, and any adjustments needed to the financial plan.
- Shared Budgeting Tools: Utilize digital tools or apps that allow for transparent tracking of income and expenses, fostering a sense of accountability.
- Prioritize Goals Collectively: List out individual and shared financial goals, then prioritize them together to ensure everyone’s aspirations are acknowledged.
- Celebrate Milestones: Recognize and celebrate when financial goals are met, reinforcing positive behavior and teamwork.
By implementing these strategies, multi-income families can create a harmonious financial environment that supports both individual dreams and collective ambitions.