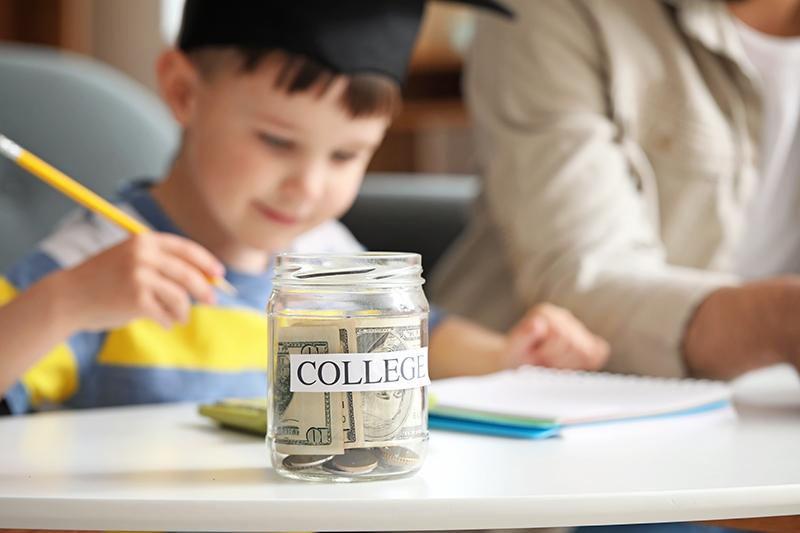

Navigating the financial landscape of higher education can be daunting, especially when you’re juggling your own student loan repayments while planning for your child’s college future. However, with a strategic approach and informed decision-making, you can effectively balance these dual responsibilities. This guide aims to empower you with practical steps and insights to ensure that your financial commitments today do not hinder your child’s educational aspirations tomorrow. By understanding the nuances of loan management and college planning, you can confidently chart a path that secures both your financial well-being and your child’s academic success.
Understanding Your Financial Landscape
Mapping out your financial future while balancing existing student loans might seem daunting, but it’s entirely achievable with the right strategies. Start by taking a comprehensive view of your current financial status. Consider creating a detailed budget that highlights your income, monthly expenses, and loan obligations. This will help you identify areas where you can cut back to allocate funds for future college savings. Prioritizing high-interest debt can accelerate your debt payoff, freeing up more resources for your child’s education.
Consider the following steps to enhance your financial planning:
- Explore savings options: Look into 529 plans or other education savings accounts that offer tax benefits.
- Automate savings: Set up automatic transfers to your savings account to ensure consistency in your saving habits.
- Seek additional income: Explore side gigs or freelance opportunities to boost your income stream.
- Consult a financial advisor: Professional advice can provide personalized strategies tailored to your financial situation.
By assessing your financial landscape with a clear and structured approach, you can successfully manage existing loans while building a solid foundation for your child’s educational future.
Strategic Loan Repayment Plans
When juggling the dual responsibilities of paying off your own student loans while planning for your child’s college education, strategic repayment plans can serve as a crucial ally. Start by evaluating all existing loan types and understanding the interest rates associated with each. Consider focusing on loans with the highest interest rates first, as this will save you money in the long run. Debt snowball and debt avalanche methods are popular strategies: the former focuses on paying off smaller debts to build momentum, while the latter targets high-interest debts for faster financial relief. Both have their merits, so choose the one that aligns with your financial goals and psychological comfort.
Implementing a clear budget can also be beneficial. Create a list of all monthly expenses and compare it to your income to identify potential areas for savings. Allocate these savings towards your loan repayment fund. Additionally, if you have multiple loans, consider consolidating them to lower your monthly payment and potentially secure a better interest rate. For some, enrolling in an income-driven repayment plan might offer the flexibility needed to manage both your loan payments and contributions to a college fund. Remember, being proactive and informed about your options will pave the way for a more secure financial future.
Smart Savings Techniques for Future Education
One of the most effective strategies to juggle paying off your student loans while preparing for your child’s college education is to adopt a multi-pronged approach. Start by creating a detailed budget that identifies discretionary spending areas you can cut back on. Use the savings to establish a dedicated education fund. Consider setting up a 529 plan, which offers tax advantages and can be tailored to your financial situation. Additionally, automate your savings to ensure consistent contributions without the temptation to spend elsewhere. Prioritize paying off high-interest loans first, as this will free up more money in the long run for future educational expenses.
- Explore employer-sponsored tuition assistance programs, which may help reduce the cost of further education for you or your children.
- Leverage scholarships and grants as a resource for both paying off loans and future educational expenses.
- Consider side gigs or freelance work to create an additional stream of income dedicated to education savings.
Balancing Priorities and Building a Support Network
Juggling the responsibilities of planning for college while managing your existing student loans can feel like a daunting task. Building a strong support network can significantly ease this journey. Start by identifying key individuals who can provide guidance and encouragement. This might include:
- Financial Advisors: Professionals who can offer strategic advice on managing debt and planning future educational expenses.
- Mentors: Experienced individuals in your field of interest who can provide career advice and networking opportunities.
- Family and Friends: Those who understand your situation and can offer emotional support and practical help.
- College Counselors: Experts who can help navigate application processes and financial aid options.
By engaging with these resources, you create a foundation that helps balance your priorities. Remember, it’s crucial to communicate openly with your network about your goals and challenges. This ensures that you receive tailored advice and support, making the path to further education less overwhelming and more achievable.