
Navigating major life changes can be daunting, especially when working within the constraints of a family budget. Whether you’re preparing for the arrival of a new family member, planning a cross-country move, or considering a career shift, strategic financial planning is essential to ensure a smooth transition. In this guide, we will explore practical steps and expert advice to help you manage these significant transitions without compromising your family’s financial stability. By understanding how to allocate resources effectively and prioritize expenditures, you can confidently face life’s changes with a well-structured plan that safeguards your family’s future.
Evaluating Your Financial Landscape for Future Changes
Understanding your current financial situation is the first step toward planning for significant life changes within a family budget. Begin by assessing your income sources and categorizing them as stable or variable. This will help you identify which sources are reliable and which may fluctuate. Next, take stock of your monthly expenses, separating them into fixed costs like mortgage or rent and variable expenses such as groceries and entertainment. This will provide a clear picture of your financial commitments and where there may be flexibility.
After laying out your current financial status, it’s essential to consider potential changes that could impact your financial landscape. These might include:
- Career transitions: Consider the implications of job changes, promotions, or possible layoffs.
- Family growth: Plan for the financial responsibilities that come with having children, such as childcare and education expenses.
- Health concerns: Account for unexpected medical expenses and insurance changes.
- Relocation: Understand the costs associated with moving to a new home or city, including potential changes in living expenses.
By thoroughly evaluating your financial landscape, you can identify areas where adjustments are necessary and set realistic goals to accommodate future changes.
Crafting a Realistic and Flexible Family Budget
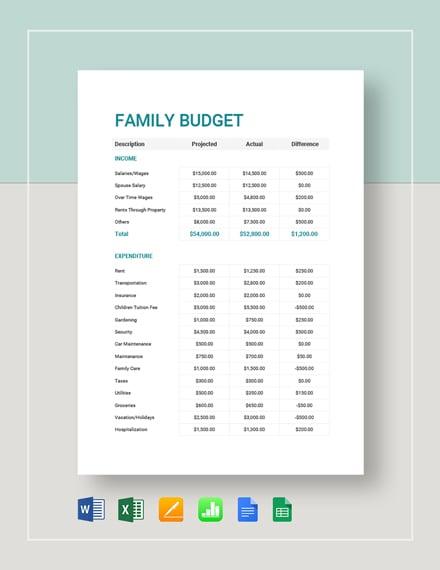
Creating a budget that adapts to life’s unexpected twists and turns is essential for any family. The key is to ensure it is both realistic and flexible. Start by identifying your core expenses, such as housing, groceries, and utilities, and distinguish these from discretionary spending like dining out or entertainment. Prioritize necessities and allocate funds for them first to ensure that your family’s fundamental needs are always met.
Once the essentials are covered, incorporate a contingency fund into your budget. This fund should be a safety net for unforeseen events like medical emergencies or sudden car repairs. A good rule of thumb is to set aside at least 10% of your monthly income into this fund. Additionally, consider these strategies for maintaining a dynamic budget:
- Regular Reviews: Schedule monthly check-ins to assess and adjust your budget as needed.
- Flexible Categories: Allow for movement between budget categories to accommodate shifting priorities.
- Emergency Savings: Build a separate emergency savings account to cushion major life changes.
Strategic Savings: Building an Emergency Fund for Unplanned Expenses
Building a financial safety net is essential for navigating unexpected twists and turns without derailing your family budget. An emergency fund acts as your first line of defense against unforeseen expenses, such as medical emergencies, car repairs, or sudden job loss. To create this cushion, start by assessing your monthly expenses and aim to save three to six months’ worth of living costs. Set up a dedicated savings account to keep these funds separate and easily accessible. Automate your savings by scheduling regular transfers from your checking account, ensuring consistent growth of your fund.
While building this fund, consider these key strategies:
- Cut non-essential expenses: Identify areas in your budget where you can reduce spending, such as dining out or subscription services.
- Increase your income: Explore side gigs or freelance opportunities to boost your savings rate.
- Prioritize high-interest debt: Focus on paying off debts with high interest rates to free up more funds for your emergency savings.
Adopting these approaches not only strengthens your financial resilience but also ensures your family is prepared for whatever life throws your way.
Cost-Effective Strategies for Managing Major Life Transitions
Managing major life transitions can be daunting, especially when trying to keep expenses under control. One effective strategy is to start by prioritizing your needs over wants. This involves distinguishing between essentials and luxuries, ensuring that your budget is focused on what truly matters during the transition period. Consider creating a detailed list of expenses, categorizing them into immediate necessities and those that can be postponed. This will help streamline your financial planning and keep you on track.
Another practical approach is to utilize community resources and support networks. Many communities offer services and programs designed to assist families during significant changes, such as moving, welcoming a new family member, or dealing with job transitions. Explore local organizations, non-profits, or even online forums that provide guidance, discounts, or free resources. Additionally, consider tapping into your personal network for advice, borrowing items, or sharing services. By leveraging these resources, you can alleviate some financial burdens without compromising the quality of the transition.
- Re-evaluate current subscriptions and memberships to identify areas for potential savings.
- Plan meals and shopping trips to minimize food waste and maximize budget efficiency.
- Engage in DIY projects for home improvements or celebrations to cut costs creatively.