In the intricate world of personal finance, understanding the impact of interest rates on debt repayment plans is crucial for anyone striving to achieve financial stability. Interest rates are more than just numbers; they are powerful tools that can significantly influence the trajectory of your financial obligations. Whether you’re managing credit card debt, student loans, or a mortgage, the rate of interest applied to your debt can either hasten your journey to financial freedom or extend it indefinitely. This article will demystify the role of interest rates, offering you a clear, strategic perspective on how they affect your repayment plans. With this knowledge, you will be empowered to make informed decisions, optimize your debt management strategies, and ultimately, take control of your financial future with confidence.
Analyzing the Relationship Between Interest Rates and Debt Repayment Strategies
Understanding how interest rates influence debt repayment strategies is crucial for anyone managing loans. At the heart of this relationship is the fact that interest rates determine how much extra you pay on top of the principal amount borrowed. When rates are high, the cost of borrowing increases, making it more challenging to pay down debt quickly. Conversely, low interest rates can present opportunities to expedite repayment. Here are some key strategies to consider:
- Refinancing: This involves replacing an existing loan with a new one at a lower interest rate, potentially reducing monthly payments and total interest paid over time.
- Debt Snowball Method: Focus on paying off smaller debts first, regardless of interest rate, to build momentum and confidence.
- Debt Avalanche Method: Prioritize paying off debts with the highest interest rates first to minimize interest expenses.
- Consolidation: Combining multiple debts into a single loan, ideally with a lower interest rate, can simplify payments and reduce costs.
Each strategy has its advantages and considerations, and the best choice often depends on individual financial situations and goals. However, by understanding and leveraging interest rates, borrowers can craft a more effective debt repayment plan that aligns with their financial objectives.
Identifying Key Factors That Influence Debt Repayment Success
When it comes to crafting effective debt repayment plans, understanding the key factors that drive success is crucial. Among these factors, several stand out for their significant impact on the ability to reduce debt effectively:
- Income Stability: A steady income stream ensures consistent payments, reducing the risk of default and helping maintain or improve credit scores.
- Budgeting Skills: Effective budgeting allows for better allocation of resources towards debt repayment, ensuring that debts are prioritized appropriately.
- Interest Rates: The cost of borrowing can significantly affect repayment timelines. Higher interest rates mean higher monthly payments, which can extend the time needed to pay off debt.
- Debt-to-Income Ratio: Keeping this ratio low is essential as it influences creditworthiness and the ability to manage additional debt obligations.
- Financial Literacy: Understanding financial principles and debt management strategies empowers individuals to make informed decisions and adopt effective repayment methods.
Recognizing and addressing these factors can streamline the path to financial freedom, making debt repayment a more manageable and successful endeavor.
Developing Effective Debt Repayment Plans in Varying Interest Rate Environments
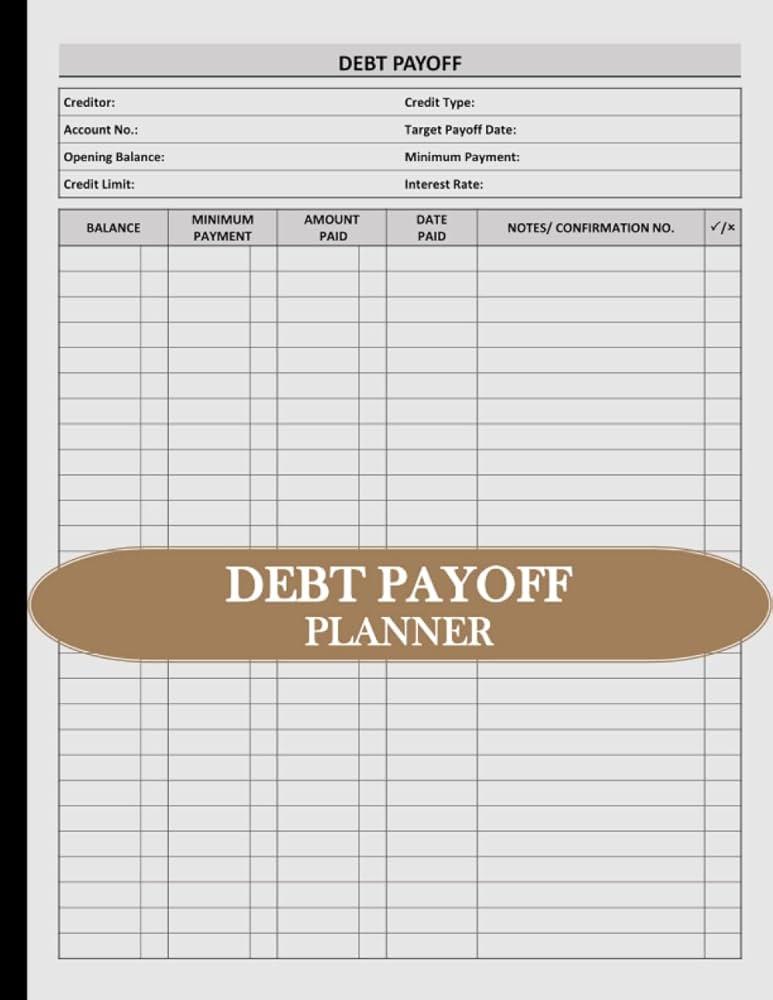
Creating a debt repayment plan requires careful consideration of the current interest rate environment. Interest rates can significantly affect the total amount you pay over time and the speed at which you can eliminate your debt. To develop an effective plan, it’s crucial to understand how different interest rate scenarios can impact your strategy. In a low-interest rate environment, focus on accelerating payments to reduce the principal faster. This strategy minimizes the overall interest paid and shortens the repayment period. On the other hand, during high-interest rate periods, it may be beneficial to prioritize paying off high-interest debts first, such as credit card balances, to prevent these costs from spiraling.
Here are some strategies to consider when crafting your repayment plan:
- Consolidation: Consider consolidating high-interest debts into a single loan with a lower interest rate.
- Refinancing: Explore refinancing options for existing loans to secure better interest rates and terms.
- Budget Adjustment: Reallocate your budget to increase debt payments, especially when interest rates are low.
- Emergency Fund: Maintain a robust emergency fund to avoid taking on additional debt during unexpected situations.
By tailoring your repayment strategy to the prevailing interest rate environment, you can optimize your debt management efforts and achieve financial freedom more efficiently.
Implementing Proactive Measures to Mitigate Interest Rate Risks in Debt Management
To effectively address the challenges posed by fluctuating interest rates, debt managers must adopt a proactive approach. One crucial strategy is to diversify the portfolio of debt instruments. By including a mix of fixed-rate and variable-rate debt, organizations can balance the benefits of stable payments with the potential cost savings from rate reductions. Additionally, it’s vital to conduct regular stress testing of debt portfolios. This involves simulating various interest rate scenarios to assess potential impacts on repayment obligations, ensuring preparedness for adverse conditions.
Implementing interest rate swaps and other derivative instruments can also serve as a robust mechanism for hedging against rate volatility. These financial products allow organizations to exchange variable interest payments for fixed rates, thus stabilizing cash flow. Furthermore, maintaining a comprehensive debt management policy that includes guidelines on interest rate exposure limits and refinancing strategies is essential. This policy should be regularly reviewed and updated to reflect current market conditions and organizational objectives, providing a structured framework for decision-making and risk mitigation.