
In today’s fast-paced world, managing personal finances can often feel like navigating a complex maze. Balancing debt repayment with the aspiration to save money might seem like a daunting task, but it is entirely achievable with the right strategies. This article will guide you through the essential steps to craft a budget that not only addresses your debt but also helps you build a robust savings plan. With a clear, methodical approach, you can regain control of your financial future, reduce stress, and pave the way for long-term stability. Dive in as we unravel the secrets to effective budgeting that empowers you to tackle debt head-on while ensuring your savings goals remain within reach.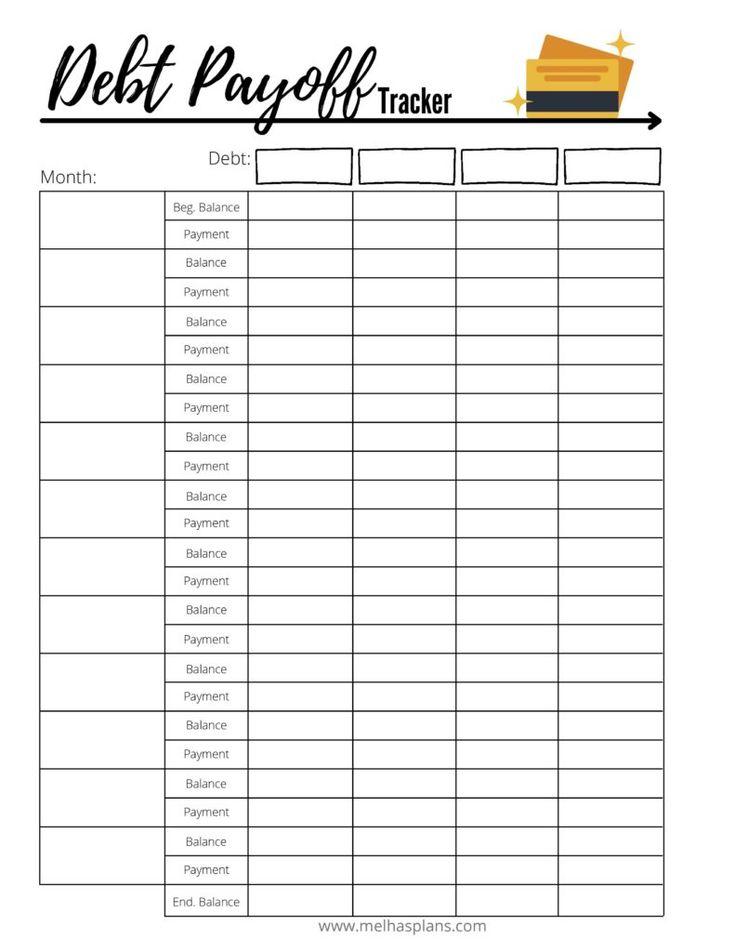
Understanding Your Financial Landscape
To effectively budget for debt repayment and simultaneously save money, it’s crucial to first evaluate your current financial situation. Begin by listing all sources of income and categorizing your expenses. This includes fixed expenses such as rent or mortgage payments, utilities, and insurance, as well as variable expenses like groceries, entertainment, and dining out. Understanding these categories will give you a clearer picture of your cash flow and help identify areas where you can cut back.
- Prioritize Your Debts: Focus on high-interest debts first, as these accumulate more costs over time. Consider using the avalanche method, where you pay off the highest interest debt while making minimum payments on others.
- Establish a Savings Goal: Allocate a portion of your income to savings, even if it’s a small amount initially. Setting up an automatic transfer to a savings account can help build a habit.
- Create a Realistic Budget: Utilize budgeting tools or apps to track your spending and adjust your budget as necessary. Ensure your budget allows for both debt repayment and saving.
By systematically addressing debt and building savings, you create a more balanced financial landscape, enabling you to handle unexpected expenses and work towards financial freedom.
Creating a Realistic Debt Repayment Plan
Crafting a practical strategy to tackle your debt begins with a clear understanding of your financial landscape. Start by gathering all your financial statements and making a list of your debts. This should include the creditor’s name, outstanding balance, interest rate, and minimum monthly payment. Prioritize your debts by identifying which ones have the highest interest rates, as these are the most costly over time. You might consider the avalanche method—focusing on paying off high-interest debts first—or the snowball method—eliminating smaller debts to build momentum. Choose the approach that best aligns with your financial situation and personal motivation.
Next, develop a budget that accommodates both your debt repayment goals and essential living expenses. Include the following in your plan:
- Income: List all sources of income to have a clear picture of available funds.
- Expenses: Categorize your expenses into essentials, like rent and groceries, and non-essentials, such as dining out and entertainment.
- Savings: Even while repaying debt, allocate a small portion of your income to savings to ensure financial resilience.
Consider using a budgeting app or a simple spreadsheet to track your spending and ensure you’re sticking to your plan. By taking these steps, you can create a sustainable debt repayment strategy that aligns with your financial goals.
Maximizing Savings Without Sacrificing Essentials
In the journey towards financial freedom, finding a balance between cutting costs and maintaining quality of life is crucial. Here are some strategies to help you streamline your spending without feeling deprived:
- Prioritize your needs: Begin by identifying the non-negotiable expenses like housing, utilities, and groceries. Use tools like budgeting apps to track and categorize your spending, ensuring your essentials are covered before anything else.
- Smart shopping: Embrace the power of bulk buying and discount stores. Look for sales, use coupons, and consider generic brands to trim your grocery bill without sacrificing quality.
- Utility management: Small changes, such as turning off lights when not in use, using energy-efficient appliances, and adjusting your thermostat, can lead to significant savings on your monthly bills.
- Meal planning: Avoid the lure of takeout by planning your meals ahead of time. Cooking at home not only saves money but also allows you to enjoy healthier, homemade meals.
By strategically focusing on these areas, you can effectively reduce your expenses, leaving more room in your budget for debt repayment and savings. Remember, the goal is to maximize your savings potential without compromising on the essentials that sustain your everyday life.
Leveraging Tools and Resources for Financial Success
To achieve financial success, it’s crucial to tap into the right tools and resources that can aid in managing debt repayment while simultaneously building savings. Start by utilizing budgeting apps that offer customizable categories and spending alerts. These apps can help you keep track of your expenses, making it easier to allocate funds for debt repayment. Additionally, take advantage of financial literacy platforms that provide educational resources on managing debt and increasing savings. Many of these platforms offer free courses and webinars that can deepen your understanding of personal finance.
Consider exploring community resources like workshops or seminars offered by local credit unions or non-profits. These often provide personalized advice and can connect you with financial advisors who specialize in debt management. Lastly, leverage online calculators to simulate various repayment scenarios. These tools can help you visualize how different payment strategies affect your debt timeline and interest costs, empowering you to make informed decisions. Remember, integrating these tools into your financial routine can streamline your path to debt freedom and savings growth.