

Creating a sustainable financial plan is an essential step towards achieving long-term financial stability and independence. With clear goal setting at its core, a well-crafted plan not only guides you through the complexities of managing your finances but also empowers you to make informed decisions that align with your values and aspirations. In this article, we will delve into the strategic process of developing a robust financial blueprint that stands the test of time. By exploring key principles, practical steps, and expert insights, you will gain the confidence and knowledge needed to set precise goals and create a financial plan that supports a secure and prosperous future. Whether you are just beginning your financial journey or seeking to refine your existing strategy, this guide will equip you with the tools to navigate your financial path with clarity and purpose.
Understanding the Core Principles of Sustainable Financial Planning
To craft a financial plan that stands the test of time, it is essential to embrace a set of core principles that anchor your approach in sustainability. Sustainable financial planning is not just about managing money; it’s about creating a resilient framework that supports long-term goals and adapts to life’s inevitable changes. At its heart, this planning method emphasizes the importance of setting clear, actionable goals. Without clarity, financial decisions can become aimless, leading to potential pitfalls and missed opportunities.
Begin by establishing a strong foundation with these guiding principles:
- Prioritize Long-term Stability: Focus on building a financial buffer that can weather economic fluctuations and personal emergencies.
- Practice Consistent Review: Regularly assess your financial goals and adjust them as necessary to stay aligned with your life circumstances and values.
- Integrate Ethical Considerations: Align your investments and spending with values that promote sustainability, ensuring your financial growth supports broader societal well-being.
- Embrace Flexibility: Allow for adaptability in your plan to accommodate unforeseen changes, ensuring resilience in the face of uncertainty.
By embedding these principles into your financial planning process, you not only create a roadmap for your financial future but also contribute to a more sustainable and equitable world.
Crafting Clear and Achievable Financial Goals
Setting financial objectives that are both clear and achievable is essential for any sustainable financial plan. Start by identifying your short-term, medium-term, and long-term goals. Short-term goals might include building an emergency fund or paying off a small debt, while medium-term goals could involve saving for a vacation or a new car. Long-term goals often focus on retirement savings or purchasing a home. Each goal should be specific, measurable, attainable, relevant, and time-bound (SMART).
- Be Specific: Instead of saying “save more,” determine an exact amount you want to save.
- Measurable: Track your progress with regular check-ins to stay on course.
- Attainable: Set realistic goals that challenge you but are within reach.
- Relevant: Align your goals with your broader life objectives and values.
- Time-bound: Establish a clear timeline to create a sense of urgency and motivation.
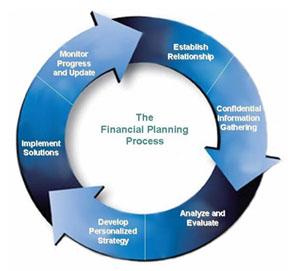
Once your goals are defined, prioritize them according to their importance and urgency. This helps in allocating your resources effectively and maintaining focus on what truly matters. Remember, flexibility is key; as your financial situation evolves, be prepared to adjust your goals accordingly. Consistent review and adaptation ensure your financial plan remains aligned with your changing life circumstances.
Integrating Long-term Vision with Short-term Milestones
Creating a sustainable financial plan requires a harmonious blend of visionary foresight and actionable steps. While it’s crucial to keep your eyes on the long-term financial horizon, breaking down these goals into manageable short-term milestones ensures you remain on track and motivated. Think of your financial journey as a marathon, not a sprint. Establish a clear vision for your financial future, such as saving for retirement, buying a home, or building an emergency fund. Then, identify specific milestones that will act as stepping stones toward these aspirations.
- Define Specific Milestones: Break down your ultimate financial goals into smaller, achievable tasks. For instance, if your goal is to save $50,000 for a home down payment, set monthly or quarterly savings targets.
- Prioritize Milestones: Not all milestones carry the same weight. Prioritize them based on urgency and impact, focusing on those that align most closely with your long-term vision.
- Track Progress Regularly: Regularly assess your progress towards each milestone. Utilize tools and apps to monitor your financial health, making adjustments as necessary.
- Celebrate Achievements: Recognize and celebrate when you reach a milestone. This not only boosts morale but also reinforces the behaviors that lead to financial success.
By integrating a long-term vision with short-term milestones, you create a roadmap that is both ambitious and attainable, ensuring a steady journey towards financial stability.
Implementing Effective Strategies for Financial Stability
Creating a sustainable financial plan starts with establishing clear, realistic goals. Begin by evaluating your current financial situation and identifying what you want to achieve in both the short and long term. This could include paying off debt, saving for retirement, or investing in a business venture. Once your goals are defined, break them down into actionable steps. Consider using the SMART criteria—Specific, Measurable, Achievable, Relevant, and Time-bound—to ensure each goal is clear and attainable. Remember, flexibility is key; be prepared to adjust your plan as life circumstances change.
Next, implement strategies that support your financial objectives. Here are a few essential tactics to consider:
- Budgeting: Create a monthly budget that aligns with your goals and stick to it. This will help you track your spending and identify areas where you can cut costs.
- Emergency Fund: Establish an emergency fund to cover unexpected expenses. Aim for at least three to six months’ worth of living expenses.
- Debt Management: Prioritize paying off high-interest debts to reduce financial strain and improve your credit score.
- Investment: Explore investment opportunities that match your risk tolerance and time horizon, ensuring a diversified portfolio for long-term growth.
By incorporating these strategies, you create a robust framework for achieving financial stability and ensuring a prosperous future.




