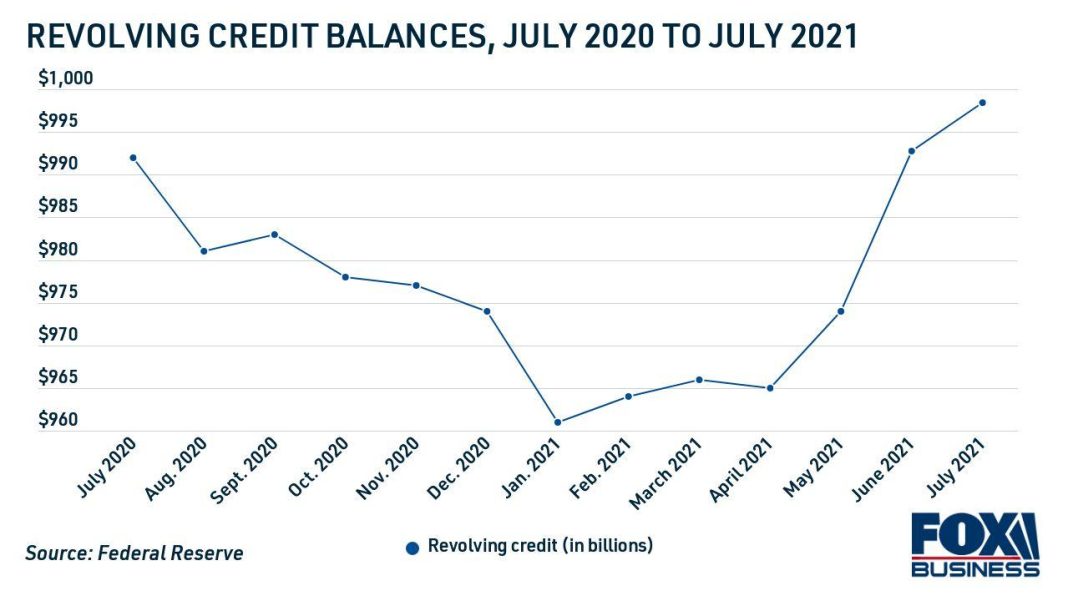

Managing revolving credit balances effectively is a crucial skill in maintaining financial health and ensuring long-term stability. As consumer debt continues to climb, finding efficient strategies to pay down these balances is more important than ever. In this article, we will explore the best ways to tackle revolving credit, from understanding your statements to implementing smart repayment strategies. Whether you’re looking to reduce interest payments or boost your credit score, these proven methods will empower you to take control of your finances with confidence and precision. Let’s dive into the steps you can take to achieve a debt-free future and secure your financial well-being.
Understanding Your Revolving Credit and Its Impact
Revolving credit, a financial tool that includes credit cards and lines of credit, offers flexibility in borrowing but also requires careful management. Unlike installment credit, which is paid back in fixed amounts, revolving credit allows you to borrow up to a certain limit and pay it back over time, making it essential to understand its nuances to maintain financial health. The interest rates on these accounts can be quite high, so it’s crucial to handle them wisely to avoid spiraling into debt.
- Monitor Your Spending: Keep a close eye on your expenses. Regularly reviewing your statements can help you stay within your limits and avoid unnecessary interest charges.
- Pay More Than the Minimum: Always aim to pay more than the minimum required amount. This approach not only reduces the principal faster but also decreases the total interest paid over time.
- Prioritize High-Interest Balances: Focus on paying down the balances with the highest interest rates first. This strategy can save you a significant amount of money in interest payments.
- Set Up Automatic Payments: To avoid late fees and potential credit score damage, consider setting up automatic payments. This ensures you never miss a payment deadline.
- Consider Balance Transfers: If you have a high-interest credit card debt, look for balance transfer options with lower rates. Many cards offer introductory rates that can provide temporary relief as you work on paying down your balances.
Effective Budgeting Strategies to Reduce Credit Balances
Mastering the art of budgeting can significantly help in reducing those pesky credit balances. By implementing a few strategic moves, you can start seeing a reduction in your debt. One effective approach is to adopt the 50/30/20 rule. This budgeting technique suggests allocating 50% of your income to needs, 30% to wants, and the remaining 20% towards savings and debt repayment. By prioritizing debt repayment within your budget, you ensure that reducing credit balances becomes a financial priority.
Another key strategy involves tracking and analyzing your spending patterns. Start by creating a detailed list of your monthly expenses and categorize them. This will help you identify areas where you can cut back and reallocate those funds towards paying off your credit balances. Consider the following:
- Eliminate unnecessary subscriptions: Cancel memberships or services you rarely use.
- Cook at home: Reduce dining out expenses by preparing meals at home.
- Negotiate bills: Contact service providers to see if there are ways to lower your bills.
By making these adjustments, you can redirect funds towards reducing your revolving credit balances, setting yourself on a path to financial freedom.
Smart Payment Techniques to Minimize Interest Charges
- Opt for Bi-Weekly Payments: Instead of making a single monthly payment, consider splitting your payment in half and paying every two weeks. This approach not only reduces the average daily balance, which interest is calculated on, but also results in an extra payment each year. Over time, this can significantly decrease the amount of interest paid and accelerate debt reduction.
- Prioritize High-Interest Balances: Focus on paying down the credit cards with the highest interest rates first. This strategy, known as the avalanche method, minimizes the amount of interest you accrue. By directing extra funds toward these high-rate accounts while maintaining minimum payments on others, you effectively cut down the overall interest burden.
- Utilize Balance Transfers Wisely: Consider transferring high-interest balances to a card with a lower rate or a promotional 0% APR offer. Be mindful of transfer fees and the duration of the promotional period. Ensure you have a clear plan to pay off the balance before the regular interest rate kicks in, to truly capitalize on this technique.
Leveraging Balance Transfers and Consolidation Options
When aiming to reduce revolving credit balances, utilizing balance transfers and consolidation options can be highly effective strategies. A balance transfer involves moving your existing credit card debt to a new card with a lower interest rate, often an introductory 0% APR for a set period. This can significantly lower the amount you pay in interest, allowing you to allocate more funds directly towards the principal. It’s important to consider any transfer fees and the duration of the promotional rate when evaluating this option.
Consolidation, on the other hand, merges multiple debts into a single loan with a fixed interest rate. This not only simplifies your payment schedule but can also result in lower monthly payments. Consider the following benefits:
- Streamlined Payments: Manage a single monthly payment instead of juggling multiple due dates.
- Potential Savings: Lower interest rates can reduce the total interest paid over time.
- Improved Credit Score: Successfully managing a consolidated loan can positively impact your credit score.
Both methods require discipline and careful planning, but when executed correctly, they can be powerful tools in your debt reduction arsenal.