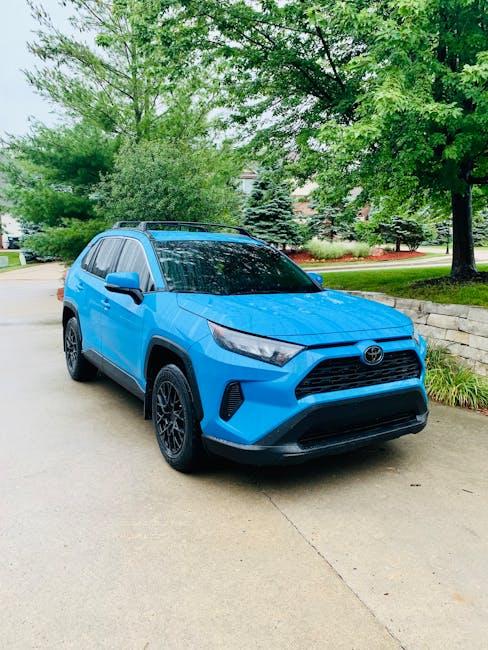

Purchasing a new family car is a significant milestone, often marked by excitement and anticipation. However, the financial commitment it entails can also bring about stress and uncertainty. Fortunately, with the right approach, saving for a new vehicle can be a manageable and even empowering process. This guide is designed to equip you with practical strategies and insights to help you build a car fund with confidence and ease. From setting realistic goals to leveraging smart budgeting techniques, we will walk you through each step, ensuring that you can drive away in your new family car without financial strain. Let’s embark on this journey together, transforming what could be a daunting task into a seamless and rewarding experience.
Create a Realistic Budget That Works for Your Family
Establishing a financial plan that aligns with your family’s needs is crucial for saving effectively. Begin by analyzing your monthly income and expenses to identify areas where you can cut back. It’s essential to prioritize your spending. Consider distinguishing between necessities and luxuries. This process might reveal unnecessary expenditures that can be redirected towards your car savings.
Incorporate the following strategies into your budgeting plan to make the journey to a new car stress-free:
- Set a clear savings goal: Determine the total amount needed for the car and break it down into manageable monthly targets.
- Create a dedicated savings account: Keep your car fund separate to track your progress and resist the temptation to dip into it for other expenses.
- Automate your savings: Set up automatic transfers to your car savings account to ensure consistent contributions without the need for constant reminders.
- Review and adjust: Regularly review your budget and adjust your spending habits to stay on track with your savings goals.
Explore Financing Options and Maximize Savings
Finding the right financing options can significantly reduce the financial burden of purchasing a new family car. Start by exploring different types of loans available. Auto loans are a common choice, but consider credit union loans or personal loans as well, which might offer more competitive rates. It’s crucial to compare the interest rates, terms, and conditions of each option. Use online calculators to estimate monthly payments and total interest over the life of the loan. Don’t hesitate to negotiate with lenders to secure the best possible deal.
- Zero-interest financing: Offered by some car dealerships, these can save you a considerable amount if you qualify.
- Leasing options: These might be beneficial if you prefer lower monthly payments and plan to upgrade your car every few years.
- Manufacturer incentives: Look for cash rebates, loyalty discounts, or special financing deals that can significantly cut costs.
Maximizing savings is not just about finding the right loan; it’s about reducing costs wherever possible. Consider setting up a dedicated savings account for your car fund, automating monthly deposits to grow your savings without the stress of remembering to transfer funds manually. Additionally, keep an eye out for seasonal sales events, and be prepared to negotiate the price of the car itself. Combining these strategies will put you in a strong position to finance your new vehicle effectively while keeping stress at bay.
Implement Smart Saving Strategies for a Stress-Free Experience
Transforming your savings plan into a seamless experience begins with adopting smart strategies that fit your lifestyle. First, set a realistic budget by analyzing your current expenses and identifying areas where you can cut back without sacrificing comfort. For instance, brewing your morning coffee at home instead of buying it daily can save a substantial amount over time. Additionally, consider implementing the 50/30/20 rule: allocate 50% of your income to necessities, 30% to discretionary spending, and 20% to savings. This balanced approach ensures you’re consistently setting aside funds for your new family car without feeling deprived.
Incorporate these tactics into your routine for a stress-free saving journey:
- Automate your savings: Set up automatic transfers to your savings account each month to ensure you’re consistently contributing without having to think about it.
- Leverage windfalls: Use unexpected money, like bonuses or tax refunds, to boost your car savings, accelerating your timeline.
- Track your progress: Regularly review your savings to stay motivated and make adjustments as needed. Seeing how close you are to your goal can be a powerful incentive to keep going.
By employing these smart saving strategies, you’ll find the journey to purchasing your new family car both manageable and rewarding.
Plan for Future Expenses to Maintain Financial Stability
Preparing for a new family car purchase requires a strategic approach to ensure that your financial stability remains intact. Start by evaluating your current financial situation and setting a realistic budget. Consider not only the upfront costs but also the long-term expenses such as insurance, maintenance, and fuel. It’s essential to prioritize savings and cut unnecessary expenses. Here are some effective strategies:
- Create a dedicated savings account: Designate a specific account for your car fund to prevent mixing with other expenses.
- Automate your savings: Set up automatic transfers to your car savings account each month to ensure consistent contributions.
- Review and adjust your budget: Regularly assess your budget to identify areas where you can save more aggressively.
- Explore financing options: Research and compare different financing plans to find the most favorable terms.
By methodically planning for these future expenses, you can alleviate the stress of buying a new family car and keep your financial health on track.