
In today’s rapidly evolving educational landscape, the importance of a robust financial strategy for your child’s college education cannot be overstated. As tuition costs continue to climb, establishing a comprehensive college savings plan has become an essential component of responsible financial planning for families. This guide will walk you through the critical steps of building a college savings plan tailored to your family’s needs, empowering you to make informed decisions and secure your child’s academic future. With authoritative insights and practical advice, we aim to demystify the complexities of college savings, ensuring you are well-equipped to navigate this significant financial commitment with confidence and foresight.
Understanding the Importance of Early Planning
Embarking on the journey of securing your child’s future requires a proactive approach, especially when it comes to financial planning for college. Early preparation allows you to take advantage of compounding interest, mitigate the impact of inflation, and explore a broader range of investment options. Starting sooner rather than later not only alleviates future financial strain but also empowers you to make informed decisions that align with your long-term financial goals.
- Leverage Compound Interest: The earlier you begin, the more time your savings have to grow, thanks to the power of compounding.
- Explore Diverse Investment Options: Starting early gives you the flexibility to consider a variety of investment vehicles, from 529 plans to custodial accounts, each with its unique benefits.
- Mitigate Inflation: Early planning helps in countering inflation’s impact, ensuring that your savings maintain their value over time.
- Reduce Financial Stress: By spreading out contributions over a longer period, you can reduce the monthly financial burden on your household budget.
Taking these steps not only sets a solid foundation for your child’s education but also instills a sense of financial security and responsibility in your family. Remember, the key is not just saving, but saving smartly and consistently over time.
Evaluating Savings Options and Accounts
When considering the best avenues for growing your college fund, it’s crucial to compare different savings accounts and options. 529 Plans are a popular choice due to their tax advantages and flexibility in covering educational expenses. However, it’s essential to evaluate the specific plan details, as fees and investment options can vary significantly by state. Coverdell Education Savings Accounts (ESAs) offer another alternative, allowing you to save up to $2,000 per year with the benefit of tax-free growth and withdrawals for qualified education expenses.
Beyond these specialized accounts, consider the potential benefits of traditional savings options. A High-Yield Savings Account can offer better interest rates than a standard savings account, though they often require a higher minimum balance. Additionally, Certificates of Deposit (CDs) can provide a fixed interest rate over a set period, which might be advantageous if you’re planning for future college expenses. It’s wise to weigh the pros and cons of each option, taking into account factors such as interest rates, fees, and accessibility, to ensure you choose the best fit for your financial goals and timeline.
Implementing a Consistent Contribution Strategy
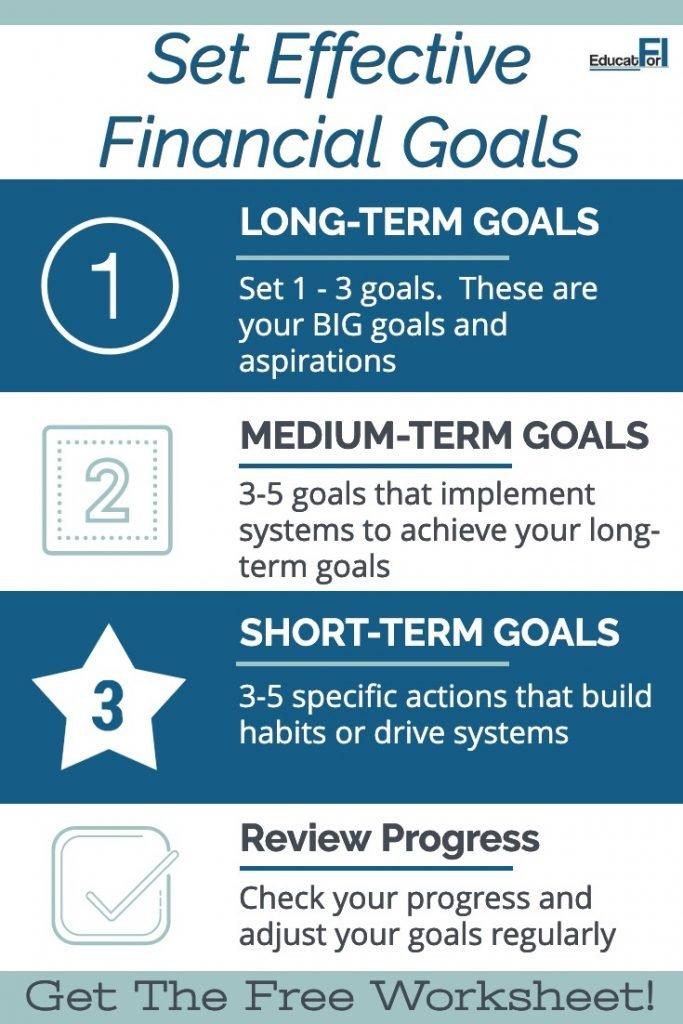
Establishing a regular and systematic approach to contributing to your child’s college savings plan is crucial for long-term success. Consistency is key, and it begins with setting a realistic budget that aligns with your financial situation. Allocate a specific amount each month dedicated solely to the college fund, treating it as a non-negotiable expense. This disciplined approach not only builds a substantial fund over time but also instills financial responsibility and foresight.
- Automate Contributions: Set up automatic transfers from your checking account to the savings plan to ensure regular deposits.
- Increase Contributions Gradually: As your income grows or financial obligations decrease, increase the contribution amount to accelerate growth.
- Review Annually: Conduct an annual review of your savings strategy to adjust contributions based on changes in financial goals or circumstances.
- Leverage Windfalls: Use bonuses, tax refunds, or unexpected financial gains to boost the college fund.
By following these strategies, you’ll establish a robust and reliable college savings plan that can withstand the test of time and ensure your child’s educational future.
Leveraging Tax Benefits and Incentives
To maximize your college savings strategy, it’s crucial to understand and utilize the available tax benefits and incentives. 529 plans are a popular choice, offering tax-free growth and tax-free withdrawals for qualified education expenses. Contributions to these plans might also be eligible for state tax deductions or credits, depending on where you live. Explore whether your state offers any unique benefits, such as matching contributions or additional tax breaks, to make the most of your savings.
- Coverdell Education Savings Accounts (ESAs): These accounts allow for tax-free growth and withdrawals for education expenses. While contribution limits are lower compared to 529 plans, they offer more flexibility in investment choices.
- American Opportunity Tax Credit (AOTC): This credit provides up to $2,500 per eligible student, covering tuition, fees, and course materials. Make sure to understand the income limits and eligibility criteria to claim this benefit effectively.
- Lifetime Learning Credit (LLC): Offering up to $2,000 per tax return, the LLC can be used for a wide range of educational expenses. It’s an excellent option for families with varying educational needs beyond undergraduate studies.
By strategically leveraging these incentives, you can significantly reduce the financial burden of college expenses and ensure a more robust savings plan for your child’s future education.