
The holiday season, a time of joy and celebration, can often bring with it the unwelcome guest of financial stress. As festive decorations adorn homes and gift lists grow, managing debt becomes an essential skill to ensure the season remains merry and bright. Navigating this financial landscape requires a strategic approach, balancing the spirit of giving with prudent financial management. In this article, we will explore the best ways to manage debt during the holidays, providing you with practical, effective strategies to maintain financial stability while still embracing the joy of the season. With a confident and informed approach, you can enjoy the holidays without the burden of financial worry.
Craft a Holiday Budget That Works for You
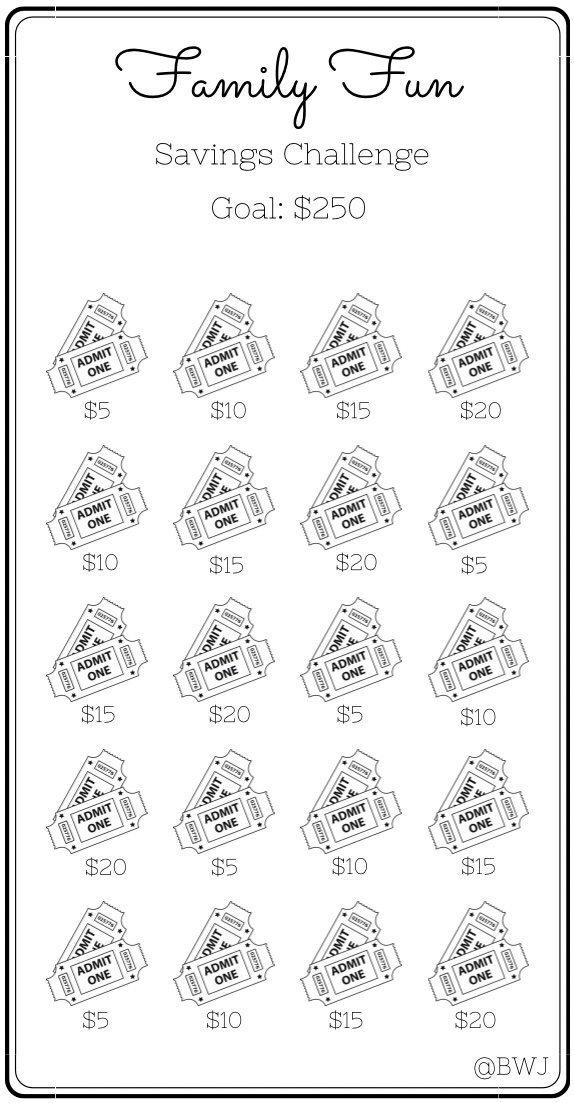
When the holiday season arrives, it’s easy to get swept up in the spirit of giving and inadvertently overspend. However, with a well-thought-out financial plan, you can celebrate joyfully without falling into the debt trap. Start by setting clear priorities. Identify who you need to buy for and what you can realistically spend on each person. This approach not only keeps your finances in check but also ensures that your gifts are meaningful and within your budget.
- Set Spending Limits: Determine a total amount you can afford to spend on gifts, decorations, and festive activities. Divide this amount among your expenses to avoid surprises.
- Use Cash or Debit: To prevent overspending, use cash or a debit card. This method keeps you grounded in reality and helps you stick to your budget.
- Track Your Purchases: Keep a record of every purchase you make. This tracking not only helps you stay within your budget but also identifies areas where you might cut back.
Remember, the essence of the holidays is not in the price tags but in the moments shared with loved ones. By planning ahead and spending wisely, you can enjoy a debt-free festive season that truly reflects the spirit of giving.
Prioritize High-Interest Debt for Maximum Savings
During the holiday season, it’s easy to get swept up in the joy of giving, but it’s crucial to stay focused on managing your financial obligations effectively. One of the smartest strategies is to tackle high-interest debt head-on. This approach not only helps in reducing your financial burden faster but also maximizes your savings over time. Concentrate on paying down debts with the highest interest rates first, such as credit cards or payday loans, which often carry exorbitant interest charges. By doing so, you’ll reduce the total amount of interest you pay and free up money for other financial goals.
- Make more than the minimum payment: By paying more than the minimum required, you can significantly cut down the interest accrued.
- Consider debt consolidation: This can simplify payments and potentially lower your interest rate.
- Utilize balance transfer offers: Take advantage of promotional periods with low or 0% interest rates to pay off debt more quickly.
Implementing these strategies during the holidays can alleviate financial stress and pave the way for a more secure financial future.
Utilize Balance Transfers and Consolidation Wisely
During the holiday season, managing debt efficiently can be crucial to maintaining financial stability. One strategic approach is to leverage balance transfers and debt consolidation. Balance transfers can help you take advantage of lower interest rates, reducing the amount you pay on your existing credit card debt. This strategy is particularly effective if you have high-interest credit cards. However, it’s essential to be mindful of any transfer fees and ensure that you can pay off the transferred balance before the introductory rate expires.
For those juggling multiple debts, debt consolidation can simplify your payments and potentially lower your monthly outlay. Consider the following benefits of consolidation:
- Simplified Payments: Combine multiple debts into a single payment to streamline your finances.
- Lower Interest Rates: Secure a loan with a lower interest rate compared to your current debts.
- Improved Cash Flow: Potentially reduce your monthly payment amount, freeing up cash for other expenses.
While these tools can be powerful, they require disciplined management to avoid falling back into debt. Always read the terms carefully and have a clear repayment plan in place.
Embrace Creative Gift-Giving to Cut Costs
Finding unique ways to give gifts during the holiday season can be a smart strategy for managing your finances while still expressing love and appreciation. Creative gift-giving not only helps cut costs but also adds a personal touch that can make your presents more meaningful. Consider these inventive ideas:
- DIY Projects: Crafting homemade gifts like candles, soaps, or knitted scarves can be both budget-friendly and heartfelt.
- Experience Over Material: Offer the gift of an experience, such as a picnic, hiking trip, or cooking class. Memories last longer than objects.
- Repurpose and Recycle: Upcycle items you already own into something new and personalized, like transforming old frames into decorative art pieces.
- Gift of Service: Provide a service like babysitting, pet sitting, or a home-cooked meal as a thoughtful and practical present.
Adopting these strategies not only helps you stay within your budget but also fosters a spirit of creativity and thoughtfulness that can be more valuable than any store-bought gift.