
In today’s complex financial landscape, managing debt effectively is a crucial skill for individuals and businesses alike. Two common strategies that often come into play are debt refinancing and debt consolidation. While both approaches aim to make debt more manageable, they serve distinct purposes and are suited to different financial situations. Understanding the nuances between debt refinancing and debt consolidation is essential for making informed decisions that can lead to improved financial health. In this article, we will delve into the fundamental differences between these two strategies, explore their respective benefits and drawbacks, and provide guidance on how to determine which option might be the best fit for your unique financial circumstances. With a clear grasp of these concepts, you’ll be better equipped to navigate the path to financial stability and success.
Understanding Debt Refinancing and Debt Consolidation
When navigating the labyrinth of financial management, understanding the nuances between debt refinancing and debt consolidation is crucial for effective decision-making. Both strategies offer pathways to streamline debt, yet they cater to distinct financial scenarios and goals.
- Debt Refinancing: This involves replacing an existing loan with a new one, typically to benefit from better interest rates or terms. It’s ideal for individuals who can secure a lower interest rate, which can reduce monthly payments and the total interest paid over time.
- Debt Consolidation: This strategy combines multiple debts into a single loan, often with a lower overall interest rate. It simplifies monthly payments by rolling various obligations into one, which can make managing finances more straightforward and reduce the risk of missing payments.
By understanding these strategies, you can tailor your approach to debt management, ensuring that your chosen method aligns with your financial objectives and current circumstances.
Key Differences Between Refinancing and Consolidation Explained
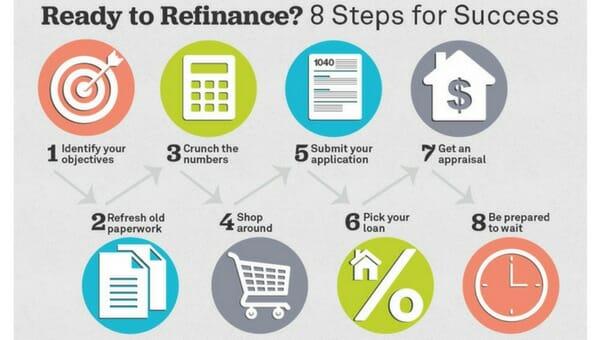
Understanding the distinction between refinancing and consolidation is crucial for anyone looking to manage their debt effectively. While both strategies aim to simplify debt management and potentially reduce costs, they operate differently. Refinancing involves replacing an existing loan with a new one, often with better terms such as a lower interest rate or extended repayment period. This approach is commonly used for large loans, like mortgages or student loans, and can result in lower monthly payments or overall interest savings.
On the other hand, consolidation combines multiple debts into a single loan, usually with a fixed interest rate and a singular monthly payment. This method is particularly beneficial for managing various high-interest debts, such as credit cards. Key benefits of consolidation include:
- Streamlined payment process
- Potentially lower interest rates
- Improved credit score due to consistent payment history
Each method has its own advantages and potential drawbacks, making it essential to evaluate personal financial circumstances and goals when choosing the right option.
Choosing the Right Strategy for Your Financial Goals
Understanding the distinction between debt refinancing and debt consolidation is crucial in crafting a strategy tailored to your financial aspirations. Debt refinancing involves replacing an existing debt with a new one, usually at a lower interest rate, which can significantly reduce your monthly payments or total interest over time. This strategy is particularly beneficial if your credit score has improved since you initially took out the loan, or if market interest rates have dropped.
On the other hand, debt consolidation merges multiple debts into a single loan, simplifying your financial obligations and often lowering the overall interest rate. This can be advantageous if you’re juggling numerous high-interest debts. Consider the following benefits of each approach:
- Debt Refinancing: Potential for lower interest rates, improved cash flow, possible reduction in loan term.
- Debt Consolidation: Streamlined payment process, reduced stress from managing multiple debts, possible lower interest rate.
Evaluating your current financial situation and long-term goals will help you decide which option aligns best with your needs.
Expert Recommendations for Managing Debt Effectively
When it comes to managing debt, leveraging expert strategies can make all the difference in your financial journey. Understanding the nuances between debt refinancing and debt consolidation is crucial. Debt refinancing involves replacing an existing loan with a new one, typically to secure a lower interest rate or better terms. This method can significantly reduce monthly payments and overall interest costs, providing immediate relief to your financial burden.
On the other hand, debt consolidation simplifies your financial landscape by merging multiple debts into a single loan. This approach offers several advantages:
- Streamlined payments: Manage one monthly payment instead of juggling several.
- Potential for lower interest rates: Especially beneficial if consolidating high-interest credit card debt.
- Improved credit score: Regular, on-time payments on a consolidated loan can positively impact your credit.
Both strategies have their merits, and choosing the right one depends on your specific financial situation. Consulting with a financial advisor can provide personalized insights, helping you decide whether refinancing or consolidation aligns with your goals.