
In today’s fast-paced financial landscape, managing debt effectively is a crucial skill that can significantly impact your overall financial health and future stability. While taking on debt can sometimes be a necessary step in achieving personal or professional goals, accumulating excessive debt can quickly become a burden that hampers your financial freedom. The challenge lies in striking a balance between paying off existing loans and resisting the temptation to accrue additional debt. This article will provide you with practical strategies and actionable insights to help you navigate this delicate balance with confidence. By understanding and implementing these techniques, you can pave the way to a debt-free future while maintaining financial discipline and peace of mind.
Understanding Your Financial Landscape
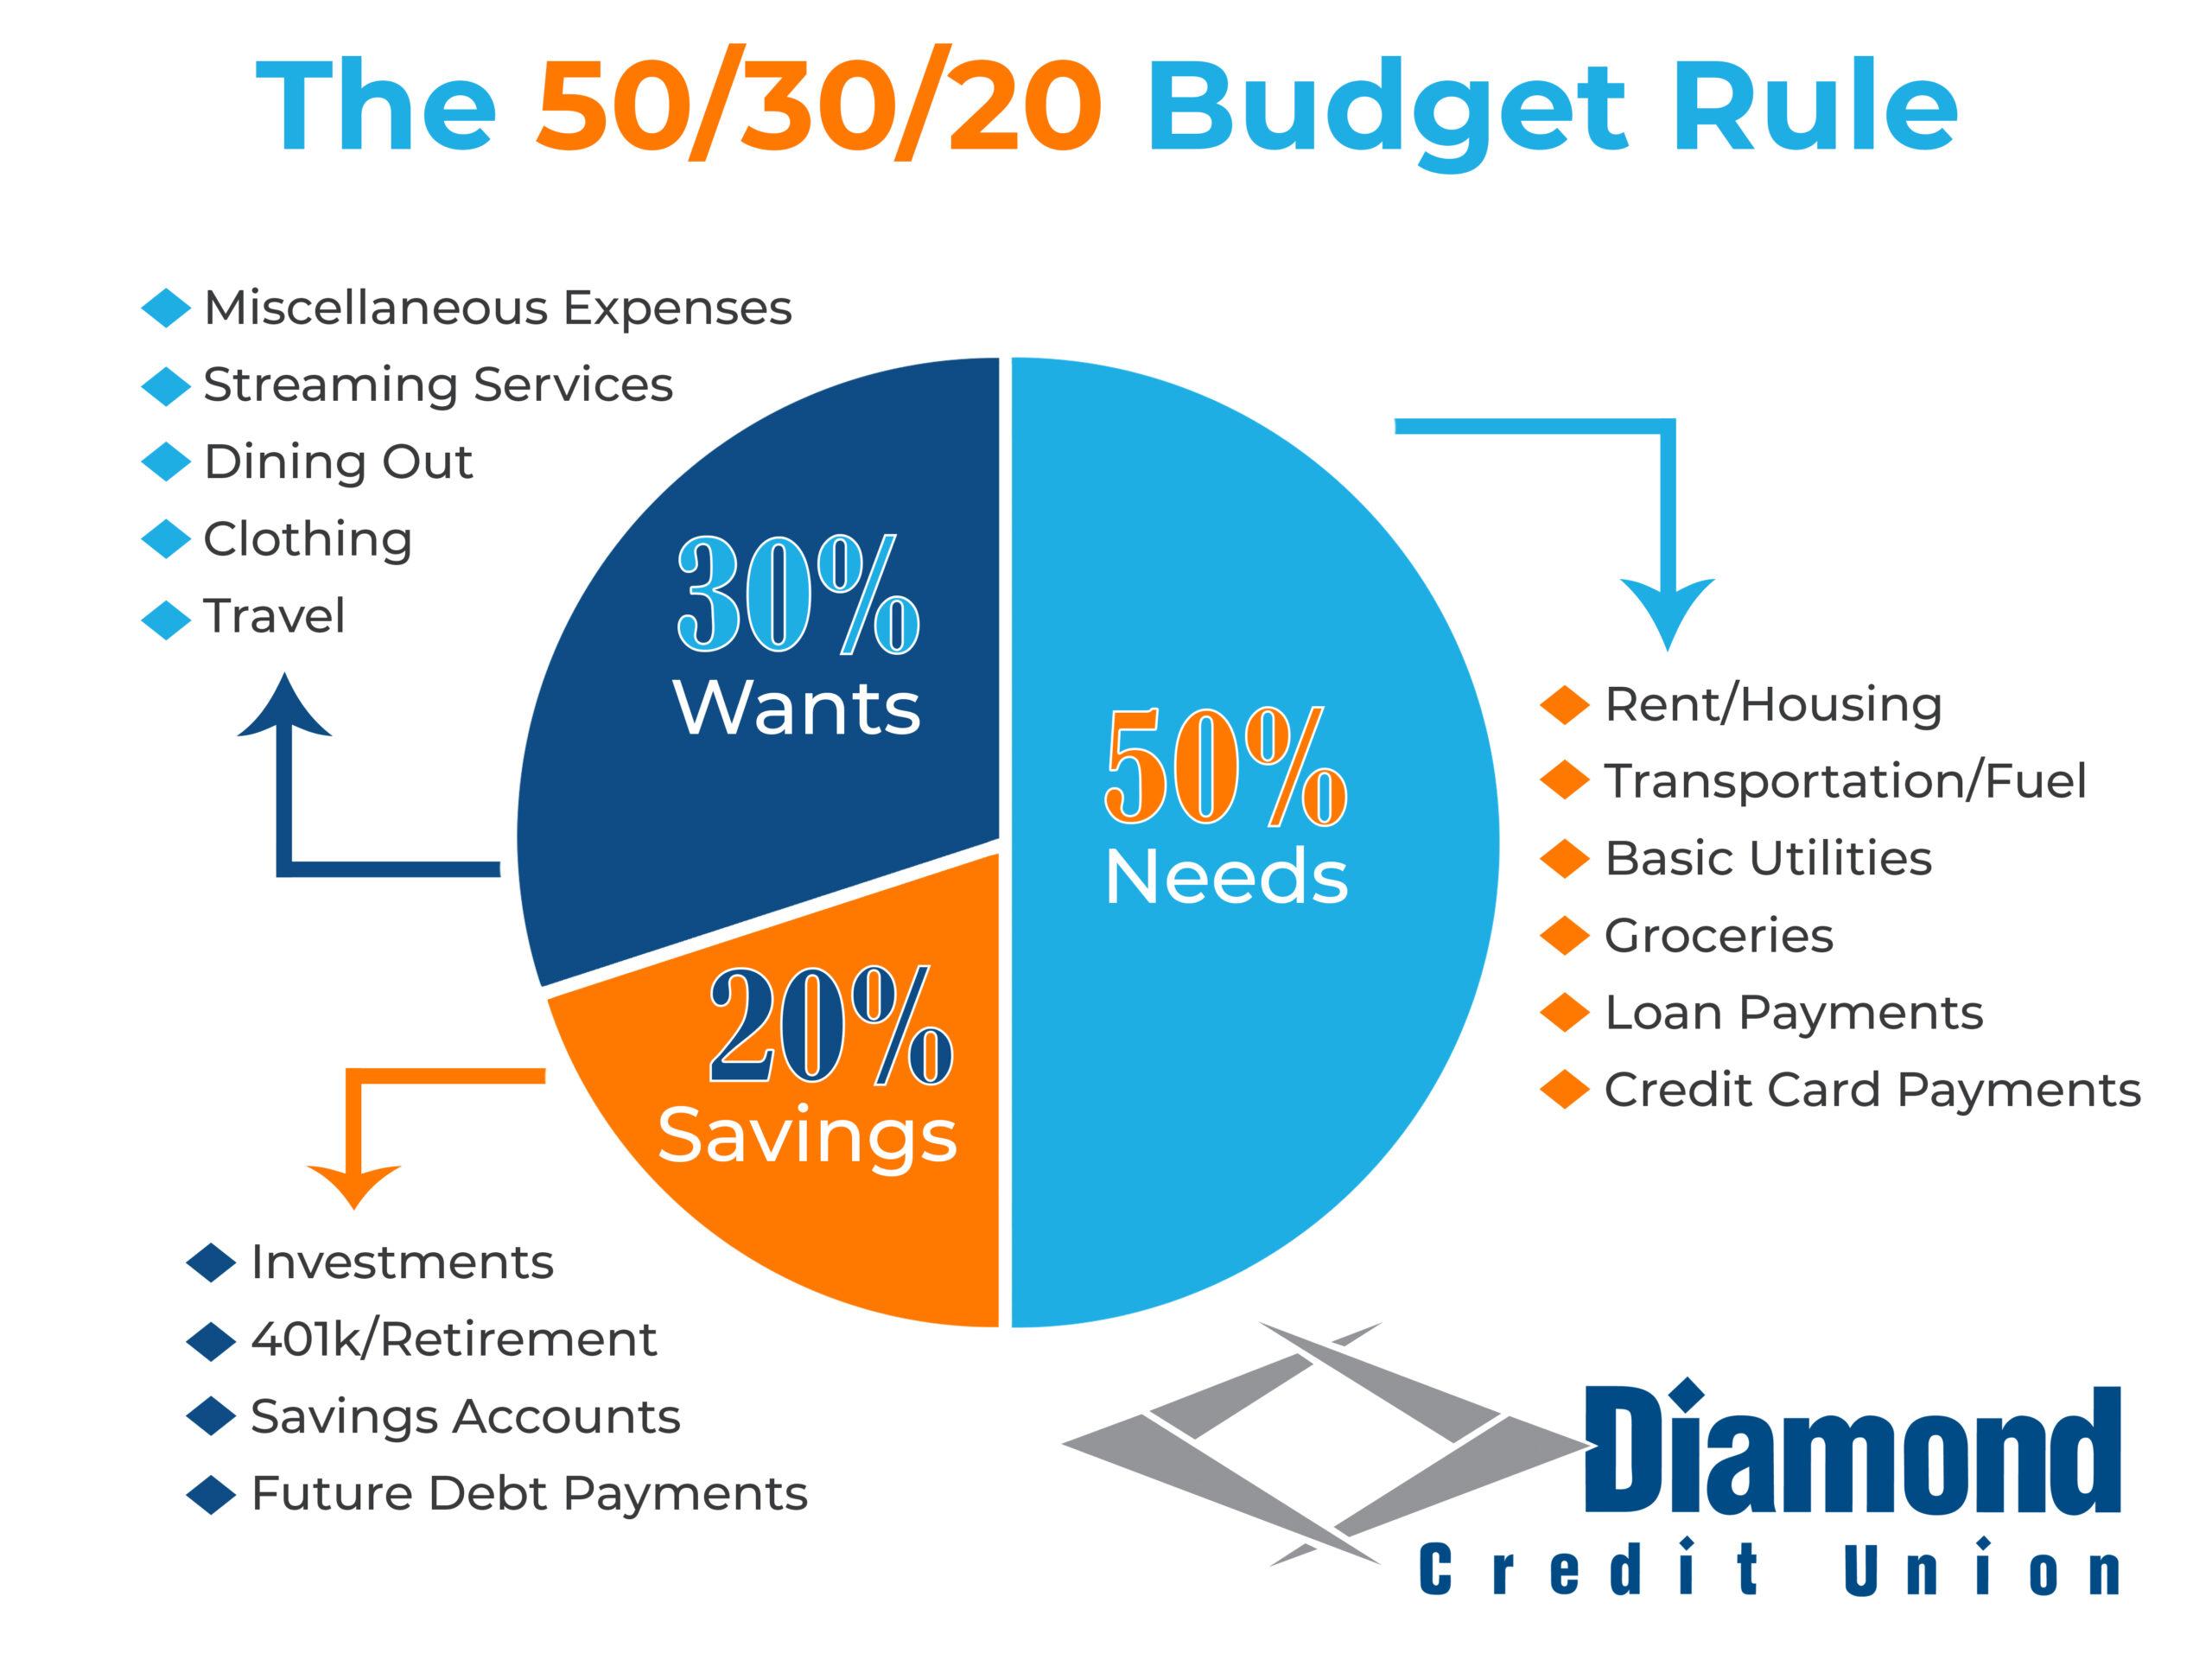
Taking control of your financial landscape is crucial to avoid the pitfalls of accumulating more debt while managing existing loans. Start by creating a detailed budget that outlines your monthly income and expenses. Prioritize your spending by focusing on essentials such as housing, utilities, and groceries. Identify areas where you can cut back, like dining out or subscription services, and reallocate those funds toward debt repayment. By doing so, you’ll free up cash to pay down existing loans without resorting to additional borrowing.
- Consolidate your loans: If you have multiple debts, consider consolidating them into a single loan with a lower interest rate.
- Negotiate better terms: Contact your creditors to discuss the possibility of reducing interest rates or extending payment terms.
- Build an emergency fund: Set aside a small amount each month to build a cushion that can prevent the need for new debt in emergencies.
Additionally, use cash or debit instead of credit for everyday purchases to maintain discipline and avoid the temptation of overspending. Regularly review your financial situation and adjust your strategy as needed to stay on track with your debt repayment goals. By taking these proactive steps, you’ll be well-equipped to manage your current loans effectively while steering clear of additional debt.
Crafting a Realistic Budget That Prioritizes Debt Repayment
Creating a budget that effectively focuses on debt repayment requires a strategic approach to both income and expenditures. Begin by listing all your sources of income and essential expenses. This provides a clear picture of what you have to work with. Categorize your expenses into necessary and discretionary, ensuring that your essentials are covered first. This might include rent or mortgage, utilities, groceries, and minimum debt payments. Once these are accounted for, prioritize your debt repayment by allocating any remaining funds towards the debt with the highest interest rate, commonly known as the avalanche method, or start with the smallest balance, known as the snowball method, depending on what keeps you motivated.
While creating your budget, consider these important tips to keep your debt repayment on track:
- Automate your payments to ensure you never miss a due date, avoiding late fees and additional interest.
- Cut unnecessary expenses such as subscription services you no longer use or dining out too frequently.
- Increase your income by taking on a side job or selling unused items to bolster your repayment efforts.
- Regularly review and adjust your budget to reflect any changes in your financial situation, ensuring you stay on track with your goals.
By maintaining a clear focus on debt repayment within your budget, you are actively taking steps to regain financial freedom without accumulating additional debt.
Exploring Strategies to Increase Income and Reduce Expenses
Discovering effective strategies to boost income while slashing expenses is essential for maintaining financial health and avoiding further debt accumulation. One approach is to leverage your skills and turn hobbies into side hustles. Whether it’s freelance writing, graphic design, or even baking, these activities can generate additional income streams. Consider exploring platforms like Upwork or Etsy to showcase your talents and attract potential clients or customers.
On the expense side, adopting a minimalist lifestyle can significantly reduce unnecessary spending. Start by evaluating your monthly subscriptions and cancel those that are rarely used. Cooking at home instead of dining out and buying generic brands are small adjustments that add up over time. Create a budget and track your spending to identify areas where you can cut back. By focusing on increasing income and decreasing expenses, you create a financial buffer that makes it easier to manage existing debts without resorting to new ones.
Leveraging Financial Tools and Resources for Debt Management
To effectively manage debt without accumulating more, it’s crucial to utilize the right financial tools and resources. Budgeting apps are an excellent starting point. They provide a clear picture of your financial situation, helping you allocate funds towards debt repayment while maintaining essential expenses. Popular choices include YNAB (You Need A Budget) and Mint, which offer user-friendly interfaces and insightful analytics. Additionally, debt management software like Undebt.it can assist in organizing and prioritizing loans, ensuring you follow a structured repayment plan. These platforms often include features that simulate different payoff strategies, allowing you to choose the most cost-effective path.
Furthermore, consider leveraging financial literacy resources to deepen your understanding of money management. Many websites and online courses offer free advice on debt reduction strategies. It’s also beneficial to explore credit counseling services, where professionals can provide personalized guidance and negotiate better terms with creditors. Remember, knowledge is power; by equipping yourself with these tools and resources, you can take proactive steps to eliminate debt while resisting the temptation to take on more.