
In today’s fast-paced world, managing finances can be a daunting task, especially when it comes to planning for significant family expenses. Whether it’s funding a child’s education, preparing for a wedding, or saving for a dream vacation, large expenses can often seem overwhelming. However, with strategic planning and a proactive approach, you can navigate these financial challenges without the burden of worry. This article will guide you through effective strategies to anticipate, budget, and save for substantial family costs, ensuring that you can meet these obligations with confidence and peace of mind. By adopting a structured financial plan, you can transform potential stressors into manageable goals, securing a stable financial future for your family.
Understanding the Nature of Large Family Expenses
When navigating the financial landscape of a large family, it’s crucial to recognize the diverse array of expenses that may arise. These costs can range from everyday necessities to significant, one-time investments. To manage these effectively, it’s important to categorize them into predictable and unpredictable expenses. Predictable expenses might include groceries, utilities, and education costs, while unpredictable expenses could involve medical emergencies, car repairs, or sudden home maintenance needs.
Understanding these categories helps in creating a more comprehensive budget. Consider the following strategies to manage them effectively:
- Prioritize Needs Over Wants: Ensure that essential expenses are covered first to avoid financial strain.
- Build an Emergency Fund: Allocate a portion of your budget to cover unforeseen expenses.
- Invest in Insurance: Consider health, home, and auto insurance to mitigate potential high-cost events.
- Review and Adjust Regularly: Periodically reassess your family’s financial situation to adapt to changing needs and circumstances.
By understanding the nature of these expenses, families can better prepare and reduce the stress associated with financial management.
Building a Comprehensive Family Budget Strategy
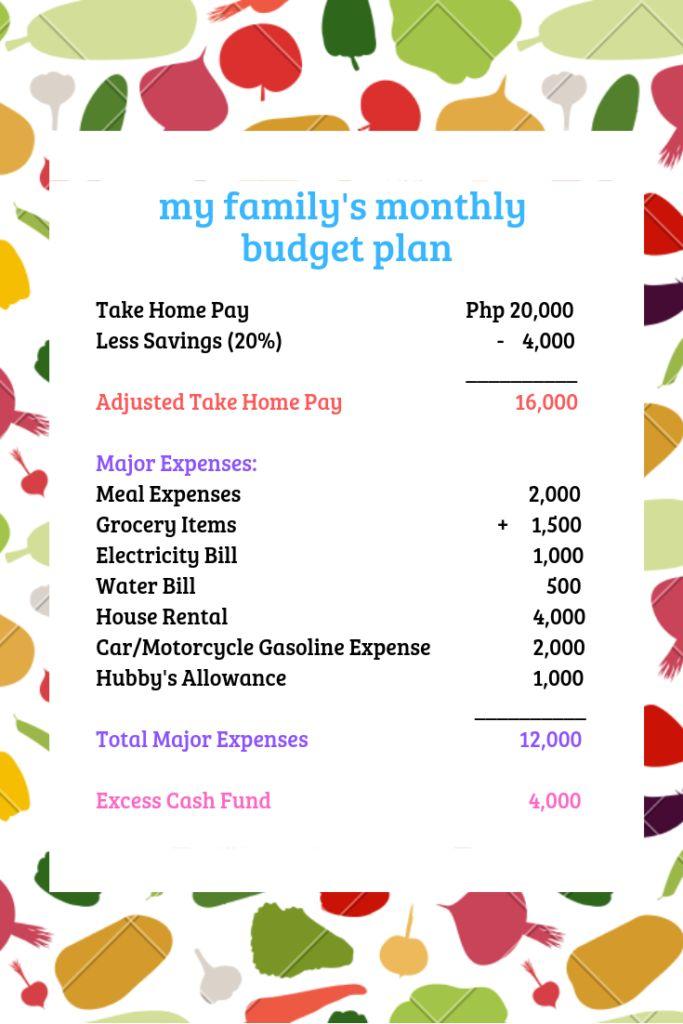
When preparing for significant expenses within a family budget, it’s crucial to adopt a structured approach that accommodates both expected and unexpected costs. Start by identifying all major upcoming expenses, such as educational fees, family vacations, or home improvements. Create a timeline for these expenditures and categorize them based on urgency and priority. This will help you allocate resources effectively without disrupting your financial stability.
Incorporate the following strategies to enhance your budget planning:
- Establish an emergency fund: Set aside a specific amount monthly to build a reserve for unforeseen expenses, which can prevent financial strain.
- Review and adjust regularly: Schedule monthly reviews of your budget to account for any changes in income or expenses, ensuring your plan remains relevant and efficient.
- Engage the whole family: Encourage family members to contribute ideas for saving and prioritize spending. This fosters a sense of shared responsibility and teamwork.
By implementing these steps, you can effectively manage large family expenses with confidence, ensuring your financial health is maintained while meeting your family’s needs.
Exploring Savings Options and Investment Opportunities
When planning for substantial family expenses, understanding the array of savings options and investment opportunities is crucial. High-yield savings accounts offer a safe place to grow your funds with competitive interest rates, making them an excellent choice for short-term goals. For those looking to set aside money for future educational expenses, consider opening a 529 College Savings Plan, which provides tax advantages and potential growth over time.
Beyond traditional savings, diversifying your investment portfolio can also play a significant role in preparing for large expenses. Mutual funds and index funds offer exposure to a broad range of assets, helping to mitigate risk while capitalizing on market growth. If you’re seeking more control over your investments, consider self-directed IRAs or Roth IRAs, which allow for tax-free withdrawals under certain conditions. Remember, balancing your risk tolerance with your financial goals is key to ensuring a stress-free financial future.
Utilizing Insurance and Emergency Funds for Financial Security
One of the pillars of financial security is having a robust plan for those unexpected, large expenses that families inevitably face. Insurance and emergency funds are two crucial tools in this regard. Insurance acts as a safety net, helping to mitigate the financial blow of unforeseen events. Ensure your family is covered with the right types of insurance, such as:
- Health Insurance: Covers medical expenses and protects against high healthcare costs.
- Homeowners or Renters Insurance: Safeguards your home and belongings from damage or theft.
- Auto Insurance: Protects against the costs associated with vehicle accidents and damages.
- Life Insurance: Provides financial support to your family in the event of your untimely passing.
Alongside insurance, maintaining an emergency fund is essential. This fund should be easily accessible and cover three to six months of living expenses. It acts as a financial buffer, providing peace of mind and allowing you to address unexpected costs without derailing your financial stability. By combining the protective coverage of insurance with the security of an emergency fund, you create a comprehensive safety net that ensures your family’s financial well-being is maintained, even in the face of large, unexpected expenses.