
Debt can feel like a heavy anchor, weighing down your financial freedom and peace of mind. However, breaking free from its grasp is not only possible but also within your reach with the right strategies. In this article, we will explore simple yet effective ways to accelerate your journey out of debt. By implementing these actionable steps, you can regain control of your finances and move toward a more secure and prosperous future. Whether you’re dealing with credit card balances, student loans, or other forms of debt, these practical tips will empower you to reduce what you owe and achieve financial liberation faster than you might have thought possible.
Create a Realistic Budget and Stick to It
Crafting a budget that mirrors your actual income and expenses is a crucial step toward debt freedom. Start by tracking your monthly earnings and expenditures to identify areas where you can cut back. Prioritize your spending by focusing on essential needs like housing, utilities, and groceries. Use any surplus to make extra payments on your debt. Remember, the goal is to spend less than you earn consistently.
- Track Every Expense: Use budgeting apps or spreadsheets to keep a detailed record of your spending.
- Set Realistic Goals: Break down your debt into manageable chunks and set achievable targets for repayment.
- Adjust as Needed: Life changes, and so should your budget. Regularly review and adjust to stay on track.
- Avoid New Debt: Stick to your budget and resist the temptation to accrue more debt, especially for non-essential items.
By diligently following your budget, you’ll be able to allocate more resources towards debt repayment, bringing you closer to financial freedom.

Prioritize High-Interest Debts for Quicker Payoff
When tackling debt, a strategic approach is essential. Start by focusing on high-interest debts, which can quickly accumulate and become overwhelming. These debts, often from credit cards or payday loans, should be your top priority. By directing your resources towards them, you reduce the amount of interest accruing over time, allowing for a faster payoff. This method not only saves you money but also helps in improving your credit score more effectively.
- Identify all your debts and list them by interest rate.
- Allocate extra payments to the debt with the highest interest rate first, while making minimum payments on others.
- Track your progress regularly to stay motivated and adjust your strategy if needed.
By concentrating on these high-interest liabilities, you gain momentum, which can boost your confidence and accelerate your journey to financial freedom. Remember, every dollar saved on interest is a dollar closer to being debt-free.

Explore Additional Income Opportunities
Finding ways to increase your income can be a powerful strategy for accelerating your journey to financial freedom. Consider these innovative methods to boost your earnings and tackle your debt more effectively:
- Freelancing: Utilize your skills in writing, graphic design, or programming to earn extra money on platforms like Upwork or Fiverr.
- Online Tutoring: Share your knowledge in subjects you excel at by teaching students around the globe on platforms like VIPKid or Tutor.com.
- Gig Economy Jobs: Join the ranks of ride-sharing or food delivery drivers with companies like Uber, Lyft, or DoorDash for flexible income opportunities.
- Renting Out Space: If you have a spare room or property, consider listing it on Airbnb to generate additional revenue.
- Sell Unused Items: Declutter your home and sell unwanted items on eBay or Facebook Marketplace to make quick cash.
By diversifying your income streams, not only do you create a buffer against financial uncertainty, but you also pave the way for more aggressive debt repayment, ultimately achieving a debt-free life faster.
Utilize Debt Consolidation for Simplified Payments
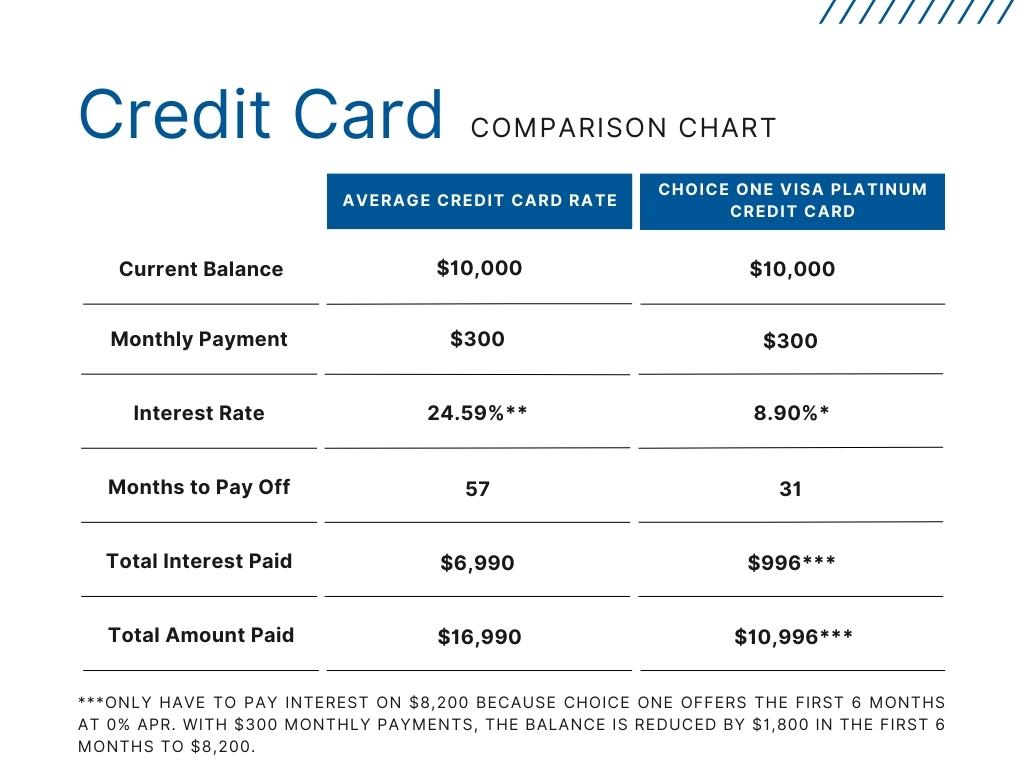
Debt consolidation can be a game-changer in managing your finances. By combining multiple debts into a single loan, you can benefit from a lower interest rate and make your financial commitments more manageable. This process simplifies your payments by transforming numerous due dates and interest rates into one consistent monthly payment. Here’s how you can leverage debt consolidation effectively:
- Assess Your Debts: Gather all the details of your existing debts, including balances and interest rates. This will help you determine the potential savings and decide if consolidation is the right step.
- Research Consolidation Options: Look into different consolidation methods, such as personal loans, balance transfer credit cards, or home equity loans. Each has its pros and cons, so choose the one that best aligns with your financial goals.
- Compare Interest Rates: Seek out lenders offering competitive interest rates. The goal is to secure a lower rate than your current debts to maximize savings.
- Create a Repayment Plan: Once consolidated, stick to a disciplined repayment schedule. This consistency is crucial in eliminating debt and avoiding future financial pitfalls.
Embracing debt consolidation can streamline your financial obligations and set you on a clearer path to becoming debt-free. With fewer payments to juggle, you’ll find it easier to manage your finances and focus on what truly matters.