
In today’s fast-paced world, managing household finances can often feel overwhelming, especially for families juggling multiple expenses. However, establishing a robust budgeting system is crucial not only for meeting immediate financial obligations but also for securing long-term financial stability. This article, “,” is designed to guide you through the essentials of creating and maintaining an effective family budget. By following our expert advice and practical tips, you will gain the confidence and skills needed to allocate resources wisely, anticipate future expenses, and achieve your family’s financial goals. Whether you’re new to budgeting or looking to refine your approach, this comprehensive guide will empower you to take control of your family’s financial future with authority and ease.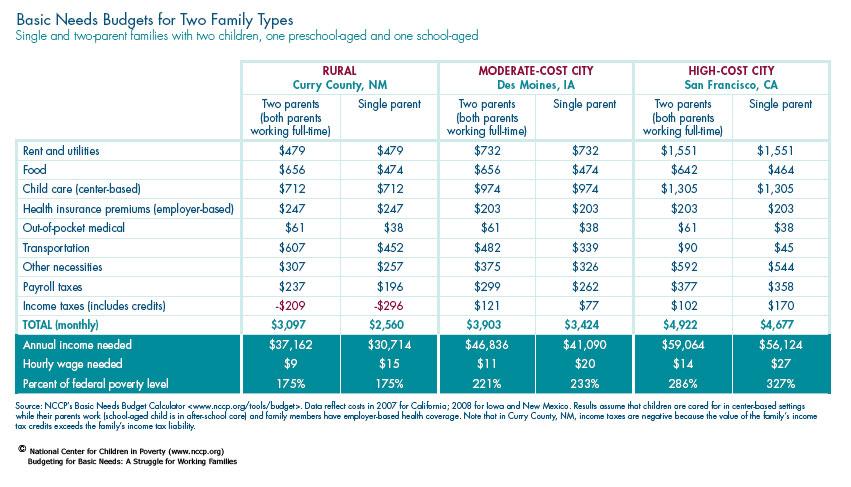
Understanding Family Expenses for Effective Budgeting
One of the cornerstones of successful family budgeting is a comprehensive understanding of where your money is going. Begin by categorizing your expenses to gain clarity. This can be broken down into essential and non-essential expenditures. Essential expenses are those that are crucial for daily living, such as:
- Housing costs – rent or mortgage payments
- Utilities – electricity, water, and gas
- Groceries – food and household supplies
- Transportation – car payments, fuel, and public transit
- Healthcare – insurance and medical expenses
Non-essential expenses, on the other hand, are those that can be adjusted or minimized without affecting your family’s quality of life. These include:
- Dining out – restaurants and takeout
- Entertainment – movies, games, and subscriptions
- Personal spending – clothing and hobbies
- Vacations - travel and leisure activities
By clearly distinguishing between these categories, you can identify areas where cuts can be made and set priorities accordingly. This strategic approach not only aids in maintaining financial health but also ensures that the family can comfortably meet its needs while still enjoying life’s little luxuries.
Creating a Realistic Monthly Budget Plan
Crafting a budget that reflects the true dynamics of family life requires a strategic approach. Start by evaluating your household’s income streams, ensuring you account for all sources, including salaries, freelance work, and any passive income. Next, list your fixed expenses such as mortgage or rent, insurance, and utilities. This foundational step provides a clear picture of your financial landscape and highlights areas where adjustments might be necessary.
To create a budget that truly works, consider your variable expenses. These include groceries, entertainment, and dining out. Establish realistic spending limits by reviewing past expenditures and prioritizing needs over wants. Use tools like spreadsheets or budgeting apps to track these expenses in real-time. Incorporate an emergency fund into your plan, setting aside a small amount each month to cushion unexpected financial challenges. By adhering to these guidelines, families can maintain financial stability and work towards their long-term goals.
Maximizing Savings with Smart Financial Strategies
Creating a family budget that truly works involves more than just tracking expenses—it’s about strategically planning to maximize savings. Start by identifying and categorizing your family’s essential expenses, such as housing, utilities, groceries, and education. Then, evaluate discretionary spending and prioritize items that add real value to your family’s lifestyle. An effective strategy is to allocate a specific percentage of your income to savings and stick to it diligently. Aim for at least 20% of your total income, directing funds towards an emergency fund, retirement savings, and other long-term goals.
- Automate Savings: Set up automatic transfers to your savings accounts to ensure consistent contributions without the temptation to spend.
- Use Cash-Back Programs: Take advantage of credit card rewards and cash-back offers for purchases you already make, funneling the rewards directly into savings.
- Review Subscriptions: Regularly audit subscription services to eliminate those that are underutilized, redirecting those funds to your savings.
- Embrace Meal Planning: Planning meals in advance reduces waste and allows for bulk purchasing, which can significantly cut down grocery bills.
By integrating these smart financial strategies, families can not only manage their budgets effectively but also enhance their financial stability and peace of mind.
Involving the Whole Family in Budgeting Discussions
Engaging every member of the household in financial planning is not just beneficial—it’s essential for fostering a collaborative environment. Start by organizing a family meeting where each person, regardless of age, can share their perspective and contribute ideas. This not only instills a sense of responsibility but also helps everyone understand the family’s financial priorities. Use simple tools like visual aids or budgeting apps that can make the process more accessible and less intimidating for younger family members.
- Set Clear Goals: Define what you’re saving for, whether it’s a family vacation, a new car, or an emergency fund.
- Assign Roles: Let each family member take charge of a specific area, like groceries, entertainment, or utilities.
- Celebrate Milestones: Acknowledge and reward achievements when financial goals are met, reinforcing positive habits.
By involving everyone, you create a unified approach to managing money that can lead to more informed decisions and a stronger family bond. Remember, open communication and shared responsibility are the cornerstones of successful family budgeting.