
Planning for significant family events, such as weddings, milestone birthdays, or reunions, can often feel like navigating a financial labyrinth. These occasions are not only emotionally significant but also come with substantial costs that, if not managed wisely, can disrupt other financial goals such as buying a home, saving for education, or building a retirement fund. This guide is designed to equip you with practical strategies to plan and save for these memorable events without derailing your broader financial objectives. With a confident approach and disciplined planning, you can ensure that your family celebrations are both joyous and financially sustainable. Let’s delve into effective techniques for budgeting, saving, and prioritizing, so you can celebrate life’s important moments with peace of mind and financial stability.
Setting Priorities to Balance Family Events and Financial Goals
When it comes to balancing family events and financial goals, setting priorities is crucial. Begin by identifying what truly matters to your family. Is it a milestone birthday, a dream vacation, or saving for your child’s education? Clearly outline these events and categorize them based on urgency and importance. Consider creating a family vision board to visualize these priorities, which can foster a shared sense of purpose. This approach not only keeps everyone on the same page but also helps in making informed decisions about where to allocate resources.
- Assess and list all upcoming family events – From weddings to family reunions, write down everything.
- Evaluate your financial goals – Savings, investments, and retirement plans should be clearly outlined.
- Rank priorities – Determine which events align with long-term financial goals and which can be adjusted or postponed.
- Allocate budgets accordingly – Assign a realistic budget to each event, ensuring it complements your overall financial strategy.
- Communicate with family members – Regular discussions can help in managing expectations and making collective decisions.
By following these steps, you can create a harmonious balance between cherishing family moments and achieving financial stability. Remember, it’s all about finding that sweet spot where your family’s happiness meets financial responsibility.
Creating a Realistic Budget for Every Major Family Occasion
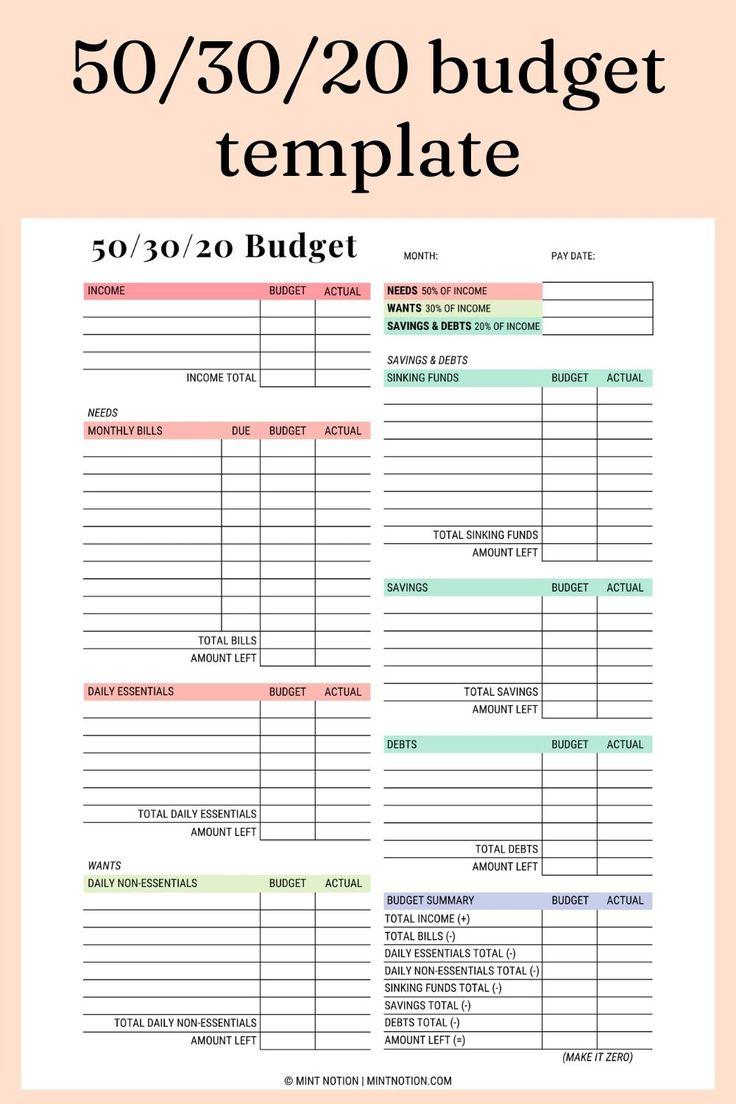
When planning for a family event, the key is to approach it with a balanced mindset. It’s crucial to prioritize spending without compromising your long-term financial goals. Begin by categorizing the event expenses into essential and non-essential. This can include:
- Venue and accommodation
- Catering and food supplies
- Entertainment and activities
- Decorations and gifts
Once you’ve identified these categories, set a realistic budget for each. Research average costs in your area and don’t hesitate to seek out deals or negotiate prices. Consider leveraging resources like community spaces for venues or potluck-style meals to cut down on costs. Always remember to incorporate a contingency fund to cushion unexpected expenses, ensuring that you’re prepared for any surprises while keeping other financial goals intact.
Smart Saving Strategies to Ensure Financial Stability
When preparing for significant family events such as weddings, milestone birthdays, or reunions, it’s crucial to adopt smart saving strategies that align with your broader financial objectives. Start by establishing a dedicated savings account for each event. This approach not only keeps funds organized but also minimizes the temptation to dip into these savings for other purposes. Implement automatic transfers to these accounts, ensuring a steady and consistent contribution over time. Additionally, review your current expenses and identify areas where you can cut back without sacrificing quality of life, such as dining out less frequently or opting for more affordable entertainment options.
To further bolster your savings efforts, consider employing a mix of these practical tactics:
- Set Clear Priorities: Identify which events are most important and allocate funds accordingly.
- Create a Realistic Budget: Outline all potential expenses related to each event and stick to your budget.
- Use Cash-Back and Rewards: Leverage credit card rewards or cash-back programs to offset costs.
- Explore DIY Solutions: For events like weddings, consider DIY decorations or catering to reduce expenses.
- Seek Group Discounts: If planning a large event, inquire about group rates or discounts for services and venues.
By integrating these strategies into your financial planning, you can enjoy meaningful family celebrations without compromising your other financial goals. These practices not only enhance your savings discipline but also provide peace of mind knowing that your financial future remains secure.
Leveraging Financial Tools to Maximize Savings and Minimize Stress
Planning for significant family events, such as weddings, milestone birthdays, or family vacations, can be a daunting task. However, utilizing the right financial tools can help you save effectively while maintaining your other financial goals. Here are some strategies to consider:
- Budgeting Apps: Utilize apps like Mint or YNAB to track your expenses and identify areas where you can cut back. This will allow you to allocate more funds towards your event without sacrificing other savings goals.
- High-Yield Savings Accounts: Open a dedicated high-yield savings account for your event. This not only keeps your savings separate from other funds but also earns you more interest over time.
- Automated Transfers: Set up automatic transfers from your checking account to your event savings account. This ensures consistent saving without the need for constant manual input.
- Cashback and Rewards Programs: Leverage credit cards that offer cashback or rewards points for your everyday purchases. Accumulate these rewards and use them to offset costs related to your event.
By strategically using these financial tools, you can plan and save for your family event with confidence, ensuring that you stay on track with all your financial objectives.