Securing a bright future for your child often begins with a solid educational foundation, and a 529 plan is a powerful tool to help you achieve just that. As the cost of education continues to rise, many parents are seeking effective strategies to manage these expenses while maximizing their savings. In this guide, we will walk you through the essential steps to open and fund a 529 plan, a tax-advantaged savings vehicle designed specifically for education expenses. With a confident grasp of the process, you’ll be equipped to make informed decisions that align with your financial goals and provide your child with the educational opportunities they deserve. Whether you’re just starting to explore savings options or ready to take action, this article will serve as your comprehensive roadmap to navigating the world of 529 plans with ease and assurance.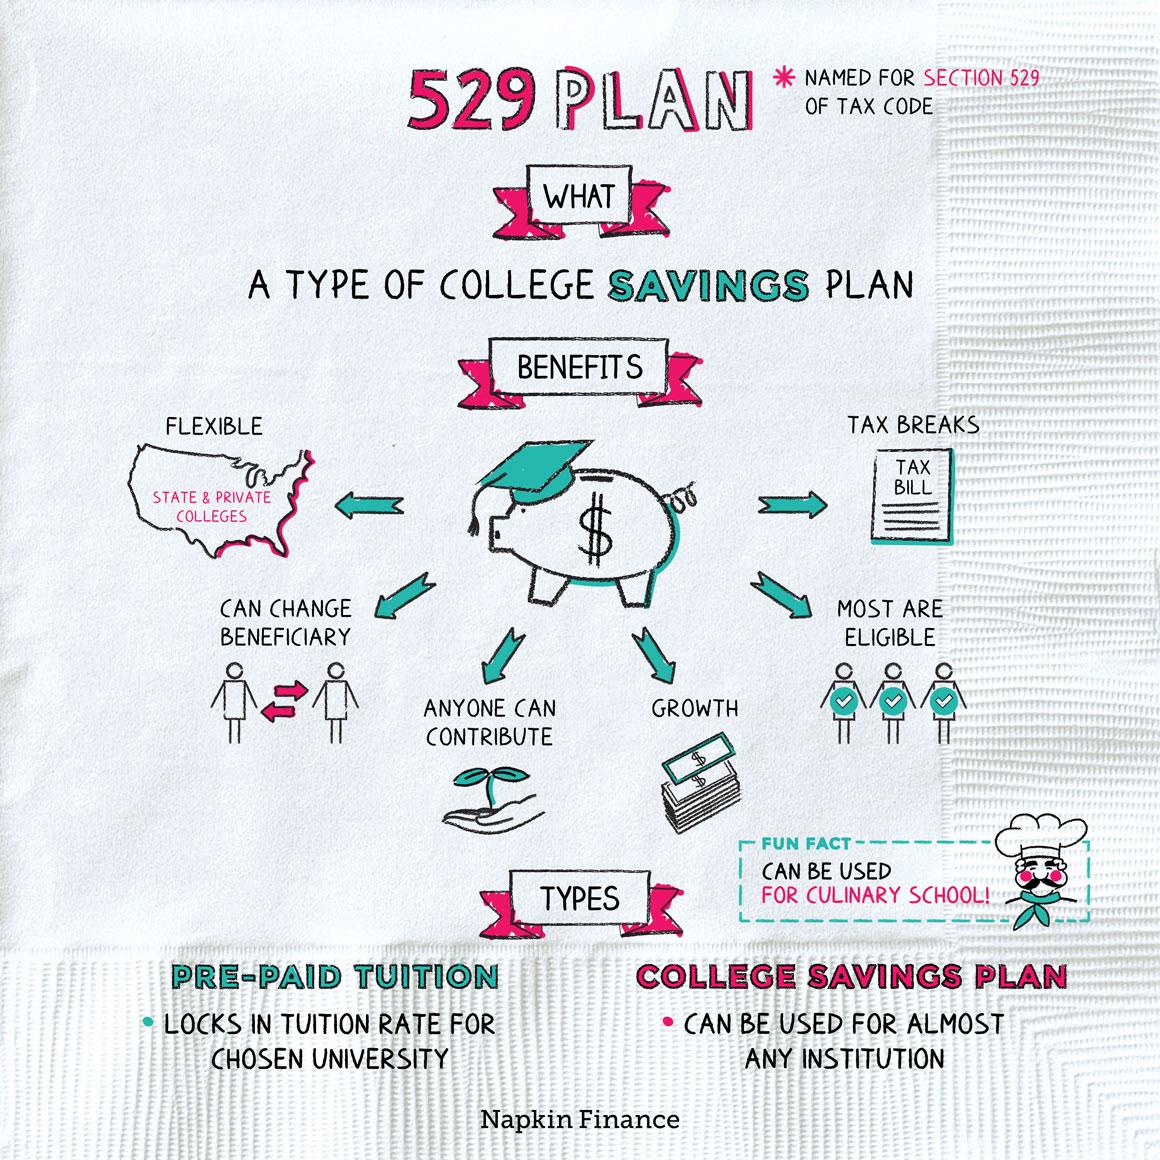
Understanding the Basics of a 529 Plan
A 529 plan is a powerful tool designed to help families save for future education costs, offering both flexibility and tax advantages. At its core, a 529 plan is a state-sponsored investment account that allows contributions to grow tax-free, provided the funds are used for qualified education expenses. These plans can cover a wide range of educational costs, including tuition, fees, books, and even room and board in some cases.
Key Features of a 529 Plan:
- Tax Benefits: Contributions grow tax-free, and withdrawals for qualified expenses are also tax-free.
- High Contribution Limits: Unlike other savings plans, 529 plans often have high contribution limits, allowing you to save significantly over time.
- Flexibility: Funds can be used at most accredited colleges and universities, and even some international institutions.
- Transferable: If one child doesn’t use the funds, they can be transferred to another beneficiary, such as a sibling.
Choosing the Right 529 Plan for Your Family
When it comes to securing a robust educational future for your child, selecting the ideal 529 plan is a critical step. With a myriad of options available, it’s important to focus on a few key factors that can help streamline your decision-making process. Consider the following aspects:
- Tax Benefits: Look for plans that offer significant tax advantages, such as tax-free withdrawals for qualified educational expenses and potential state tax deductions.
- Investment Options: Evaluate the range of investment choices. Some plans offer age-based portfolios that adjust automatically as your child gets closer to college age, while others provide static options for more hands-on management.
- Fees and Expenses: Compare the fee structures of different plans. Lower fees can significantly enhance your savings over time, so it’s crucial to understand the costs involved.
- Flexibility: Consider the plan’s flexibility in terms of beneficiary changes and use of funds. Some plans allow you to switch beneficiaries or use funds for a broad range of educational purposes, providing added peace of mind.
By weighing these factors, you can make an informed choice that aligns with your family’s financial goals and educational aspirations.
Step-by-Step Guide to Opening a 529 Account
Embarking on the journey to open a 529 account is a commendable step toward securing your child’s educational future. To start, research and choose the right 529 plan that suits your needs. This could involve comparing state-sponsored plans and understanding the tax benefits associated with each. Once you’ve settled on a plan, gather necessary personal information, such as your Social Security number and your child’s details. You’ll also need to decide on an initial contribution amount and select your preferred investment options within the plan.
Next, initiate the account setup process, which can typically be completed online through the plan’s website. Follow these steps:
- Complete the application form with accurate details.
- Choose how you want to fund the account initially, whether via a one-time payment or setting up automatic contributions.
- Review the terms and conditions, ensuring you understand the fees and investment risks involved.
After the account is established, consider setting up a consistent funding strategy to maximize the plan’s growth potential. Regular contributions, even if modest, can significantly benefit from compounding over time.
Effective Strategies for Funding Your Child’s 529 Plan
Maximizing the potential of your child’s 529 plan requires strategic funding approaches that align with your financial goals. Begin by setting up a systematic contribution schedule. Automated monthly contributions can help you stay consistent, and even small amounts can grow significantly over time thanks to compound interest. Consider leveraging windfalls such as tax refunds or bonuses to make larger, one-time contributions to the account. These infusions can dramatically enhance the growth potential of the fund.
Another effective tactic is to engage family members in the funding process. Encourage grandparents and other relatives to contribute to the 529 plan instead of traditional gifts for birthdays or holidays. Many plans offer options for gift contributions, making it easy for loved ones to help invest in your child’s future. Additionally, look into employer-sponsored plans or incentives. Some employers offer matching contributions or payroll deduction options for 529 plans, providing a valuable boost to your funding efforts. By utilizing these strategies, you can effectively build a robust financial foundation for your child’s education.