
In an ever-evolving financial landscape, securing your family’s future requires more than just saving pennies in a jar or maintaining a rainy-day fund. It demands a strategic approach to long-term financial planning that encompasses everything from retirement savings to education funds, and from investment portfolios to estate planning. This guide will empower you with the knowledge and tools needed to navigate the complexities of financial planning with confidence. By setting clear, achievable goals and implementing a well-structured plan, you can ensure your family’s financial stability and peace of mind for generations to come. Whether you’re just starting out or looking to refine your existing strategy, this article will provide you with the insights and steps necessary to build a robust financial foundation tailored to your family’s unique needs and aspirations.
Understanding Your Financial Landscape
Before embarking on any financial journey, it is essential to grasp the full scope of your current financial standing. This involves assessing all income sources, expenses, debts, and assets. Start by listing your monthly income streams and contrasting them against your regular expenses. Don’t overlook irregular expenses, such as annual insurance payments or maintenance costs, which can often be forgotten but have a significant impact when they arise.
- Calculate your total net worth by summing up all your assets and subtracting liabilities.
- Identify patterns in your spending habits and see where you can make adjustments.
- Consider the inflation rate and how it may affect your savings and investments over time.
Armed with this knowledge, you can make informed decisions and set realistic, achievable financial goals for your family. isn’t just about knowing numbers; it’s about gaining insight into your financial behavior and how it aligns with your family’s long-term aspirations.
Setting Clear and Achievable Financial Objectives
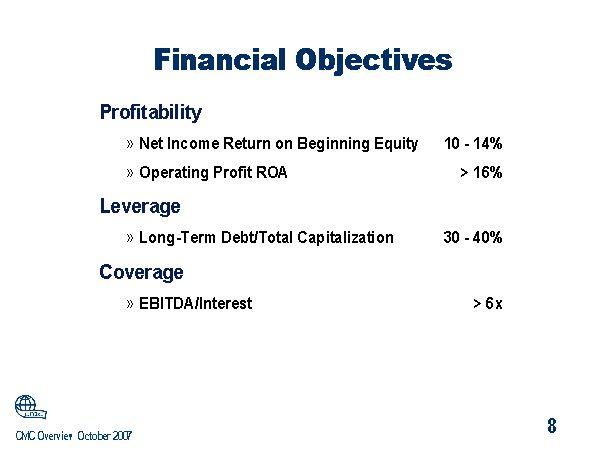
Creating a roadmap for your family’s financial future starts with setting objectives that are both clear and attainable. It’s essential to define what success looks like for your family, whether it’s buying a new home, funding education, or planning for retirement. Start by discussing with your family what your long-term aspirations are, and ensure everyone is on the same page. This collaborative approach not only strengthens family bonds but also aligns everyone towards common goals.
When establishing your objectives, consider the following steps:
- Prioritize Goals: Decide which goals are most important and require immediate attention.
- Be Specific: Clearly define what you want to achieve. For instance, instead of saying “save more money,” specify “save $10,000 for a vacation by next summer.”
- Set a Timeline: Establish a realistic timeframe for each goal to maintain focus and motivation.
- Break It Down: Divide larger goals into smaller, manageable tasks to make the process less daunting.
- Review Regularly: Schedule regular check-ins to assess progress and make necessary adjustments.
By setting well-defined financial objectives, you can navigate your family’s financial journey with clarity and purpose, turning aspirations into achievable milestones.
Creating a Strategic Savings and Investment Plan
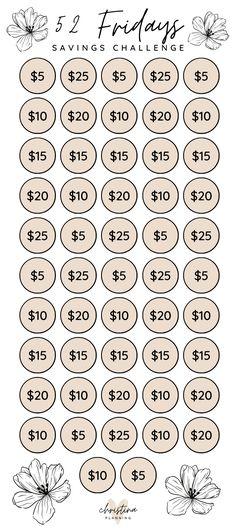
Developing a robust savings and investment plan is pivotal for securing your family’s financial future. Start by evaluating your current financial situation and defining clear, achievable goals. Prioritize your objectives: whether it’s saving for your children’s education, buying a new home, or ensuring a comfortable retirement. Once your priorities are set, allocate a portion of your income to savings and investments regularly. Use budgeting tools to track your expenses and identify areas where you can cut back to increase your savings potential.
Consider diversifying your investment portfolio to balance risk and return. Include a mix of stocks, bonds, and mutual funds that align with your risk tolerance and timeline. Explore tax-advantaged accounts like 401(k)s or IRAs to maximize your savings. Regularly review and adjust your plan as your family’s needs and financial circumstances evolve. Remember, consistency and discipline are key to achieving long-term financial success. Seek advice from a financial advisor if necessary to tailor a plan that best suits your family’s unique goals.
Implementing and Monitoring Your Financial Strategy
Once you’ve crafted a solid financial plan, the next step is ensuring it stays on course. Implementing your strategy requires setting up a robust framework to manage and track your progress. Start by breaking down your long-term goals into manageable, short-term objectives. This can involve setting up automatic transfers to savings accounts, investing in diversified portfolios, or scheduling regular reviews of your financial health.
Monitoring is equally crucial, acting as the compass guiding your financial journey. Regularly assess your financial statements and investment performance to ensure alignment with your goals. Consider employing tools like budgeting apps or financial dashboards to keep an eye on spending and savings trends. Key activities to include in your monitoring routine are:
- Reviewing monthly budget reports.
- Tracking progress towards specific savings targets.
- Adjusting investment allocations based on market conditions.
By diligently , you can navigate the complexities of financial planning with confidence, ensuring your family’s long-term goals remain within reach.