
Setting financial goals is a crucial step in securing a prosperous future for your family, yet many struggle with where to begin. The key to successful financial planning lies in establishing SMART goals—Specific, Measurable, Achievable, Relevant, and Time-bound. These criteria not only provide clarity and direction but also enhance motivation and accountability. In this article, we will guide you through the process of crafting SMART financial goals that align with your family’s long-term vision. With a strategic approach, you can transform your aspirations into actionable plans, ensuring financial stability and success for generations to come. Let’s embark on this journey to financial empowerment, where each step is designed to bring you closer to the future your family deserves.
Understanding the SMART Framework for Financial Planning
When it comes to financial planning for your family, utilizing the SMART framework can be a game-changer. This approach ensures that your financial goals are well-defined and actionable. SMART stands for Specific, Measurable, Achievable, Relevant, and Time-bound, each of which is crucial for crafting goals that are not only realistic but also motivating. By making your goals specific, you eliminate ambiguity and provide a clear target for your family to aim for. Instead of saying, “We want to save money,” specify, ”We will save $10,000 for our family vacation by the end of the year.”
Next, ensure your goals are measurable. This means setting criteria to track progress and determine when the goal has been met. In the example above, the $10,000 target makes it easy to measure your progress. Achievable goals are realistic and within reach, taking into account your family’s financial situation and commitments. Relevant goals align with your family’s values and long-term plans, ensuring that the effort you invest will be worthwhile. setting a time-bound deadline adds urgency and encourages consistent action. Consider these elements when planning your family’s financial future, and watch as the clarity and direction they provide propel you towards success.
Crafting Specific and Measurable Family Financial Objectives
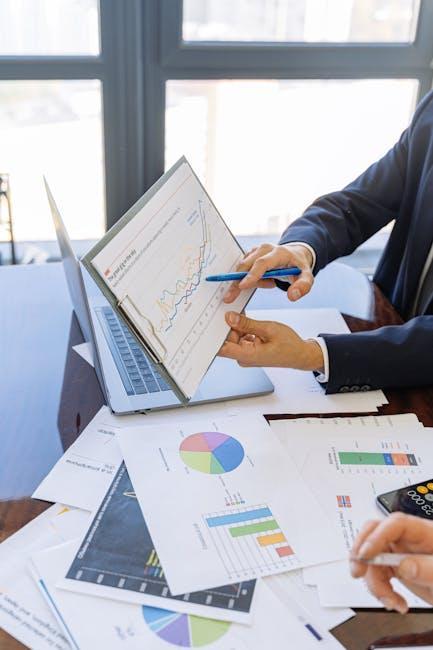
When envisioning the financial future of your family, it is crucial to transform vague dreams into clear, actionable steps. Crafting specific and measurable objectives can serve as your roadmap to achieving these goals. Begin by clearly defining what you want to accomplish. Instead of saying, ”We want to save more,” aim for something more precise, like, “We will save $10,000 for our child’s college fund by the end of the year.” Such specificity not only provides a clear target but also helps in tracking progress.
Next, ensure your goals are measurable. This involves setting benchmarks and timelines. Consider using the following strategies:
- Track Your Progress: Use tools like budgeting apps or spreadsheets to monitor your savings and expenditures.
- Set Milestones: Break down your primary objective into smaller, manageable goals. For example, aim to save $2,500 every three months to reach your annual savings target.
- Adjust as Needed: Life is unpredictable. Regularly review your goals and make adjustments to stay on track.
By focusing on specific and measurable financial objectives, you empower your family to achieve long-term success with clarity and purpose.
Achieving Attainable and Relevant Financial Milestones
Setting financial goals that are both attainable and relevant is essential for long-term family success. To ensure your financial milestones are realistic, start by evaluating your current financial situation. Analyze your income, expenses, and any existing savings or investments. This initial assessment will help you set goals that are challenging yet achievable. Remember to keep your family’s unique needs and aspirations at the forefront when defining these objectives. Consider goals such as saving for your children’s education, building an emergency fund, or planning for a family vacation.
When crafting these milestones, it’s crucial to keep them relevant to your family’s lifestyle and values. Ask yourself whether the goals align with your family’s future plans and aspirations. Consider the following to ensure your goals are relevant:
- Prioritize: Focus on what matters most to your family, whether it’s paying off debt or saving for retirement.
- Adaptability: Be prepared to adjust your goals as your family’s circumstances change.
- Involvement: Engage your family in the goal-setting process to ensure everyone is committed and invested.
By setting financial milestones that are both attainable and relevant, you create a clear roadmap that guides your family towards a prosperous future.

Setting Timely Goals for Sustained Family Prosperity
In the quest for long-term family success, establishing well-defined and timely financial goals is crucial. The SMART criteria—Specific, Measurable, Achievable, Relevant, and Time-bound—serve as a powerful framework for goal-setting. Here’s how you can leverage this approach:
- Specific: Clearly articulate your financial objectives. Instead of vague goals like “save money,” aim for precision, such as “save $20,000 for a family vacation in three years.”
- Measurable: Define metrics to track progress. Utilize budgeting tools or spreadsheets to monitor monthly savings and expenditures, ensuring you’re on track to reach your targets.
- Achievable: Set realistic goals that align with your family’s financial capacity. Evaluate your income and expenses to ensure that your objectives are within reach, avoiding unnecessary stress.
- Relevant: Align your goals with your family’s values and priorities. Consider whether the financial objectives contribute to your family’s overall well-being and long-term aspirations.
- Time-bound: Establish a clear timeline for achieving each goal. Whether it’s short-term, like a year, or long-term, like a decade, having deadlines keeps the family motivated and accountable.
By integrating these principles into your financial planning, you create a structured pathway to achieving prosperity that not only meets immediate needs but also supports enduring family success.