
Selecting the right education investment accounts for your children is a crucial decision that can significantly impact their future opportunities. With the rising costs of higher education, it’s more important than ever for parents to strategically plan and invest in their children’s academic journeys. In this guide, we will walk you through the key considerations and options available for managing education investments for multiple children. From understanding the differences between 529 plans and Coverdell ESAs to assessing the benefits of custodial accounts, we’ll equip you with the knowledge and confidence needed to make informed decisions. Whether you’re a seasoned investor or new to the world of financial planning, this article will serve as a comprehensive resource to help you secure a bright educational future for each of your children.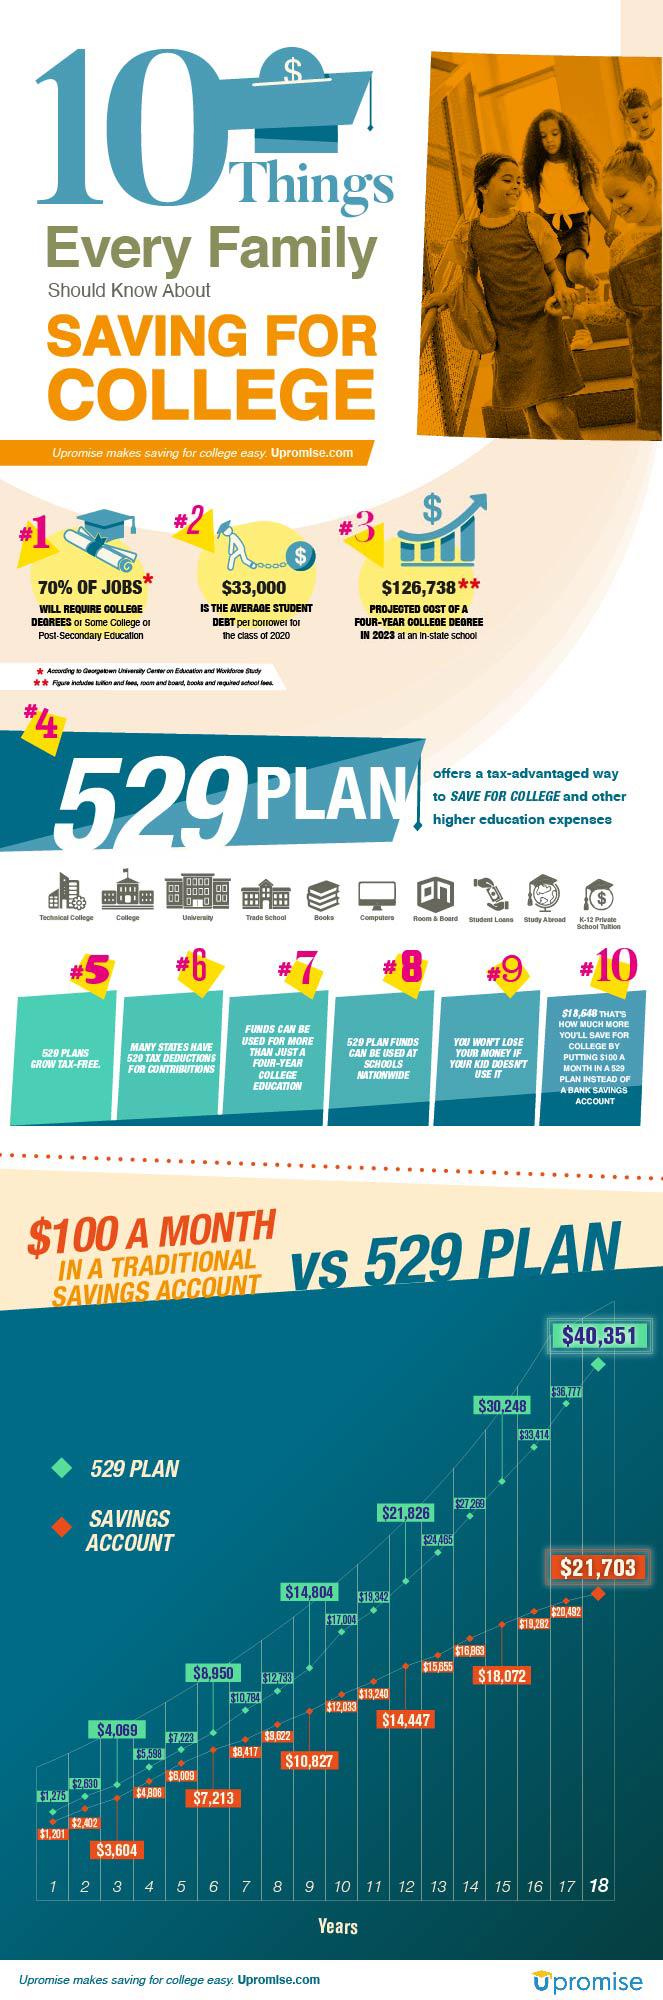
Understanding Key Features of Education Investment Accounts
When selecting an education investment account, it’s essential to understand the key features that can impact your financial strategy. One important aspect is the tax benefits. Many accounts offer tax-deferred growth or tax-free withdrawals for qualified education expenses, which can significantly enhance your savings over time. Consider the flexibility of contributions and withdrawals, as some accounts allow more frequent adjustments to accommodate the changing needs of multiple children.
Another crucial feature is the investment options available within the account. Look for accounts that offer a diverse range of investment vehicles, such as stocks, bonds, and mutual funds, to tailor your portfolio according to your risk tolerance and financial goals. Additionally, evaluate the fees and expenses associated with the account. Lower fees can lead to more substantial savings over the long term. Make sure to also assess the eligibility requirements and contribution limits, as these can vary widely and impact your ability to maximize the benefits of the account.
Strategies for Balancing Investments Across Multiple Children
When investing for multiple children, it’s crucial to implement strategies that ensure a balanced approach. Start by assessing each child’s unique educational needs and timelines. Some children may require funds sooner than others, depending on their age or educational plans. It’s wise to create a detailed timeline for each child, highlighting major educational milestones, which will guide your investment strategy.
Consider diversifying the types of accounts you use. Here are some effective strategies:
- 529 Plans: These accounts offer tax advantages and flexibility, making them a popular choice for education savings. Consider opening separate accounts for each child to tailor contributions according to their specific timelines.
- Custodial Accounts (UTMA/UGMA): These accounts can be used for educational expenses beyond tuition, providing additional flexibility. However, be mindful of potential tax implications and the impact on financial aid.
- Coverdell Education Savings Accounts: While these have lower contribution limits, they can be beneficial for covering K-12 expenses as well as college costs, offering a complementary option to 529 plans.
Regularly review and adjust contributions to each account based on changes in financial circumstances or educational goals. This proactive approach ensures that your investment strategy remains aligned with each child’s evolving needs.
Tax Advantages and Implications to Consider
When choosing the ideal education investment accounts for your children, understanding the tax benefits and potential implications is crucial. 529 plans are a popular choice due to their tax advantages. Contributions grow tax-deferred, and withdrawals for qualified education expenses are tax-free. This can lead to significant savings over time. Additionally, some states offer tax deductions or credits for contributions to their 529 plans, enhancing the potential for financial growth. However, it’s important to note that using funds for non-qualified expenses could result in taxes and penalties.
Coverdell Education Savings Accounts (ESAs) also provide tax-deferred growth, and withdrawals for qualified education expenses are tax-free. Unlike 529 plans, Coverdell ESAs allow for a broader range of investment options, though contributions are limited to $2,000 per year per beneficiary. Consider the following tax-related factors when selecting an account:
- State tax incentives: Check if your state offers tax deductions or credits for contributions to certain accounts.
- Income restrictions: Some accounts, like Coverdell ESAs, have income limits for contributors.
- Qualified expense flexibility: Evaluate which account offers the most flexibility for your family’s anticipated educational needs.
By understanding these tax aspects, you can make informed decisions that maximize your savings and support your children’s educational goals.
Expert Recommendations for Optimal Account Selection
When choosing education investment accounts for multiple children, consider a mix of options to maximize flexibility and growth potential. 529 Plans are a popular choice due to their tax advantages and high contribution limits, making them ideal for families with more than one child. However, it’s essential to assess each state’s plan for potential benefits and compare them with your own state’s offerings. Coverdell Education Savings Accounts (ESAs) are another viable option, particularly if you value a broader range of investment choices, though they come with lower contribution limits.
- Age-Based Portfolios: Opt for age-based portfolios within 529 Plans that automatically adjust the asset allocation as your child nears college age.
- Custodial Accounts: Consider Uniform Transfers to Minors Act (UTMA) or Uniform Gifts to Minors Act (UGMA) accounts for greater flexibility in how funds are used, although they lack the tax benefits of education-specific accounts.
- Assess Financial Aid Impact: Evaluate how each account type affects financial aid eligibility, as some may count more heavily against aid calculations.
For families with varying educational goals, diversifying across these accounts can help tailor your strategy to each child’s unique needs while maximizing your savings potential. Consulting with a financial advisor can also provide personalized insights to ensure that your investment strategy aligns with your long-term educational objectives.