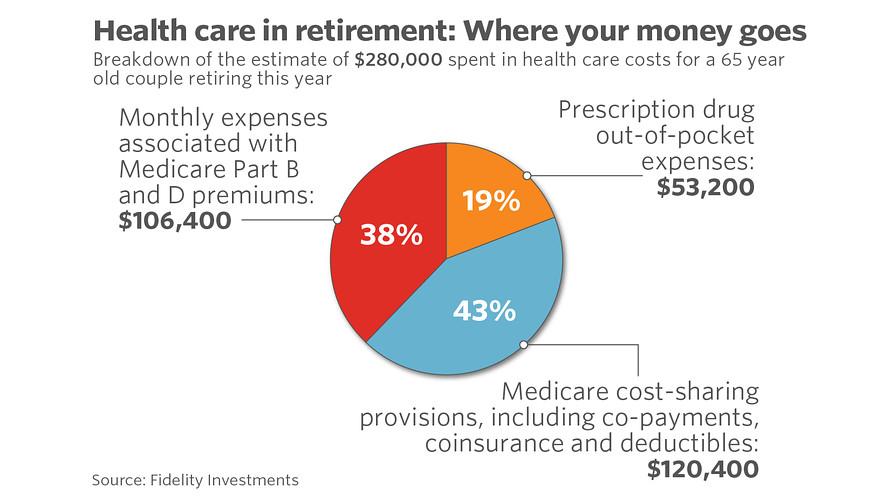
Monday, October 5, 2026
14.4 C
London

How to Plan for Health Care Costs in Retirement

Navigating the complexities of retirement planning can be daunting, but one critical aspect that often requires careful attention is preparing for health care costs. As we age, medical expenses can become a significant portion of our financial obligations, making it essential to develop a robust strategy to manage these costs effectively. In this guide, we will provide you with a clear, step-by-step approach to planning for health care expenses in retirement. By understanding the potential challenges and exploring available options, you can confidently secure your financial well-being and enjoy a worry-free retirement. Whether you are just beginning to think about retirement or are in the final stages of planning, this article will equip you with the knowledge and tools needed to make informed decisions about your health care future.
Understanding Future Health Care Needs

Understanding Future Health Care Needs

As we age, understanding the intricacies of potential health care needs becomes paramount. The landscape of health care is continuously evolving, influenced by factors such as advancements in medical technology, policy changes, and shifts in demographic trends. To prepare effectively, it’s essential to anticipate the types of care you may require. Consider the following potential needs:

  • Preventive Care: Regular check-ups, screenings, and vaccinations to maintain health and catch issues early.
  • Chronic Disease Management: Ongoing treatment for conditions like diabetes, heart disease, or arthritis, which become more prevalent with age.
  • Long-Term Care: Assistance with daily activities that may become necessary, whether through in-home care or a nursing facility.
  • Prescription Medications: An increase in medications for managing health conditions, which can significantly impact your budget.

By forecasting these needs, you can create a more robust financial strategy, ensuring that your retirement years are not only enjoyable but also secure.
Evaluating Insurance Options for Retirees

Evaluating Insurance Options for Retirees

When selecting an insurance plan for your retirement years, it’s crucial to consider the diverse needs that arise with age. Begin by evaluating Medicare, as it forms the cornerstone of health care for most retirees. Understand the differences between Medicare Part A, B, C, and D and determine which combination suits your health care requirements. Many retirees find that supplementing with a Medigap policy can help cover costs that traditional Medicare doesn’t, such as copayments, coinsurance, and deductibles.

In addition to Medicare, explore private insurance options that offer tailored benefits. Consider plans that provide coverage for long-term care, dental, and vision, which are often not included in Medicare. Key factors to assess include:

  • Premiums and Out-of-Pocket Costs: Ensure the plan fits your budget without compromising on necessary coverage.
  • Network of Providers: Verify that your preferred doctors and hospitals are within the plan’s network.
  • Coverage for Prescription Drugs: Evaluate the plan’s formulary to ensure your medications are covered.
  • Flexibility and Additional Benefits: Look for plans offering wellness programs, telehealth services, or overseas emergency care.

Choosing the right insurance plan requires balancing cost, coverage, and convenience to secure a worry-free retirement.

Creating a Comprehensive Health Care Budget

Building a well-rounded budget for health care in retirement involves several key steps. Begin by estimating your future medical expenses, which include both predictable and unforeseen costs. This can be done by examining your current health conditions and considering potential changes as you age. Use tools like retirement calculators or consult with a financial advisor to get a clearer picture. It’s also wise to account for inflation, as medical costs tend to rise over time.

Next, explore various health insurance options to cover potential gaps. Consider the following:

  • Medicare: Understand the different parts (A, B, C, D) and what each covers.
  • Supplemental Insurance: Look into Medigap policies that can help cover out-of-pocket expenses not included in Medicare.
  • Long-term Care Insurance: This can be essential if you anticipate needing assistance with daily activities or residing in a care facility.

By integrating these elements into your financial planning, you can create a robust budget that provides peace of mind and ensures you’re prepared for whatever the future holds.

Incorporating Health Savings Accounts into Your Plan

Health Savings Accounts (HSAs) offer a strategic advantage in managing health care expenses during retirement. These accounts allow for tax-free contributions, growth, and withdrawals when used for qualified medical expenses, making them a powerful tool in your financial arsenal. To maximize the benefits of an HSA, consider the following:

  • Start Early: The earlier you begin contributing to an HSA, the more time your funds have to grow. This can result in a substantial nest egg specifically earmarked for health care costs.
  • Contribute the Maximum: Each year, aim to contribute up to the maximum limit set by the IRS. This will enhance your tax advantages and increase your savings potential.
  • Invest Wisely: Many HSAs offer investment options similar to a 401(k). By investing a portion of your HSA funds, you can take advantage of compound growth over time.

By integrating an HSA into your retirement strategy, you ensure that a significant portion of your health care expenses can be managed without derailing your overall financial plans.


Hot this week

Best Ways to Plan for Your Familys Long Term Financial Success

To secure your family's financial future, start by setting clear goals, creating a diversified investment portfolio, and building an emergency fund. Regularly review your plans and adjust as needed to stay on track for long-term success.

How to Diversify Your Familys Investment Portfolio

Diversifying your family's investment portfolio involves balancing risk and reward. Consider a mix of stocks, bonds, real estate, and mutual funds. Regularly review and adjust to align with financial goals and market conditions.

Credit counseling services for debt management and reduction

Credit counseling services offer expert guidance for managing and reducing debt. By analyzing your financial situation, they help create a tailored plan to consolidate debts, lower interest rates, and improve financial literacy, leading to lasting financial stability.

How to Stay Focused on Long Term Financial Goals

Stay focused on long-term financial goals by setting clear objectives, creating a realistic budget, and regularly reviewing your progress. Automate savings and avoid distractions by staying informed and disciplined in your financial journey.

How to Plan for Unexpected Medical Expenses

To manage unexpected medical expenses, start by building an emergency fund. Regularly review your insurance coverage to ensure it meets your needs, and consider a Health Savings Account (HSA) for tax-advantaged savings.

Topics

Best Ways to Plan for Your Familys Long Term Financial Success

To secure your family's financial future, start by setting clear goals, creating a diversified investment portfolio, and building an emergency fund. Regularly review your plans and adjust as needed to stay on track for long-term success.

How to Diversify Your Familys Investment Portfolio

Diversifying your family's investment portfolio involves balancing risk and reward. Consider a mix of stocks, bonds, real estate, and mutual funds. Regularly review and adjust to align with financial goals and market conditions.

Credit counseling services for debt management and reduction

Credit counseling services offer expert guidance for managing and reducing debt. By analyzing your financial situation, they help create a tailored plan to consolidate debts, lower interest rates, and improve financial literacy, leading to lasting financial stability.

How to Stay Focused on Long Term Financial Goals

Stay focused on long-term financial goals by setting clear objectives, creating a realistic budget, and regularly reviewing your progress. Automate savings and avoid distractions by staying informed and disciplined in your financial journey.

How to Plan for Unexpected Medical Expenses

To manage unexpected medical expenses, start by building an emergency fund. Regularly review your insurance coverage to ensure it meets your needs, and consider a Health Savings Account (HSA) for tax-advantaged savings.

Simple Steps to Cut Down on Monthly Bills

To reduce monthly bills, start by tracking your expenses. Identify non-essential subscriptions to cancel, negotiate better rates for services, and implement energy-saving habits. These steps can significantly ease financial stress.

How to Choose the Right Education Savings Plan

Choosing the right education savings plan requires understanding your financial goals, the timeline for education expenses, and tax implications. Evaluate options like 529 plans or ESAs to find the best fit for your family's future.

Simple Ways to Save for a Family Vacation This Year

Start by setting a clear savings goal and timeline. Create a dedicated vacation fund, automate monthly deposits, and cut non-essential expenses. Use cashback apps and compare travel deals to maximize your savings efficiently.
spot_img

Related Articles

Popular Categories

spot_imgspot_img