In the battle against mounting debt, finding an effective strategy to regain financial freedom is crucial. One powerful approach that has gained popularity among financial experts and debtors alike is the Avalanche Method. This technique not only helps you pay off debt faster but also saves you money on interest in the long run. In this article, we will guide you through the steps of implementing the Avalanche Method, empowering you with the tools and confidence needed to tackle your debt head-on. By understanding and applying this method, you can create a clear, focused plan to eliminate your financial burdens and pave the way toward a more secure and prosperous future. Let’s dive into how you can harness the power of the Avalanche Method to transform your financial landscape.
Understanding the Avalanche Method and Its Benefits
The avalanche method is a strategic approach to debt repayment that prioritizes paying off debts with the highest interest rates first. By focusing on these high-interest debts, you can reduce the total amount of interest paid over time, enabling faster debt elimination. This method requires discipline and a clear understanding of your financial obligations, but the rewards are significant.
Benefits of the Avalanche Method include:
- Interest Savings: By tackling high-interest debts first, you save money that would otherwise be lost to interest payments.
- Faster Debt Repayment: Once high-interest debts are cleared, more of your payment goes toward the principal balance of remaining debts.
- Financial Clarity: With a structured plan, you gain a clearer picture of your financial progress and are less likely to incur additional debt.
Identifying and Prioritizing High-Interest Debts
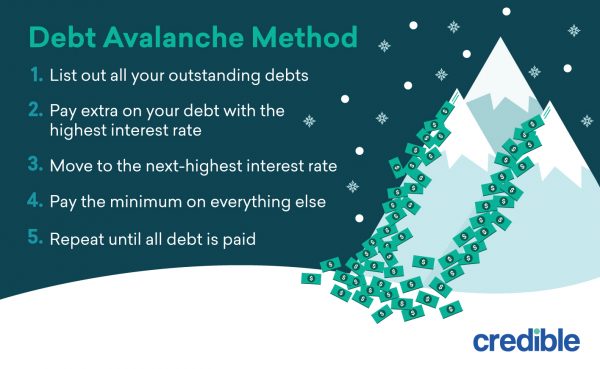
Before you can effectively employ the Avalanche Method, it’s crucial to identify which debts are costing you the most. Start by compiling a comprehensive list of all your outstanding debts, including credit cards, personal loans, and any other liabilities. For each, note down the interest rate and the outstanding balance. Once you have this information, sort your debts in order of interest rate, from highest to lowest. This prioritized list will be your roadmap, allowing you to tackle the most expensive debts first, thereby saving money on interest in the long run.
- Compile a list: Gather all details about your debts.
- Note interest rates: Identify which debts have the highest rates.
- Prioritize: Sort debts by interest rate to determine the payoff order.
By focusing on high-interest debts, you’re strategically targeting the financial burdens that are growing the fastest. This approach not only accelerates debt repayment but also instills a sense of accomplishment as you eliminate the most costly obligations first. Remember, it’s not just about paying off debt—it’s about doing so in the most efficient way possible.

Crafting a Strategic Repayment Plan
When embarking on a journey to become debt-free using the avalanche method, developing a strategic repayment plan is essential. This approach prioritizes debts with the highest interest rates, ensuring that you’re minimizing the total interest paid over time. Begin by listing all your debts, identifying the interest rate for each. Focus on these key steps to create an effective plan:
- Identify High-Interest Debts: Use your list to pinpoint which debts have the highest interest rates. These are your primary targets.
- Allocate Extra Payments: Direct any additional funds towards the debt with the highest interest rate, while maintaining minimum payments on others.
- Track Your Progress: Regularly monitor your repayments and adjust your plan as needed to ensure you’re on track to meet your goals.
With discipline and a clear strategy, the avalanche method can significantly reduce the time and money spent on debt repayment, accelerating your path to financial freedom.

Maximizing Savings and Staying Motivated
Embracing the avalanche method isn’t just about numbers; it’s a mindset shift that empowers you to tackle debt strategically. The essence of this method lies in paying off debts with the highest interest rates first, thereby minimizing the total interest paid over time. Here’s how to keep your savings on track while maintaining motivation:
- Track Your Progress: Use a simple spreadsheet or a budgeting app to monitor your debt payments. Seeing the high-interest balances decrease can be incredibly motivating and reinforces your commitment.
- Celebrate Milestones: Set small goals and celebrate when you reach them. Whether it’s a special meal or a day out, rewarding yourself for hitting milestones can keep the momentum going.
- Automate Payments: Set up automatic payments to ensure consistency and avoid late fees. This step helps maintain discipline and prevents the temptation to allocate funds elsewhere.
Remember, every dollar saved on interest is a dollar that can be redirected towards your financial goals. By staying organized and focused, the avalanche method can transform your approach to debt repayment and lead you to financial freedom faster.