
In today’s rapidly evolving educational landscape, the cost of college tuition continues to climb, posing significant financial challenges for students and their families. However, proactive planning can play a pivotal role in alleviating this burden. One effective strategy that is gaining traction is the use of prepayment options to lock in current tuition rates and reduce future college expenses. This approach not only offers peace of mind but also provides a strategic financial advantage by circumventing the unpredictability of tuition hikes. In this article, we will explore various prepayment options available to families, detailing how they work, their benefits, and the steps you can take to implement them successfully. By taking control of college costs now, you can ensure a more financially secure future for your educational journey.
Exploring Prepayment Plans to Lock in Tuition Rates
One effective way to combat the ever-increasing costs of college education is through prepayment plans. These plans allow families to pay for future tuition at current rates, effectively locking in today’s prices and protecting against inflation. When considering this option, it’s important to explore various plans offered by different institutions and states, as each may come with unique terms and benefits. Some may allow you to prepay for specific credit hours, while others might offer a comprehensive package covering all tuition-related expenses.
- Research the eligibility requirements for each plan to ensure it aligns with your financial goals and your student’s educational path.
- Understand the refund policies, as circumstances might change, and it’s crucial to know how your investment is protected.
- Compare the flexibility of different plans, especially if your student might consider transferring schools or changing their major.
By choosing the right prepayment plan, families can not only manage future college expenses more effectively but also gain peace of mind knowing they’ve safeguarded their investment in education against unpredictable tuition hikes.
Maximizing Savings with Early Payment Discounts
One savvy strategy to trim future college expenses is by leveraging early payment discounts offered by educational institutions. These discounts provide a percentage reduction in tuition fees when payments are made before a specified deadline. By taking advantage of these offers, families can effectively decrease the overall cost of college education. Here’s how to make the most of these opportunities:
- Research and Compare: Different colleges may offer varying discount rates for early payments. Investigate the policies of each institution to identify the most advantageous options.
- Plan Finances: Assess your financial situation to determine if early payments are feasible. This may involve reallocating funds or budgeting to ensure that you can meet the deadline.
- Understand the Terms: Carefully read the terms and conditions associated with early payment discounts. Be aware of any potential penalties for late payments or withdrawals.
By implementing these strategies, you can not only reduce the immediate financial burden but also secure long-term savings, allowing more room in your budget for other educational expenses.
Understanding the Benefits of Tuition Prepayment Options
Navigating the landscape of college expenses can be daunting, but tuition prepayment plans offer a strategic way to manage future costs. By locking in current tuition rates, these plans protect families from the annual increases in college fees. This approach is particularly beneficial for families with younger children, as it allows them to capitalize on today’s rates for tomorrow’s education. The prepayment option essentially acts as a hedge against inflation, ensuring that future financial burdens are minimized.
When considering these plans, it’s important to weigh the benefits carefully. Some key advantages include:
- Predictability: Prepaying tuition provides a fixed cost structure, making financial planning more predictable.
- Potential Tax Benefits: In certain cases, prepayment plans may offer tax advantages, depending on the state or institution.
- Peace of Mind: Knowing that a significant portion of college expenses is already covered can reduce stress and allow families to focus on other financial goals.
By understanding and utilizing tuition prepayment options, families can take proactive steps towards reducing the financial burden of higher education.
Strategic Financial Planning for College Cost Reduction
When it comes to managing the financial burden of higher education, prepayment options can be a game-changer. By planning strategically, families can lock in current tuition rates, potentially saving thousands of dollars. Here are some key considerations to keep in mind:
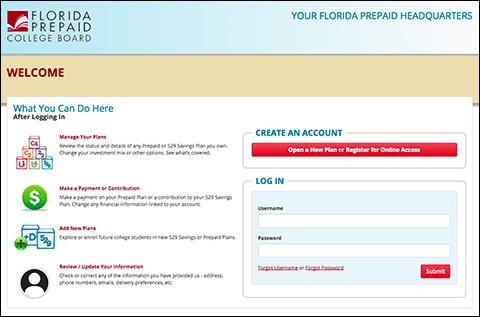
- Prepaid Tuition Plans: These plans allow you to pay for future tuition at today’s rates, which can be a hedge against tuition inflation. Investigate if your state offers a prepaid tuition plan and understand the terms and conditions, including any residency requirements.
- 529 Plans: While traditionally used for savings, some 529 plans offer prepaid options. Research if your state provides this benefit and consider the tax advantages that come with contributing to a 529 plan.
- Institution-Specific Prepayment Programs: Some colleges and universities offer their own prepaid tuition programs. Contact the financial aid office of your preferred institutions to explore available options and their specific benefits.
By incorporating these prepayment strategies into your financial planning, you can take a proactive approach to reducing future college costs. Remember, the key is to start early and explore all available options to find the best fit for your financial situation.