
Creating a robust family savings plan is a cornerstone of financial stability and peace of mind. In a world where economic uncertainties are increasingly common, having a well-structured savings strategy is not just advisable but essential. This guide is designed to equip you with the knowledge and tools necessary to establish a family savings plan that is both practical and enduring. By understanding key financial principles and adopting disciplined habits, you can build a secure financial future for your family. From setting realistic goals to monitoring progress and making adjustments, this article will walk you through each step of the process, ensuring that your savings plan is not only effective but also sustainable.
Establish Clear Financial Goals for Your Family
Setting financial objectives is the cornerstone of a successful family savings plan. Begin by engaging in an open dialogue with all family members to determine both short-term and long-term financial aspirations. Consider discussing the following questions:
- What are our immediate financial needs?
- What larger purchases or investments do we envision in the next five years?
- What are our retirement or education savings goals?
Once these goals are identified, prioritize them based on urgency and importance. This will provide a roadmap to align your savings strategy with your family’s unique aspirations. Communicate these priorities clearly and ensure everyone is on the same page to foster a sense of shared responsibility and motivation.
Develop a Realistic Budget and Tracking System
Crafting a budget that works for your family requires a clear understanding of your income, expenses, and savings goals. Begin by listing all sources of income and categorizing your expenses into essentials and non-essentials. Essentials include housing, utilities, groceries, and transportation, while non-essentials might cover dining out, entertainment, and subscriptions. Prioritize your expenses, ensuring that your essential needs are met before allocating funds to discretionary spending. By doing so, you create a realistic view of your financial landscape, enabling better control over your money.
Implement a tracking system to monitor your financial progress. This can be as simple as a spreadsheet or as sophisticated as a budgeting app that links to your bank accounts. Key elements of an effective tracking system include:
- Real-time updates to track spending immediately.
- Categorization tools to help you see where your money is going.
- Alerts for when you’re approaching your budget limits.
Regularly reviewing your budget and making necessary adjustments ensures it remains relevant and effective. Set aside time each month to evaluate your spending habits, and be open to modifying your budget as your family’s needs change. This disciplined approach will keep you on track towards achieving your savings goals.
Implement Consistent Saving Strategies and Techniques
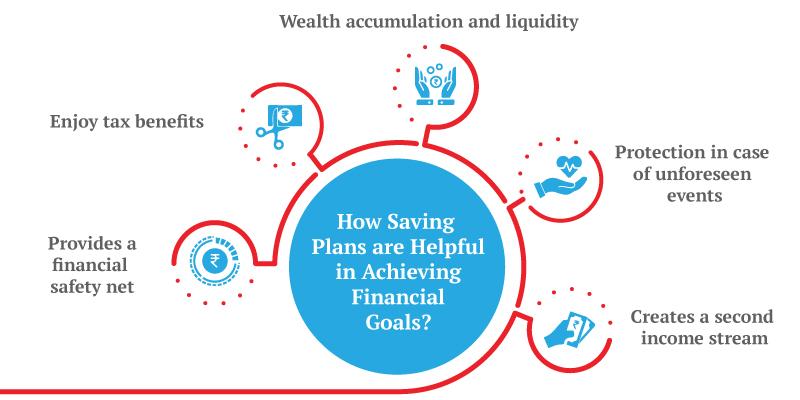
To ensure that your family savings plan is not only established but also adhered to, it’s crucial to implement consistent saving strategies. Begin by setting clear and achievable savings goals that align with your family’s financial objectives. Break these goals down into smaller, manageable milestones to maintain motivation and track progress effectively. This approach not only provides clarity but also allows for regular celebration of achievements, reinforcing positive saving habits.
- Automate Savings: Use automatic transfers to move a fixed amount from your checking to savings account regularly, ensuring savings are prioritized.
- Budgeting Tools: Utilize budgeting apps or spreadsheets to monitor spending and identify areas where expenses can be trimmed to increase savings potential.
- Review Regularly: Schedule monthly or quarterly family meetings to review financial progress, adjust strategies, and address any challenges in sticking to the plan.
- Emergency Fund: Establish a separate emergency fund to avoid dipping into your savings for unexpected expenses, keeping your savings goals intact.
By integrating these techniques into your routine, you create a disciplined and structured environment that fosters a culture of saving within the family. This ensures that your savings plan is not just a fleeting resolution but a lasting commitment to financial well-being.
Engage and Educate Family Members on Financial Responsibility
Building a successful family savings plan involves the collaboration and commitment of every family member. Start by scheduling a family meeting to discuss financial goals and the importance of saving. Encourage open communication where everyone can voice their ideas and concerns. Together, establish a shared vision of what the savings are for—be it a family vacation, an emergency fund, or a long-term investment in education. This not only aligns your goals but also motivates each member to contribute actively.
Here are some steps to foster engagement and accountability:
- Set realistic goals: Break down larger objectives into manageable milestones to keep everyone motivated.
- Assign roles and responsibilities: Designate tasks like monitoring expenses or researching savings options to specific members.
- Create a visible savings tracker: Use a chart or digital app to track progress, making it accessible for the whole family to see.
- Celebrate achievements: Acknowledge and reward the family’s efforts when milestones are met, reinforcing positive saving habits.