
Embarking on the journey of saving for college can often feel like navigating a labyrinth of numbers, options, and looming deadlines. However, with the right approach and a clear plan, it can be a manageable and even empowering process. This guide is designed to demystify the steps you need to take to start saving for college without stress. By breaking down the complexities into simple, actionable steps, we aim to equip you with the knowledge and confidence needed to secure a bright academic future for your child or yourself. Whether you’re just beginning to consider the costs or are looking for smarter ways to enhance your savings strategy, this article will provide you with the essential tools and insights to turn what can be an overwhelming task into a straightforward and achievable goal. Let’s dive in and discover how you can start saving for college today, with peace of mind and a clear path forward.
Understanding College Savings Plans and Their Benefits
When it comes to planning for your child’s future education, understanding the various savings options available is crucial. College savings plans offer numerous benefits that can ease the financial burden when the time comes. Here are some key points to consider:
- Tax Advantages: Many college savings plans, such as 529 plans, offer tax-free growth and tax-free withdrawals when used for qualified education expenses. This can result in significant savings over time.
- Flexibility: These plans often provide flexibility in terms of contributions and withdrawals. You can adjust your contributions based on your financial situation, making it easier to manage alongside other financial commitments.
- Investment Options: College savings plans typically offer a range of investment choices, allowing you to tailor your portfolio according to your risk tolerance and financial goals.
- State Benefits: Some states offer additional incentives, such as tax deductions or matching grants, for residents who invest in their state’s plan.
Understanding these benefits can empower you to make informed decisions about saving for college. With the right plan, you can significantly reduce the financial stress associated with higher education expenses, ensuring a brighter future for your child.
Crafting a Realistic Savings Goal Tailored to Your Familys Needs
Setting a savings goal that aligns with your family’s specific needs requires a careful evaluation of your financial landscape. Begin by assessing your current financial situation: monthly income, existing expenses, and any outstanding debts. With this foundation, you can determine how much you can realistically allocate towards your child’s college fund each month. Remember, it’s important to balance this new savings commitment with other essential financial obligations.
- Identify potential cost-saving areas in your budget to free up more funds for savings.
- Consider your child’s educational aspirations and the potential cost of different types of institutions.
- Factor in inflation and rising tuition costs when setting your target amount.
With a clear understanding of your financial picture, set a specific and measurable savings target. Break this goal into manageable milestones, such as quarterly or annual savings targets. This approach not only makes the goal less daunting but also allows for adjustments along the way. By aligning your savings plan with your family’s unique needs and circumstances, you’ll create a pathway that feels achievable and empowering.
Exploring Scholarships and Grants to Supplement Your Savings
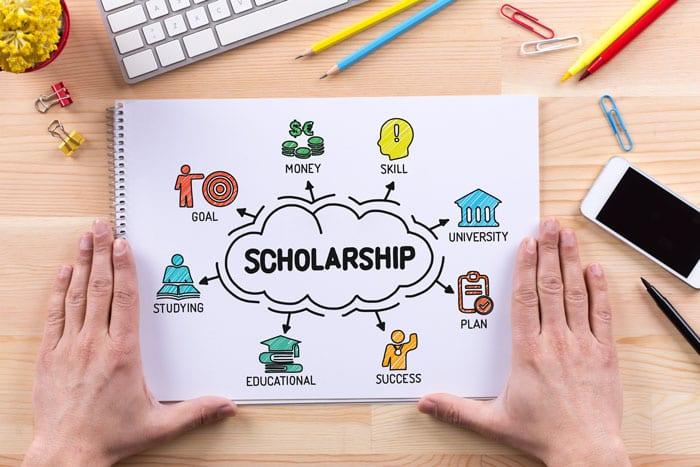
When planning for college expenses, it’s essential to explore every avenue available to ease the financial burden. Scholarships and grants are excellent resources that can significantly bolster your college fund. These opportunities often come with the advantage of not needing to be repaid, unlike student loans. To make the most of these options, start by researching opportunities early. Many scholarships and grants are available through a variety of sources, including:
- Academic Institutions: Colleges often offer merit-based scholarships or need-based grants to attract talented students.
- Private Organizations: Numerous foundations and companies provide scholarships based on criteria such as field of study, community service, or demographic factors.
- Government Programs: Federal and state governments offer grants like the Pell Grant, which can significantly reduce tuition costs for eligible students.
To maximize your chances, tailor each application to highlight your unique strengths and align with the specific criteria of the scholarship or grant. Also, pay close attention to deadlines and required documentation. By systematically exploring and applying for these opportunities, you can effectively supplement your savings and reduce the financial stress associated with college expenses.
Utilizing Automatic Contributions to Simplify Your Savings Strategy
Harnessing the power of automatic contributions can revolutionize your savings strategy, especially when planning for college expenses. By setting up a systematic, hands-off approach, you not only ensure regular savings but also alleviate the stress of manual transfers. Most financial institutions offer this service, allowing you to define a specific amount to be deducted from your paycheck or primary account at regular intervals. This ensures that your savings grow steadily over time without the temptation of spending the funds elsewhere.
- Consistency: Regular deposits help build a substantial fund over time.
- Discipline: Removes the need for constant decision-making about when and how much to save.
- Peace of Mind: Knowing that your savings are growing without active intervention.
Embrace the simplicity and efficiency of automatic contributions to take the guesswork out of saving for college. By setting up this system, you’re making a smart financial decision that aligns with a long-term goal, all while minimizing the mental load associated with financial planning.