Thursday, November 19, 2026
6.7 C
London

Best Ways to Save for a Down Payment on a House

Purchasing a home is a monumental milestone, a dream that many aspire to achieve. Yet, the journey to homeownership often begins with a formidable challenge: saving for a down payment. Navigating this financial commitment requires strategic planning and disciplined saving habits. In this guide, we will explore the best methods to effectively save for a down payment, empowering you with the knowledge and tools necessary to turn your dream into reality. Whether you’re a first-time buyer or looking to upgrade, our comprehensive strategies will provide a clear path to building your savings, ensuring you are well-prepared to take the next step towards securing your future home. Let’s embark on this journey with confidence and clarity, transforming the daunting task of saving into a manageable and achievable goal.
Understanding Your Savings Goals and Timeline

Understanding Your Savings Goals and Timeline

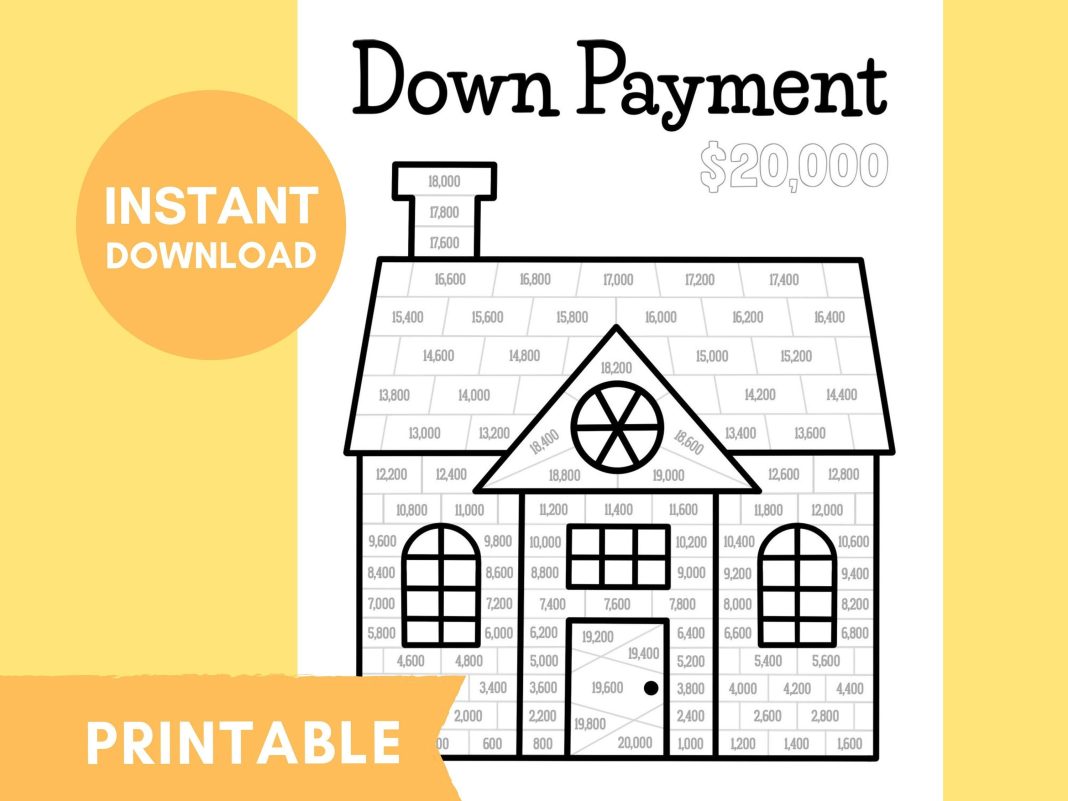
Before embarking on your journey to homeownership, it’s crucial to have a clear understanding of your savings objectives and the timeline you’re working with. Identifying your savings goal involves more than just calculating the down payment; you must also consider closing costs, moving expenses, and a potential buffer for unexpected costs. Begin by determining the total amount you’ll need to save, then break it down into manageable monthly savings targets. This approach will help you stay on track and reduce the overwhelming feeling that often accompanies such a significant financial commitment.

Creating a timeline is equally important. Start by setting a realistic target date for purchasing your home. Consider factors such as your current financial situation, income stability, and any upcoming life changes that might impact your ability to save. Once you’ve established a timeline, it’s time to create a plan that aligns with it. Here are a few strategies to help you reach your goal:

  • Automate your savings: Set up automatic transfers to a dedicated savings account to ensure consistency.
  • Reduce unnecessary expenses: Identify areas where you can cut back, such as dining out or subscription services.
  • Increase your income: Explore side hustles or ask for a raise to boost your savings potential.
  • Leverage windfalls: Allocate bonuses, tax refunds, or gifts directly to your down payment fund.

By understanding and organizing your savings goals and timeline, you’ll be better equipped to make informed decisions and maintain motivation throughout the saving process.

Maximizing Income and Reducing Expenses

To effectively reach your savings goal, it’s crucial to focus on both increasing your income and cutting unnecessary costs. Here are some strategies to help you optimize your finances:

  • Boost Your Earnings: Consider taking on a side hustle or freelance work in your spare time. Platforms like Upwork or Fiverr offer opportunities to leverage your skills for extra cash. Alternatively, ask for a raise or explore job opportunities that offer better compensation.
  • Slash Your Expenses: Start by auditing your monthly expenses and identifying areas where you can cut back. Cancel unused subscriptions, opt for home-cooked meals instead of dining out, and negotiate for lower rates on bills such as insurance and utilities.
  • Automate Savings: Set up automatic transfers to a dedicated savings account specifically for your down payment. This ensures that a portion of your income is consistently saved without the temptation to spend it elsewhere.

By diligently following these steps, you’ll create a robust financial plan that not only maximizes your income but also strategically minimizes your expenses, paving the way to your new home.

Exploring Investment Options for Growth

When planning for a down payment on a house, diversifying your investment strategies can help accelerate your savings growth. Consider these smart investment options to enhance your financial portfolio:

  • High-Yield Savings Accounts: These accounts offer higher interest rates than traditional savings accounts, allowing your money to grow more quickly while remaining easily accessible.
  • Certificates of Deposit (CDs): With fixed interest rates and terms, CDs provide a secure way to grow your funds. They often offer higher returns than regular savings accounts, especially if you’re willing to lock in your money for a longer period.
  • Stocks and ETFs: Investing in stocks or Exchange-Traded Funds can potentially yield higher returns. Opt for a diversified portfolio to spread risk and consider low-cost index funds for long-term growth.
  • Robo-Advisors: If you’re new to investing or prefer a hands-off approach, robo-advisors can automatically manage your portfolio with algorithms tailored to your financial goals and risk tolerance.

By leveraging these options, you can strategically build a robust fund for your future home, combining security with the potential for higher returns.

Leveraging Financial Assistance Programs

When you’re on the path to purchasing a home, understanding and utilizing various financial assistance programs can significantly accelerate your journey. These programs, often provided by government agencies, non-profits, or financial institutions, are designed to support first-time homebuyers or those in need of extra financial backing. They can come in the form of grants, low-interest loans, or down payment assistance programs. It’s crucial to research the options available in your area and determine your eligibility, as these programs can help reduce the initial financial burden, allowing you to focus on other aspects of home ownership.

  • First-Time Homebuyer Grants: These are often non-repayable funds provided to assist with down payments and closing costs. Explore local and federal options to see what you qualify for.
  • Low-Interest Loans: Many financial institutions offer loans with reduced interest rates for first-time buyers. These can make home ownership more affordable over the long term.
  • Down Payment Assistance Programs: These programs can offer a percentage of the home’s purchase price or a fixed amount to help cover your down payment. Often tailored to specific income brackets or geographic locations, these can be a game-changer for buyers.

Taking advantage of these financial assistance options not only helps you gather the necessary funds more quickly but also demonstrates your commitment and preparedness to lenders, potentially improving your loan terms. Don’t overlook these resources as you strategize your savings plan for a down payment.


Hot this week

Family budgeting strategies for large families

Mastering family budgeting for large households involves prioritizing expenses, tracking spending, and leveraging bulk purchases. Set clear financial goals, involve all family members, and use apps to streamline and monitor the budget effectively.

How to create a family financial roadmap with clear milestones

Start by assessing your current financial situation and setting specific, achievable goals. Break these into short-term, medium-term, and long-term milestones. Regularly review and adjust your plan to stay on track and ensure family financial stability.

How to balance short term and long term financial goals as a family

Balancing short-term and long-term financial goals as a family requires clear communication, prioritizing needs, and setting realistic timelines. Start with a budget that allocates funds for immediate expenses while saving for future aspirations.

Pros and Cons of Debt Management Programs vs Debt Settlement

Debt management programs offer structured repayment plans to help manage debt, promoting financial discipline and often reducing interest rates. In contrast, debt settlement negotiates debt reductions but may harm credit scores and incur fees.

The Benefits of Debt Management Plans for Families

Debt Management Plans (DMPs) offer families a structured path to financial stability by consolidating debts into manageable payments. They reduce interest rates and monthly burdens, empowering families to regain control over their financial future.

Topics

Family budgeting strategies for large families

Mastering family budgeting for large households involves prioritizing expenses, tracking spending, and leveraging bulk purchases. Set clear financial goals, involve all family members, and use apps to streamline and monitor the budget effectively.

How to create a family financial roadmap with clear milestones

Start by assessing your current financial situation and setting specific, achievable goals. Break these into short-term, medium-term, and long-term milestones. Regularly review and adjust your plan to stay on track and ensure family financial stability.

How to balance short term and long term financial goals as a family

Balancing short-term and long-term financial goals as a family requires clear communication, prioritizing needs, and setting realistic timelines. Start with a budget that allocates funds for immediate expenses while saving for future aspirations.

Pros and Cons of Debt Management Programs vs Debt Settlement

Debt management programs offer structured repayment plans to help manage debt, promoting financial discipline and often reducing interest rates. In contrast, debt settlement negotiates debt reductions but may harm credit scores and incur fees.

The Benefits of Debt Management Plans for Families

Debt Management Plans (DMPs) offer families a structured path to financial stability by consolidating debts into manageable payments. They reduce interest rates and monthly burdens, empowering families to regain control over their financial future.

How to Plan for Rising Costs During Retirement

To tackle rising costs in retirement, start by creating a detailed budget that accounts for inflation. Diversify your investment portfolio to hedge against market volatility, and consider healthcare savings plans to cover medical expenses.

Top Tips for Saving Money on Groceries Every Month

Cut costs with a meal plan: Plan weekly meals to avoid impulse buys. Buy in bulk for non-perishables, and choose generic brands. Use loyalty programs and coupons for extra savings. Shop with a list to stay focused and on budget.

How to Set Financial Goals That Work for Your Family

Setting financial goals for your family begins with open communication. Identify priorities, set realistic timelines, and track progress regularly. By aligning goals with family values, you create a plan that’s both motivating and achievable.
spot_img

Related Articles

Popular Categories

spot_imgspot_img