
Achieving your family’s financial milestones is not just a dream—it’s an attainable goal that requires strategic planning and disciplined execution. In a world where economic uncertainties often challenge financial stability, having a clear roadmap can make all the difference in securing your family’s future. This guide will empower you with the knowledge and tools necessary to navigate the complexities of personal finance, enabling you to set realistic goals and implement effective strategies. From budgeting basics to investment insights, you’ll learn how to align your financial decisions with your family’s unique aspirations. Let’s embark on this journey together, transforming your financial goals into a reality that supports your family’s well-being and prosperity.
Setting Clear and Attainable Financial Goals
To transform your family’s financial aspirations into reality, it is crucial to establish objectives that are both clear and attainable. Begin by identifying what truly matters to your family—whether it’s saving for your children’s education, planning a dream vacation, or securing a comfortable retirement. Clarity in your goals ensures that everyone is on the same page and can work collaboratively towards achieving them.
- Be Specific: Instead of a vague goal like “save money,” aim for something tangible, such as “save $10,000 for a family vacation by next year.”
- Set Measurable Targets: Break down your goals into smaller, measurable steps to track your progress effectively.
- Ensure Achievability: While it’s important to aim high, make sure your goals are realistic based on your current financial situation.
- Time-Bound Objectives: Assign a timeline to each goal, creating a sense of urgency and helping maintain focus.
By following these steps, your family will have a roadmap to follow, making financial success not just a possibility but a planned outcome.
Crafting a Strategic Family Budget
Developing a family budget is akin to crafting a masterpiece, where each financial decision contributes to the larger picture of achieving your family’s aspirations. Identify your financial goals by discussing and prioritizing what truly matters, be it saving for a dream vacation, funding your children’s education, or building an emergency fund. Start by gathering all sources of income and cataloging them. This provides a clear understanding of your financial landscape and helps in allocating funds effectively.
Next, categorize your expenses into essentials and non-essentials. Essentials include mortgage or rent, utilities, groceries, and insurance. Non-essentials might encompass dining out, entertainment, and subscriptions. Here’s a strategic approach to streamline your budget:
- Track your spending meticulously to identify patterns and areas for potential savings.
- Set a monthly limit for each category and stick to it.
- Reevaluate your budget quarterly to accommodate any changes in income or expenses.
- Utilize budgeting tools or apps to automate and simplify the process.
By treating your budget as a dynamic and adaptable tool, you empower your family to not only meet current needs but also lay the foundation for future financial milestones.
Building an Emergency Fund for Stability
Establishing a robust emergency fund is crucial for ensuring your family’s financial security. This fund acts as a financial buffer, providing peace of mind and stability during unexpected events such as medical emergencies, car repairs, or sudden job loss. To effectively build this fund, start by setting a clear target amount—typically, this should cover three to six months of living expenses. This will vary based on your family’s unique needs and lifestyle.
- Automate Your Savings: Set up automatic transfers from your checking account to your savings account each month. This ensures consistent contributions without the temptation to spend the money elsewhere.
- Cut Unnecessary Expenses: Review your monthly expenditures and identify areas where you can cut back. Redirect these savings to your emergency fund.
- Boost Your Income: Consider side gigs or freelance work to generate additional income dedicated solely to your emergency fund.
- Utilize Windfalls Wisely: Use bonuses, tax refunds, or monetary gifts to make substantial contributions to your fund, accelerating your progress.
By taking these proactive steps, you can create a financial safety net that not only supports your family during unforeseen circumstances but also reinforces a foundation for achieving broader financial milestones.
Investing in Your Familys Future
Mapping out a strategy for achieving financial milestones is essential for ensuring a secure and prosperous future for your family. Begin by setting clear and realistic goals that align with your family’s values and aspirations. These could include saving for a child’s education, purchasing a family home, or planning for a comfortable retirement. Prioritize these goals by considering their timeframes and importance. Once your priorities are set, develop a budget that allocates resources towards these goals, ensuring that you are consistently making progress.
To enhance your family’s financial stability, consider the following steps:
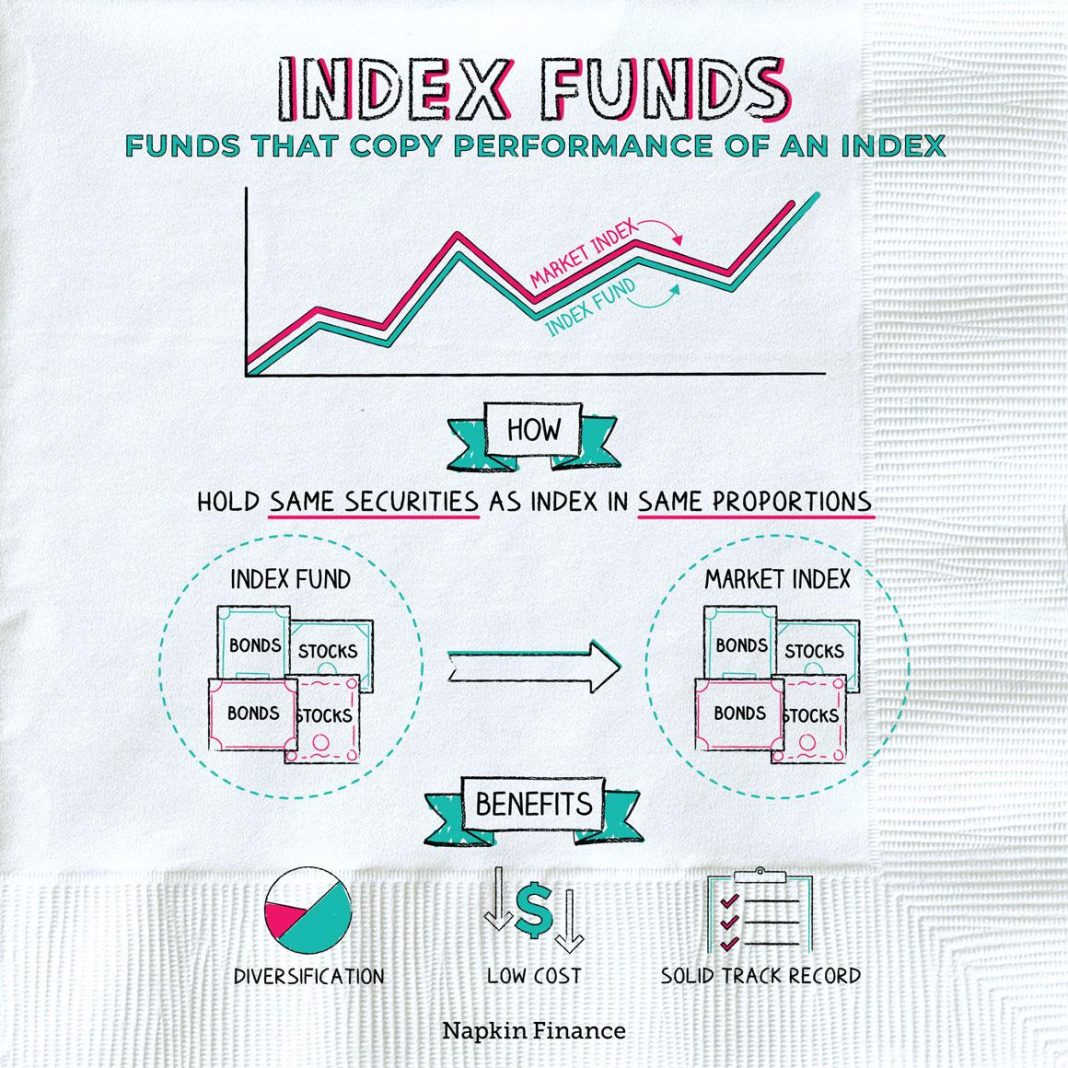
- Diversify Investments: Explore a mix of stocks, bonds, and real estate to spread risk and maximize potential returns.
- Emergency Fund: Build a safety net to cover unexpected expenses, ideally covering 3-6 months of living costs.
- Education and Skill Development: Invest in learning opportunities that increase earning potential and job security for family members.
- Insurance Coverage: Ensure you have adequate health, life, and property insurance to protect against unforeseen events.
By taking these proactive steps, you can confidently steer your family towards achieving their financial dreams, laying a strong foundation for future generations.