
Navigating the financial demands of both college tuition and retirement savings can feel like walking a tightrope, but with the right strategy, you can secure a bright future without sacrificing your financial well-being. As the cost of higher education continues to rise, many families face the daunting challenge of funding their children’s college education while also preparing for their own retirement. The good news is that you don’t have to choose one over the other. By implementing smart saving techniques and taking advantage of available resources, you can achieve a balance that ensures both educational and retirement goals are met. In this guide, we will explore effective methods to save for college while maintaining a robust retirement plan, empowering you to confidently invest in your family’s future.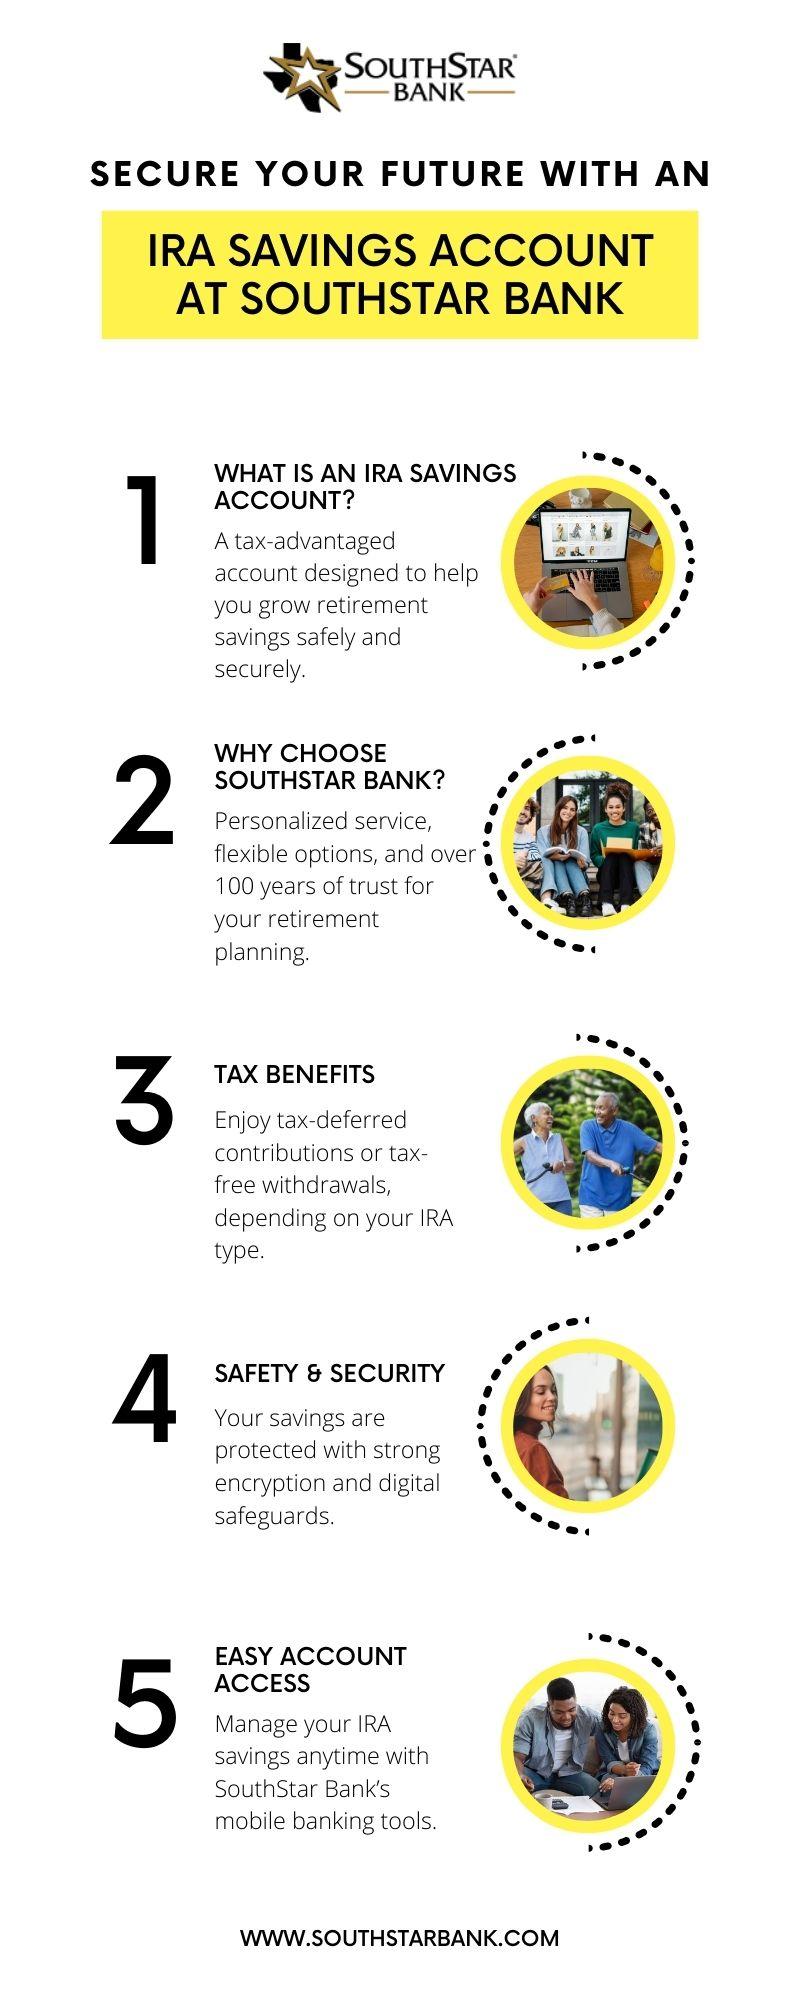
Maximize Tax-Advantaged Accounts for Dual Benefits
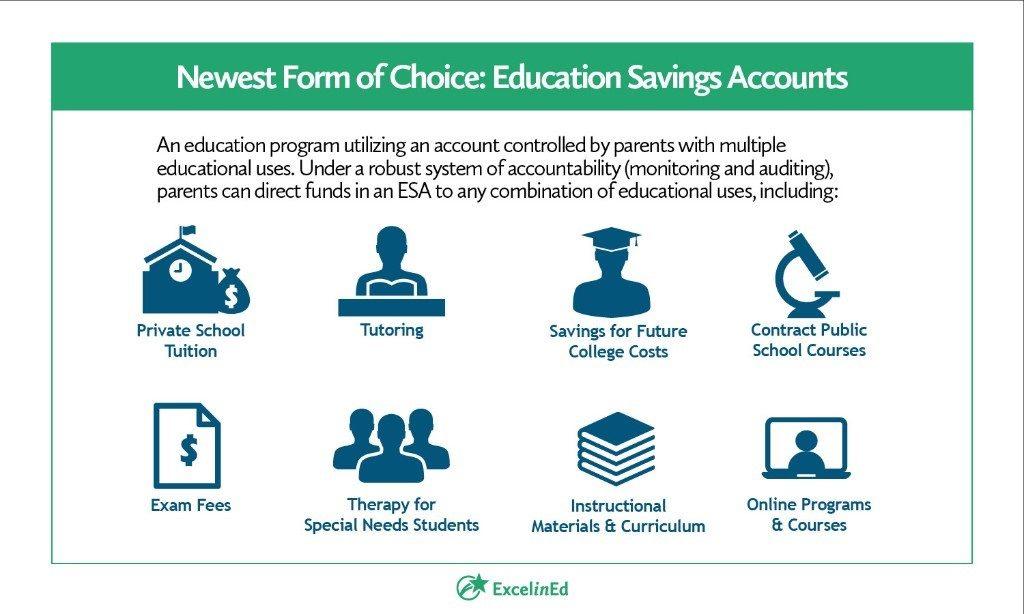
One of the most strategic moves in your financial planning arsenal is leveraging tax-advantaged accounts to achieve both educational and retirement goals. 529 Plans and Roth IRAs are exceptional tools in this regard. A 529 Plan offers tax-free growth and withdrawals for qualified education expenses, ensuring your college savings are maximized without the tax burden. Meanwhile, a Roth IRA provides tax-free growth and withdrawals in retirement, but also allows for penalty-free withdrawals on contributions for educational expenses, making it a flexible dual-purpose account.
Consider the following strategies to optimize these accounts:
- Contribute to a 529 Plan: Utilize state tax deductions or credits where available, and start early to maximize compound growth.
- Use a Roth IRA Wisely: While primarily a retirement account, its contribution withdrawal flexibility can act as a financial cushion for education costs.
- Balance Contributions: Ensure you’re not overfunding one account at the expense of the other. Regularly assess your financial goals and adjust contributions accordingly.
By strategically utilizing these accounts, you can effectively work towards securing both your retirement and educational aspirations without compromise.
Strategically Balance Contributions to Ensure Future Security
Balancing contributions between college savings and retirement funds requires a clear strategy to ensure both goals are met without undue financial strain. Start by prioritizing your retirement savings, as it typically offers fewer alternatives like loans or scholarships compared to college funding. Make sure to maximize your employer’s 401(k) match, as this is essentially free money that can significantly boost your retirement nest egg. Additionally, consider contributing to a Roth IRA, which offers tax-free withdrawals in retirement, providing flexibility in managing future expenses.
Once your retirement contributions are on track, focus on college savings. Utilize a 529 plan for its tax advantages and investment growth potential, making sure to align it with your child’s anticipated college entry date. Diversify your investments within the 529 plan to balance risk and reward as your child approaches college age. Consider the following strategies to optimize your savings efforts:
- Automatic Contributions: Set up automatic transfers to your 529 plan to ensure consistent saving.
- Gift Contributions: Encourage family and friends to contribute to your child’s college fund during birthdays or holidays.
- Tax Credits: Take advantage of education tax credits like the American Opportunity Credit, which can offset some of the costs of higher education.
By carefully planning and adjusting your financial strategy over time, you can effectively secure both your retirement and your child’s educational future.
Explore Scholarships and Grants to Reduce Out-of-Pocket Costs
Unlocking the potential of scholarships and grants can significantly ease the financial burden of college expenses. These opportunities are not just for those with exceptional academic achievements; they are available for various talents, backgrounds, and interests. Begin your search by exploring resources such as the Free Application for Federal Student Aid (FAFSA), which provides access to federal grants. Don’t overlook the College Board’s Scholarship Search tool, which helps identify potential scholarships based on personal criteria.
To maximize your chances, consider the following strategies:
- Research Local Opportunities: Many community organizations and local businesses offer scholarships. Check with local civic groups, libraries, and community centers.
- Leverage School Resources: High school counselors and college financial aid offices often have information on lesser-known scholarships and grants.
- Apply Early and Often: Many scholarships have early deadlines. Regularly check for new opportunities and apply to as many as possible.
- Tailor Your Applications: Customize your essays and applications to reflect how your skills and experiences align with each scholarship’s criteria.
By proactively seeking out these financial resources, you can significantly reduce your college expenses without compromising your retirement savings.
Leverage Financial Planning Tools for Optimal Resource Allocation
To effectively balance saving for college and retirement, it’s crucial to utilize modern financial planning tools that can streamline your resource allocation. Budgeting apps and investment calculators can provide valuable insights into your financial health and future needs. By setting clear, measurable goals within these platforms, you can visualize the impact of your savings strategies over time. Consider tools that allow for scenario planning, enabling you to explore different outcomes based on various saving and investment rates.
Additionally, leveraging tax-advantaged accounts can significantly enhance your saving efforts. Options like 529 plans for college savings and IRAs for retirement can offer substantial tax benefits, helping you maximize your contributions to both. To ensure optimal allocation, regularly review and adjust your contributions based on changes in income, expenses, or financial goals. This proactive approach, supported by robust financial tools, ensures that both your educational and retirement aspirations are met without undue compromise.