In today’s fast-paced world, achieving financial stability and securing a prosperous future for your family requires more than just good intentions; it demands a strategic approach. Enter SMART financial goals—a powerful framework designed to transform your family’s financial dreams into actionable plans. By setting Specific, Measurable, Achievable, Relevant, and Time-bound objectives, you can navigate the complexities of personal finance with clarity and confidence. This article will guide you through the process of crafting SMART financial goals tailored to your family’s unique needs, ensuring that each step you take is purposeful and aligned with your long-term vision. Whether you’re saving for your children’s education, planning for retirement, or building an emergency fund, mastering the art of SMART goal setting is the key to unlocking a future of financial security and peace of mind.
Understanding the SMART Criteria for Financial Success
To achieve financial success, it is crucial to establish goals that are both realistic and motivating. The SMART criteria provide a structured approach to goal setting, ensuring that your family’s financial objectives are Specific, Measurable, Achievable, Relevant, and Time-bound. By incorporating these principles, you create a clear roadmap for your financial journey, allowing you to track progress and make informed decisions along the way.
- Specific: Clearly define what you want to accomplish. Instead of setting a vague goal like “save money,” aim for something precise, such as “save $10,000 for a family vacation.”
- Measurable: Establish criteria to measure progress. Determine how you will track your savings, whether through monthly statements or a budgeting app.
- Achievable: Ensure the goal is realistic given your current financial situation. Analyze your income and expenses to see if setting aside a certain amount each month is feasible.
- Relevant: Align the goal with your family’s broader financial priorities and life aspirations. Consider how saving for a vacation fits into your overall financial plan.
- Time-bound: Set a deadline to create a sense of urgency and motivation. Decide on a specific date by which you plan to reach your savings goal.
Aligning Family Values with Financial Objectives
Bridging the gap between your family’s values and financial aspirations is essential for crafting a harmonious financial plan. Begin by identifying the core values that resonate with your family, such as education, health, or adventure. Once these are established, align them with your financial goals to create a roadmap that reflects your family’s priorities. Here’s how:
- Specific: Clearly define what you want to achieve. If education is a priority, specify the amount needed for college tuition.
- Measurable: Quantify your goals. Track your progress by setting milestones, like saving a certain amount each month.
- Achievable: Set realistic targets based on your current financial situation. Break larger goals into manageable steps.
- Relevant: Ensure each goal aligns with your family’s values. If health is a focus, allocate funds for gym memberships or organic groceries.
- Time-bound: Establish a timeline for each goal. Decide when you want to achieve them, such as having a fully funded college fund in ten years.
By aligning your financial objectives with your family’s core values, you create a strategy that is not only practical but also deeply meaningful. This alignment fosters a sense of unity and purpose, making the journey towards your financial goals a rewarding experience for everyone involved.
Creating a Step-by-Step Plan for Achieving Financial Goals
To effectively reach your family’s financial aspirations, it’s essential to break down your objectives into manageable steps. Start by identifying each financial goal and ensure it aligns with the SMART criteria—Specific, Measurable, Achievable, Relevant, and Time-bound. This clarity will guide your planning process and keep your efforts focused.
- Specific: Clearly define what you want to accomplish. Instead of setting a vague goal like “save money,” specify an amount, such as “save $20,000 for a family vacation.”
- Measurable: Determine how you will track your progress. For example, you could measure your savings by setting monthly targets to ensure you stay on course.
- Achievable: Assess your current financial situation and resources. Set goals that are challenging yet within reach, so you maintain motivation without feeling overwhelmed.
- Relevant: Ensure that your goals align with your family’s broader financial priorities, such as paying off debt or investing for future education.
- Time-bound: Set a realistic timeline for achieving each goal. Having a deadline creates a sense of urgency and helps prevent procrastination.
With a well-structured plan, you can systematically approach each step, celebrate small victories along the way, and steadily progress towards securing your family’s financial future.
Monitoring Progress and Adjusting Financial Strategies
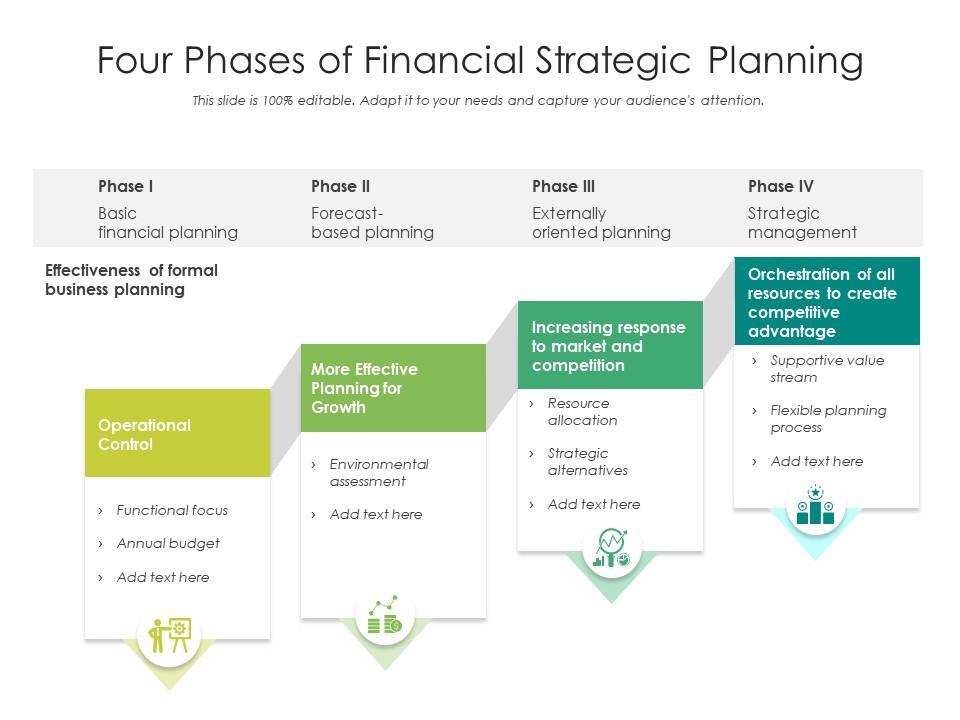
Consistently evaluating your family’s financial progress is crucial in ensuring your SMART goals remain relevant and achievable. Regularly review your financial statements, budgets, and expenditures to identify trends and areas that require adjustment. This involves setting aside time each month or quarter to analyze your financial health. Look for patterns such as overspending in certain categories or underfunding in others. Effective monitoring allows you to make informed decisions and pivot your strategies as needed.
Consider implementing the following practices to stay on track:
- Schedule regular financial check-ins: Use calendar reminders to keep these meetings consistent.
- Use financial tracking tools: Leverage apps or software that provide insights into your spending habits.
- Set benchmarks: Establish interim goals that serve as checkpoints to gauge progress.
- Stay informed: Keep abreast of economic changes that might affect your financial strategies.
By routinely monitoring your progress, you can swiftly adapt to changes, ensuring your financial strategies remain aligned with your family’s evolving needs and goals.