

In today’s fast-paced world, maintaining a firm grasp on your family’s financial trajectory can often feel like navigating through a maze. Yet, with the right strategies and a clear focus, staying on track with your family’s financial goals is not only achievable but can also lead to greater stability and peace of mind. This guide will equip you with practical steps and expert advice to help you prioritize your spending, save effectively, and plan for a prosperous future. Whether you’re aiming to build an emergency fund, save for a family vacation, or invest in your children’s education, this article will provide the tools you need to turn your financial aspirations into reality. Embrace the confidence that comes from being in control of your financial destiny and let’s embark on this journey together.
Setting Clear Objectives for Your Familys Financial Future
Establishing a solid financial foundation begins with crafting precise and achievable objectives. Start by engaging in a family discussion to identify what truly matters to each member. Consider goals like building an emergency fund, saving for a dream vacation, or planning for your children’s education. Once you’ve identified your priorities, categorize them into short-term and long-term goals. This helps in visualizing the journey ahead and setting a timeline for each objective.
To ensure success, break down larger goals into manageable tasks. This could include actions such as creating a monthly budget, cutting unnecessary expenses, or setting up automatic savings transfers. Regularly review and adjust your plan to accommodate life’s changes. Key strategies include:
- Setting specific and measurable targets
- Allocating resources effectively
- Tracking progress regularly
- Celebrating small victories to stay motivated
By taking these steps, you empower your family to not only envision their financial future but actively work towards making it a reality.
Creating a Realistic Budget That Everyone Can Follow
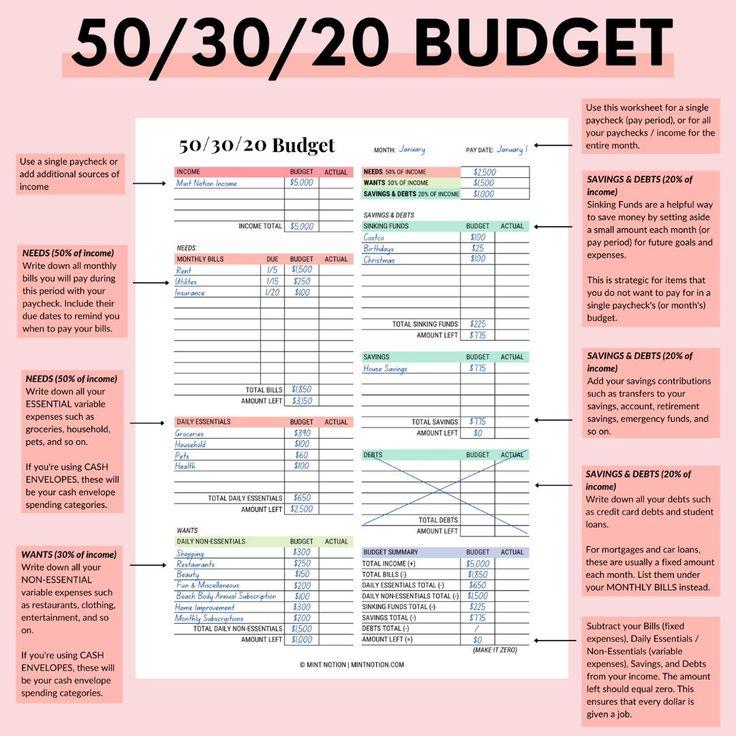
To build a practical budget that truly works for everyone in the family, start by identifying your financial priorities. This might include paying off debt, saving for a vacation, or building an emergency fund. Once your priorities are clear, break them down into achievable goals. Consider using the following steps:
- Track your expenses: Keep a record of every dollar spent for a month to understand your spending habits.
- Categorize your spending: Divide expenses into fixed (like rent or mortgage) and variable (like dining out or entertainment) categories.
- Set realistic limits: Allocate a reasonable amount to each category, ensuring you have enough to cover essentials while still setting aside funds for savings and goals.
Incorporate flexibility into your budget to accommodate unexpected expenses. Regularly review and adjust your budget to reflect any changes in income or expenses. This dynamic approach ensures that your budget remains a reliable tool for achieving your family’s financial aspirations.
Leveraging Technology to Monitor and Adjust Your Progress
In today’s digital age, harnessing technology is crucial to keeping your family’s financial goals on track. From budgeting apps to online investment platforms, there are myriad tools designed to streamline the process of monitoring and adjusting your financial progress. Budgeting apps such as YNAB (You Need A Budget) or Mint allow you to track spending in real-time, categorize expenses, and even set alerts for overspending. This immediate feedback loop ensures that you can quickly adapt to any financial missteps, keeping you aligned with your financial objectives.
Consider the use of financial dashboards that consolidate all your accounts in one place, providing a comprehensive view of your financial health. Tools like Personal Capital offer features that let you visualize your net worth, analyze your investment portfolio, and plan for future goals. Moreover, take advantage of automated savings tools which can effortlessly transfer funds to savings or investment accounts based on your pre-set rules. By leveraging these technologies, you’re not just reacting to your financial situation; you’re proactively managing it. This approach empowers you to make informed decisions, ensuring that your family’s financial future remains on a steady path.
Building a Supportive Environment to Foster Financial Discipline
Creating a nurturing atmosphere at home is crucial for achieving your financial aspirations as a family. Begin by establishing open communication about money matters. Encourage family members to share their thoughts and ideas, ensuring that everyone feels heard and respected. This can be facilitated through regular family meetings where financial goals are discussed and progress is reviewed.
- Set clear and achievable goals: Break down long-term objectives into smaller, manageable tasks.
- Celebrate milestones: Recognize and reward the family when you reach a financial target.
- Educate each other: Share articles, books, or podcasts about financial literacy to enhance understanding.
- Create visual reminders: Use charts or vision boards to keep the family’s financial objectives in sight.
By fostering a collaborative environment, each family member becomes a contributor to the financial journey, creating a shared sense of responsibility and accomplishment.




