
In the ever-evolving landscape of financial planning, creating a robust family investment plan for real estate wealth building stands out as a strategic avenue for securing long-term prosperity. As real estate continues to be one of the most reliable and tangible assets, families seeking to enhance their financial portfolio can greatly benefit from a well-structured approach to property investment. This article delves into the intricacies of crafting a family investment plan, offering analytical insights into market trends, risk management, and portfolio diversification. With a confident stride towards financial independence, this guide aims to equip families with the knowledge and tools necessary to navigate the complexities of real estate, ensuring not only wealth accumulation but also intergenerational financial stability. Whether you are a seasoned investor or just beginning your journey, understanding the foundational principles of real estate investment can pave the way for a legacy of economic security and growth.
Identifying Lucrative Real Estate Opportunities for Long-term Growth
To ensure sustained financial growth in real estate, it’s crucial to pinpoint areas with high potential for appreciation. Conduct thorough market research to identify neighborhoods that are on the cusp of development. Look for indicators such as planned infrastructure projects, increasing employment opportunities, and demographic trends that favor young professionals or families. Additionally, analyze historical data on property values in the area to spot consistent growth patterns.
Consider the following factors when assessing potential investments:
- Economic Indicators: Examine local economic health, including job growth rates and business investments.
- Location and Accessibility: Properties close to public transportation, schools, and shopping centers often see higher demand.
- Supply and Demand Dynamics: A low supply of housing coupled with high demand can drive up property values over time.
By focusing on these elements, you can uncover properties that promise long-term value appreciation, setting a solid foundation for your family’s real estate wealth-building strategy.
Structuring a Diverse Portfolio to Mitigate Risks and Maximize Returns
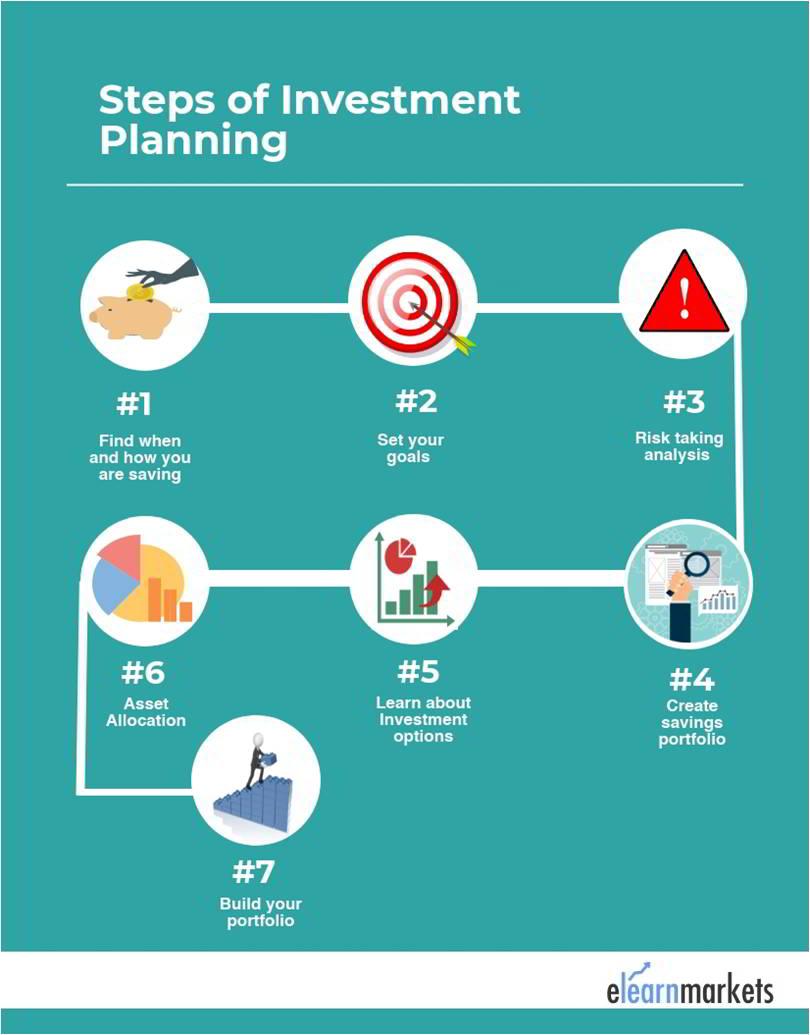
In the quest to build a robust real estate investment strategy, diversification is a critical element. A well-structured portfolio not only reduces risks but also enhances the potential for long-term gains. To achieve this, consider spreading investments across various property types and geographic locations. This approach ensures that your family is not overly reliant on any single market segment, providing a buffer against market volatility. Residential properties, such as single-family homes and multi-family units, offer steady rental income and long-term appreciation potential. On the other hand, commercial properties, including office spaces and retail outlets, can yield higher returns albeit with higher risk. Incorporating vacation rentals or industrial spaces adds another layer of diversification, tapping into different economic cycles and tenant demands.
Another essential aspect of a diverse portfolio is balancing active and passive investments. Active investments, where you are involved in managing and improving properties, can significantly increase returns through strategic enhancements and market timing. However, they also require more time and expertise. On the contrary, passive investments, such as Real Estate Investment Trusts (REITs), allow you to benefit from real estate markets without direct management responsibilities, thus reducing operational risks. By combining these strategies, your family can effectively mitigate risks while seizing opportunities for wealth accumulation in real estate. This multi-faceted approach ensures that your investment plan is resilient and capable of adapting to changing market conditions.
Leveraging Financing Options and Tax Benefits to Enhance Investment Value
When structuring a family investment plan for real estate, strategic financing and savvy tax planning are crucial tools for maximizing returns. Start by exploring various financing options such as traditional mortgages, home equity loans, and private lenders. Each option has unique terms and benefits, so analyze them carefully to determine which aligns best with your family’s financial goals and risk tolerance. Creative financing solutions, such as seller financing or lease-to-own agreements, can also provide flexibility and potentially lower initial costs.
On the tax front, leveraging benefits can significantly enhance your investment’s profitability. Consider the following strategies:
- Depreciation Deductions: Reduce taxable income by accounting for property wear and tear.
- 1031 Exchanges: Defer capital gains taxes by reinvesting proceeds from a property sale into a similar investment.
- Mortgage Interest Deductions: Deduct interest payments on mortgages from taxable income.
- Tax Credits: Explore credits for energy-efficient upgrades or rehabilitation of historic properties.
By combining these financial and tax strategies, you can enhance the overall value of your family’s real estate investments, ensuring long-term wealth growth and stability.
Implementing a Family-Centric Decision-Making Framework for Cohesive Planning
Incorporating a family-focused approach to decision-making can significantly enhance the effectiveness of your real estate investment strategy. A family-centric framework not only ensures that everyone’s voice is heard but also aligns investment goals with family values and long-term aspirations. To achieve this, begin by establishing a platform for open communication where each member can express their ideas and concerns. This collaborative environment fosters trust and ensures that decisions are made with a comprehensive understanding of family priorities.
- Shared Vision: Develop a unified vision for the family’s financial future, considering both short-term gains and long-term wealth accumulation.
- Role Assignment: Clearly define roles and responsibilities for each family member based on their skills and interests to streamline the decision-making process.
- Periodic Reviews: Schedule regular meetings to review the investment portfolio’s performance, allowing for adjustments in strategy as needed.
By implementing these practices, families can create a dynamic and adaptable investment plan that not only builds wealth but also strengthens family bonds. This approach transforms real estate investing from a solitary endeavor into a collective journey, driven by shared ambitions and mutual support.