
In an era marked by economic uncertainty and fluctuating financial landscapes, establishing a robust long-term investment plan for your family has never been more critical. As families navigate the complexities of securing financial stability and future prosperity, a strategic approach to investment can serve as a cornerstone for achieving these goals. This article delves into the analytical process of crafting a comprehensive long-term investment plan tailored to your family’s unique needs and aspirations. By evaluating risk tolerance, setting clear financial objectives, and diversifying assets, we will guide you through the essential steps to build a resilient investment strategy. With confidence and precision, this roadmap aims to empower you to make informed decisions that will safeguard and grow your family’s wealth for generations to come.
Assessing Family Financial Goals and Risk Tolerance
When embarking on the journey of crafting a long-term investment plan, understanding your family’s financial goals and risk tolerance is paramount. Start by identifying what your family aims to achieve financially. Are you saving for your children’s education, a comfortable retirement, or perhaps a dream home? Having clear, well-defined goals provides direction and focus, allowing you to tailor your investment strategy to meet these objectives. It’s essential to categorize these goals by time horizon, such as short-term, medium-term, and long-term, to align with appropriate investment vehicles.
Equally crucial is assessing your family’s risk tolerance. This involves evaluating how much risk you are willing to take in pursuit of higher returns. Factors influencing risk tolerance include your current financial situation, investment experience, and psychological comfort with market fluctuations. To gauge this, consider the following aspects:
- Age and Time Horizon: Younger families might be more open to riskier investments due to a longer time horizon, whereas older families might prefer stability.
- Income Stability: A stable income might encourage more aggressive investment strategies, while variable income could necessitate a more conservative approach.
- Previous Investment Experience: Familiarity with investment markets can affect comfort levels with riskier assets.
By meticulously evaluating these elements, you can construct a robust investment plan that not only aligns with your family’s aspirations but also respects its comfort level with risk.
Diversifying Investments to Balance Growth and Stability
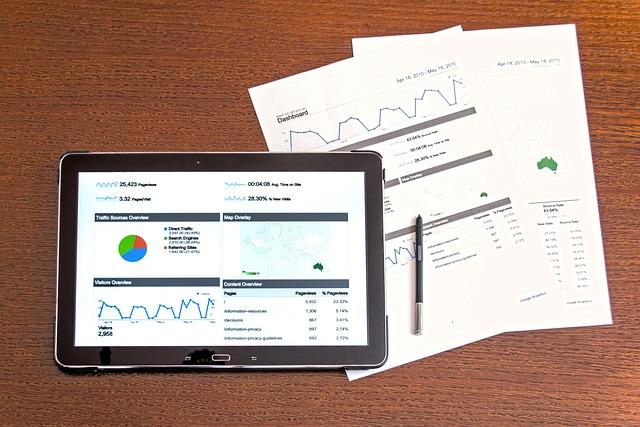
To craft a resilient investment strategy that navigates both growth and stability, it’s essential to consider a mix of asset classes that respond differently to market dynamics. This approach can mitigate risks while maximizing potential returns over time. Consider incorporating stocks, which offer substantial growth opportunities but come with higher volatility. Balancing this with bonds can provide a cushion against market downturns, as they typically offer lower returns but with less risk. Additionally, real estate investments can add another layer of stability, offering both income through rentals and potential appreciation.
Diversification can also be achieved by exploring alternative investments like commodities and cryptocurrencies. These assets often move independently of traditional markets, providing a hedge against economic fluctuations. Furthermore, investing in international markets can expose your portfolio to different economic cycles and opportunities for growth. As you build this diverse mix, it’s crucial to regularly review and adjust your portfolio to align with changing market conditions and family goals, ensuring that the balance between growth and stability remains intact.
Implementing Tax-Efficient Strategies for Wealth Accumulation
Maximizing wealth accumulation while minimizing tax liabilities is a nuanced art that requires a well-thought-out strategy. One effective approach is to leverage tax-advantaged accounts. Consider these key accounts:
- 401(k) Plans: Contributions are made pre-tax, reducing taxable income for the year. Additionally, many employers offer matching contributions, effectively increasing your savings.
- Roth IRAs: While contributions are made with after-tax dollars, the advantage lies in tax-free withdrawals during retirement, offering significant savings in the long run.
Another strategy involves the strategic use of capital gains and losses. Here’s how you can optimize this:
- Harvesting Losses: By selling investments that have declined in value, you can offset capital gains, reducing your overall tax liability.
- Long-Term Gains: Holding onto investments for over a year allows you to benefit from lower long-term capital gains tax rates, which can be significantly less than short-term rates.
Regularly Reviewing and Adjusting the Investment Plan
In the dynamic world of investments, a set-it-and-forget-it approach might not yield the desired outcomes for your family’s financial future. Regular evaluation of your investment plan is crucial to ensure alignment with evolving market conditions and personal financial goals. Reviewing your investment strategy periodically allows you to adapt to changes such as market volatility, life events, or shifts in your risk tolerance. It’s not just about assessing past performance but also about making informed decisions for the future.
- Market Conditions: Stay informed about economic trends that may impact your investments, such as interest rate changes or geopolitical events.
- Life Changes: Consider adjustments when major life events occur, like the birth of a child, career shifts, or retirement planning.
- Risk Tolerance: Reassess your comfort level with risk, especially during times of significant market fluctuations.
By proactively managing your investment plan, you not only safeguard your family’s financial health but also seize opportunities for growth and diversification. Utilize tools and resources, such as financial advisors or investment apps, to aid in this ongoing process, ensuring your family’s financial legacy is both resilient and robust.