Friday, November 20, 2026
9.8 C
London

How to set and achieve financial goals for building an education fund

In today’s rapidly evolving world, securing a solid education has never been more crucial for unlocking future opportunities and achieving personal success. As parents and guardians, one of the most impactful investments you can make is building a robust education fund for your children. However, the path to accumulating sufficient financial resources for educational purposes is often riddled with uncertainties and challenges. This article is designed to guide you through the essential steps of setting and achieving financial goals specifically tailored for an education fund. By adopting a structured approach, you can transform aspirations into actionable plans, ensuring a bright academic future for your loved ones. With confidence and clarity, we will explore practical strategies, from defining clear objectives to implementing effective savings techniques, empowering you to create a lasting educational legacy.

Identifying Your Education Funding Needs

Before diving into the world of education funding, it’s crucial to understand your specific needs. This involves taking a close look at several factors that will shape your financial strategy. Start by evaluating the type of education you or your loved ones are pursuing. Are we talking about a private university, community college, or trade school? Each option comes with its own set of costs. Consider the duration of the program and whether it requires special equipment or materials, which can add to your financial burden. Another important aspect is the geographic location; studying abroad or out-of-state may significantly increase living expenses.

  • Current savings: Assess what you already have set aside.
  • Potential scholarships or grants: Research opportunities that could offset costs.
  • Inflation and future cost projections: Estimate how much education costs may rise over the years.
  • Additional income sources: Consider part-time work or family contributions.

By understanding these elements, you lay the groundwork for setting realistic and achievable financial goals, ensuring your education funding strategy is both comprehensive and effective.
Crafting a Realistic and Achievable Savings Plan

Crafting a Realistic and Achievable Savings Plan

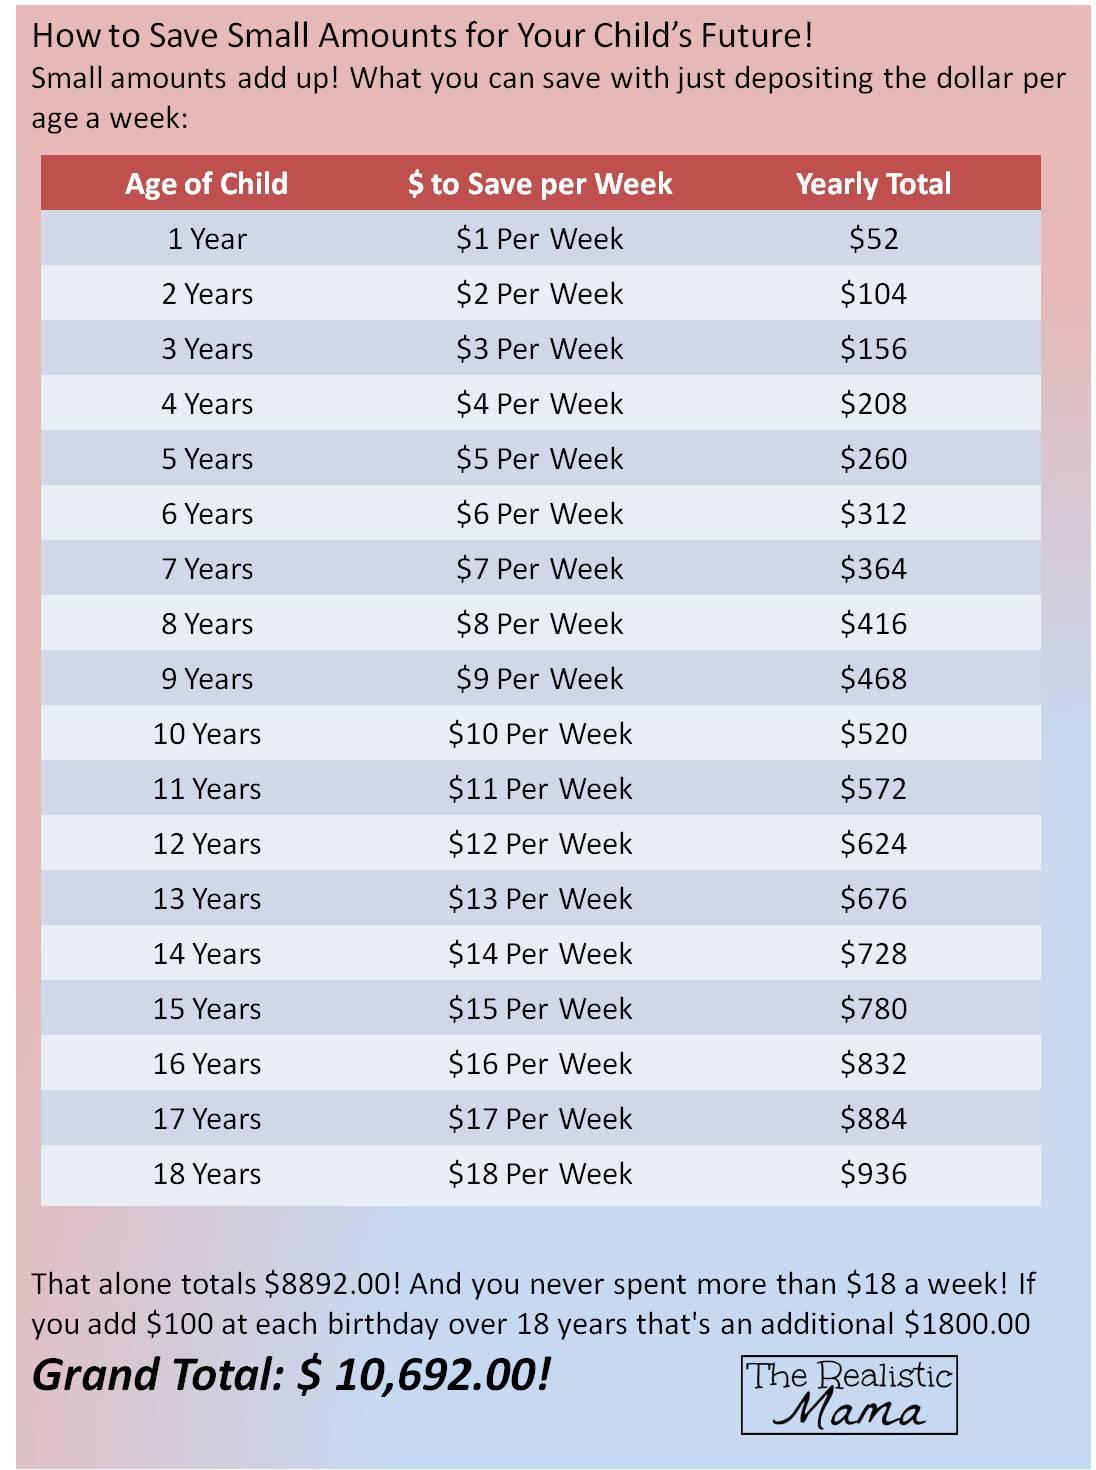
When embarking on the journey to build an education fund, it’s crucial to establish a strategy that aligns with your financial situation and future aspirations. Start by identifying the total amount you’ll need for the education fund, considering factors like tuition fees, living expenses, and potential inflation. Break this amount into smaller, more manageable targets, and set a timeline for achieving each one. This not only makes the goal less daunting but also helps maintain motivation as you reach each milestone.

  • Analyze your current finances: Review your income, expenses, and any existing debts. This will give you a clear picture of your financial standing and how much you can realistically save each month.
  • Automate your savings: Set up automatic transfers to your education fund to ensure consistency and discipline in saving.
  • Track and adjust: Regularly review your progress and be flexible to make adjustments if needed. Life is unpredictable, and it’s important to adapt your plan to changing circumstances.
  • Explore investment options: Consider investing a portion of your savings to potentially grow your fund faster. Consult with a financial advisor to explore options that match your risk tolerance.

By structuring your savings plan with clear, realistic goals and actionable steps, you’ll be well on your way to securing a bright educational future.
Exploring Investment Options to Maximize Growth
Exploring Investment Options to Maximize Growth

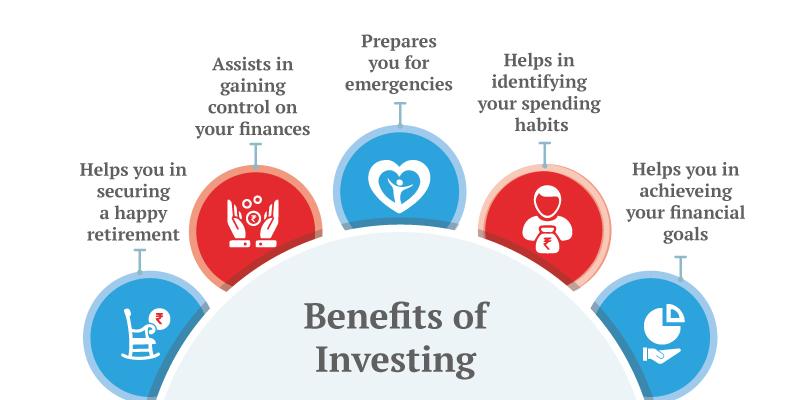
When planning to build an education fund, it’s crucial to explore a variety of investment options to ensure growth and security. Start by considering diversified portfolios that include a mix of stocks, bonds, and mutual funds. Diversification helps mitigate risk while maximizing potential returns. Additionally, explore index funds and exchange-traded funds (ETFs) as cost-effective options that offer broad market exposure.

  • Stocks: Offer high growth potential, but come with higher risk.
  • Bonds: Provide stability and regular income, ideal for risk-averse investors.
  • Mutual Funds: Managed by professionals, offering diversification and convenience.
  • Index Funds/ETFs: Low-cost, diversified, and track specific market indices.

Don’t overlook the power of compound interest; starting early can significantly boost your fund over time. Consider setting up a 529 plan or other tax-advantaged accounts to maximize your savings. Regularly review and adjust your investment strategy to align with your evolving financial goals and market conditions. By staying informed and proactive, you can confidently build a robust education fund for the future.

Monitoring Progress and Adjusting Strategies

Monitoring Progress and Adjusting Strategies

To ensure you’re on the right track towards building a robust education fund, it’s crucial to consistently evaluate your progress and make necessary adjustments. Begin by setting regular check-ins, perhaps monthly or quarterly, to review your financial statements and compare them against your goals. Look for patterns in your spending and saving habits that might require modification. During these evaluations, ask yourself:

  • Are my savings contributions meeting my expectations?
  • Have there been any unexpected expenses that impacted my fund?
  • Is the growth of my investments aligned with my projections?

If you notice discrepancies or areas of concern, don’t hesitate to pivot your strategy. Consider increasing your monthly contributions, exploring new investment opportunities, or cutting back on non-essential expenses. Utilize budgeting tools or apps to track your progress more effectively. Remember, flexibility is key; adapting to changes promptly can significantly enhance your ability to reach your financial goals.


Hot this week

Family budgeting strategies for large families

Mastering family budgeting for large households involves prioritizing expenses, tracking spending, and leveraging bulk purchases. Set clear financial goals, involve all family members, and use apps to streamline and monitor the budget effectively.

How to create a family financial roadmap with clear milestones

Start by assessing your current financial situation and setting specific, achievable goals. Break these into short-term, medium-term, and long-term milestones. Regularly review and adjust your plan to stay on track and ensure family financial stability.

How to balance short term and long term financial goals as a family

Balancing short-term and long-term financial goals as a family requires clear communication, prioritizing needs, and setting realistic timelines. Start with a budget that allocates funds for immediate expenses while saving for future aspirations.

Pros and Cons of Debt Management Programs vs Debt Settlement

Debt management programs offer structured repayment plans to help manage debt, promoting financial discipline and often reducing interest rates. In contrast, debt settlement negotiates debt reductions but may harm credit scores and incur fees.

The Benefits of Debt Management Plans for Families

Debt Management Plans (DMPs) offer families a structured path to financial stability by consolidating debts into manageable payments. They reduce interest rates and monthly burdens, empowering families to regain control over their financial future.

Topics

Family budgeting strategies for large families

Mastering family budgeting for large households involves prioritizing expenses, tracking spending, and leveraging bulk purchases. Set clear financial goals, involve all family members, and use apps to streamline and monitor the budget effectively.

How to create a family financial roadmap with clear milestones

Start by assessing your current financial situation and setting specific, achievable goals. Break these into short-term, medium-term, and long-term milestones. Regularly review and adjust your plan to stay on track and ensure family financial stability.

How to balance short term and long term financial goals as a family

Balancing short-term and long-term financial goals as a family requires clear communication, prioritizing needs, and setting realistic timelines. Start with a budget that allocates funds for immediate expenses while saving for future aspirations.

Pros and Cons of Debt Management Programs vs Debt Settlement

Debt management programs offer structured repayment plans to help manage debt, promoting financial discipline and often reducing interest rates. In contrast, debt settlement negotiates debt reductions but may harm credit scores and incur fees.

The Benefits of Debt Management Plans for Families

Debt Management Plans (DMPs) offer families a structured path to financial stability by consolidating debts into manageable payments. They reduce interest rates and monthly burdens, empowering families to regain control over their financial future.

How to Plan for Rising Costs During Retirement

To tackle rising costs in retirement, start by creating a detailed budget that accounts for inflation. Diversify your investment portfolio to hedge against market volatility, and consider healthcare savings plans to cover medical expenses.

Top Tips for Saving Money on Groceries Every Month

Cut costs with a meal plan: Plan weekly meals to avoid impulse buys. Buy in bulk for non-perishables, and choose generic brands. Use loyalty programs and coupons for extra savings. Shop with a list to stay focused and on budget.

How to Set Financial Goals That Work for Your Family

Setting financial goals for your family begins with open communication. Identify priorities, set realistic timelines, and track progress regularly. By aligning goals with family values, you create a plan that’s both motivating and achievable.
spot_img

Related Articles

Popular Categories

spot_imgspot_img