
Planning for retirement is a crucial step in securing your financial future, yet many people hesitate to take action, fearing it will require significant sacrifices in their current lifestyle. The good news is that you can build a robust retirement fund without drastically altering your day-to-day living. In this guide, we will explore the most effective strategies to save for retirement while maintaining the lifestyle you enjoy. By implementing smart financial habits and leveraging innovative saving tools, you can create a balanced approach that supports both your present needs and future goals. Get ready to embark on a journey towards financial security with confidence and ease. Employer-Sponsored Retirement Plans for Long-Term Benefits”>
Maximize Employer-Sponsored Retirement Plans for Long-Term Benefits
To leverage the full potential of employer-sponsored retirement plans, it is essential to understand and maximize the benefits these plans offer. Start by ensuring you’re contributing enough to get the full employer match, as this is essentially free money that can significantly boost your retirement savings. Review your plan options regularly, and consider increasing your contributions whenever you receive a raise or bonus. This way, you’re building your nest egg without feeling the pinch in your current budget.
Many plans offer a variety of investment choices, so take the time to diversify your portfolio based on your risk tolerance and retirement timeline. This strategy can help in balancing potential growth with risk management. Additionally, keep an eye out for any changes in the plan’s features or benefits. Stay informed about any new options or tools your employer may offer, such as financial planning resources or automatic contribution increases, which can further enhance your savings strategy. By taking these proactive steps, you can effectively use your employer-sponsored retirement plan to its fullest, securing long-term financial benefits without compromising your present lifestyle.
Leverage Tax-Advantaged Accounts to Enhance Your Savings
Maximizing your retirement savings without affecting your day-to-day life can be seamlessly achieved by tapping into tax-advantaged accounts. These accounts not only offer potential tax benefits but also encourage disciplined saving habits. Consider utilizing the following:
- 401(k) Plans: Many employers offer 401(k) plans, which allow you to contribute pre-tax income. This reduces your taxable income and can lead to significant tax savings. Additionally, many employers match contributions, which is essentially free money for your retirement fund.
- Roth IRA: Unlike traditional IRAs, contributions to a Roth IRA are made with after-tax dollars, allowing your money to grow tax-free. This can be particularly advantageous if you expect to be in a higher tax bracket during retirement.
- Health Savings Accounts (HSAs): If you have a high-deductible health plan, an HSA can be a powerful tool. Contributions are tax-deductible, and withdrawals for qualified medical expenses are tax-free. After age 65, withdrawals for any purpose are taxed like a traditional IRA, providing flexibility in retirement planning.
Strategically using these accounts can substantially boost your retirement savings while still allowing you to maintain your current lifestyle. Focus on maximizing contributions to these accounts, as the compound growth potential can significantly enhance your financial security in retirement.
Adopt Smart Budgeting Strategies to Preserve Your Lifestyle
To ensure you can enjoy both your present lifestyle and a comfortable retirement, consider integrating smart budgeting strategies into your financial plan. Begin by analyzing your spending habits to identify areas where you can cut back without feeling deprived. This could involve eliminating subscriptions you rarely use or opting for homemade meals instead of dining out. Next, automate your savings to make sure a portion of your income is consistently directed towards your retirement fund. This can be easily set up through your bank or employer, ensuring that saving becomes a seamless part of your financial routine.
- Track Expenses: Use budgeting apps to keep an eye on where your money goes.
- Prioritize High-Interest Debt: Focus on paying off debts with the highest interest rates first to free up more money for savings.
- Embrace DIY Projects: Save on costs by taking on do-it-yourself projects for home maintenance and personal hobbies.
- Negotiate Bills: Contact service providers to negotiate better rates on utilities, insurance, and other recurring expenses.
By adopting these strategies, you not only safeguard your financial future but also maintain the lifestyle you cherish today. Remember, the goal is to create a balance that allows you to save effectively without feeling like you’re missing out on life’s pleasures.
Explore Diverse Investment Options for Optimal Growth
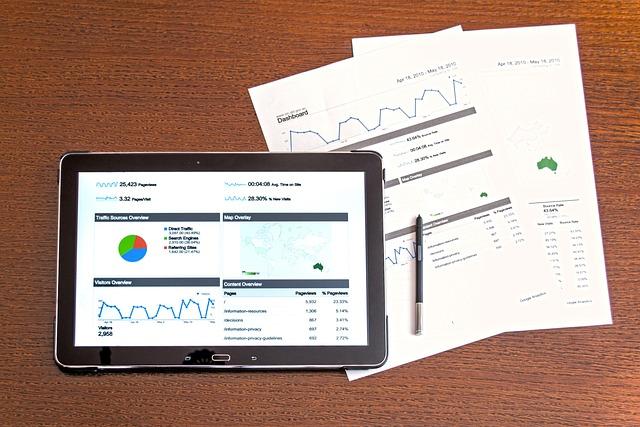
When planning for a comfortable retirement, it’s essential to consider a range of investment options that can help grow your savings without compromising your present lifestyle. Diversifying your investment portfolio is a strategic way to balance risk and reward. Here are some diverse investment avenues to consider:
- Stocks and Bonds: A balanced mix of equities and fixed-income securities can offer growth potential while providing stability. Consider index funds or ETFs for diversified exposure.
- Real Estate: Investing in property can provide rental income and capital appreciation. Real estate investment trusts (REITs) offer a more accessible way to invest without the need for direct property management.
- Retirement Accounts: Maximize contributions to tax-advantaged accounts like IRAs or 401(k)s. These accounts offer tax benefits that can enhance your long-term savings.
- Peer-to-Peer Lending: This innovative investment option allows you to lend directly to individuals or small businesses, potentially yielding higher returns than traditional savings accounts.
- Commodities: Diversifying with assets like gold, silver, or oil can hedge against inflation and economic uncertainty.
Remember, the key to successful retirement planning is to balance growth with security, ensuring that your investments align with your risk tolerance and financial goals.