
Navigating the path to a secure retirement can often feel like a daunting journey, especially for families in their 40s who are juggling multiple financial priorities. However, this pivotal decade presents a unique opportunity to fortify your financial future with strategic planning and informed decisions. In this article, we delve into the best retirement savings tips tailored specifically for families in their 40s, empowering you with the knowledge and confidence to build a robust retirement plan. By focusing on practical strategies and leveraging the advantages of this stage in life, you can transform potential challenges into opportunities for growth, ensuring a comfortable and fulfilling retirement for you and your loved ones.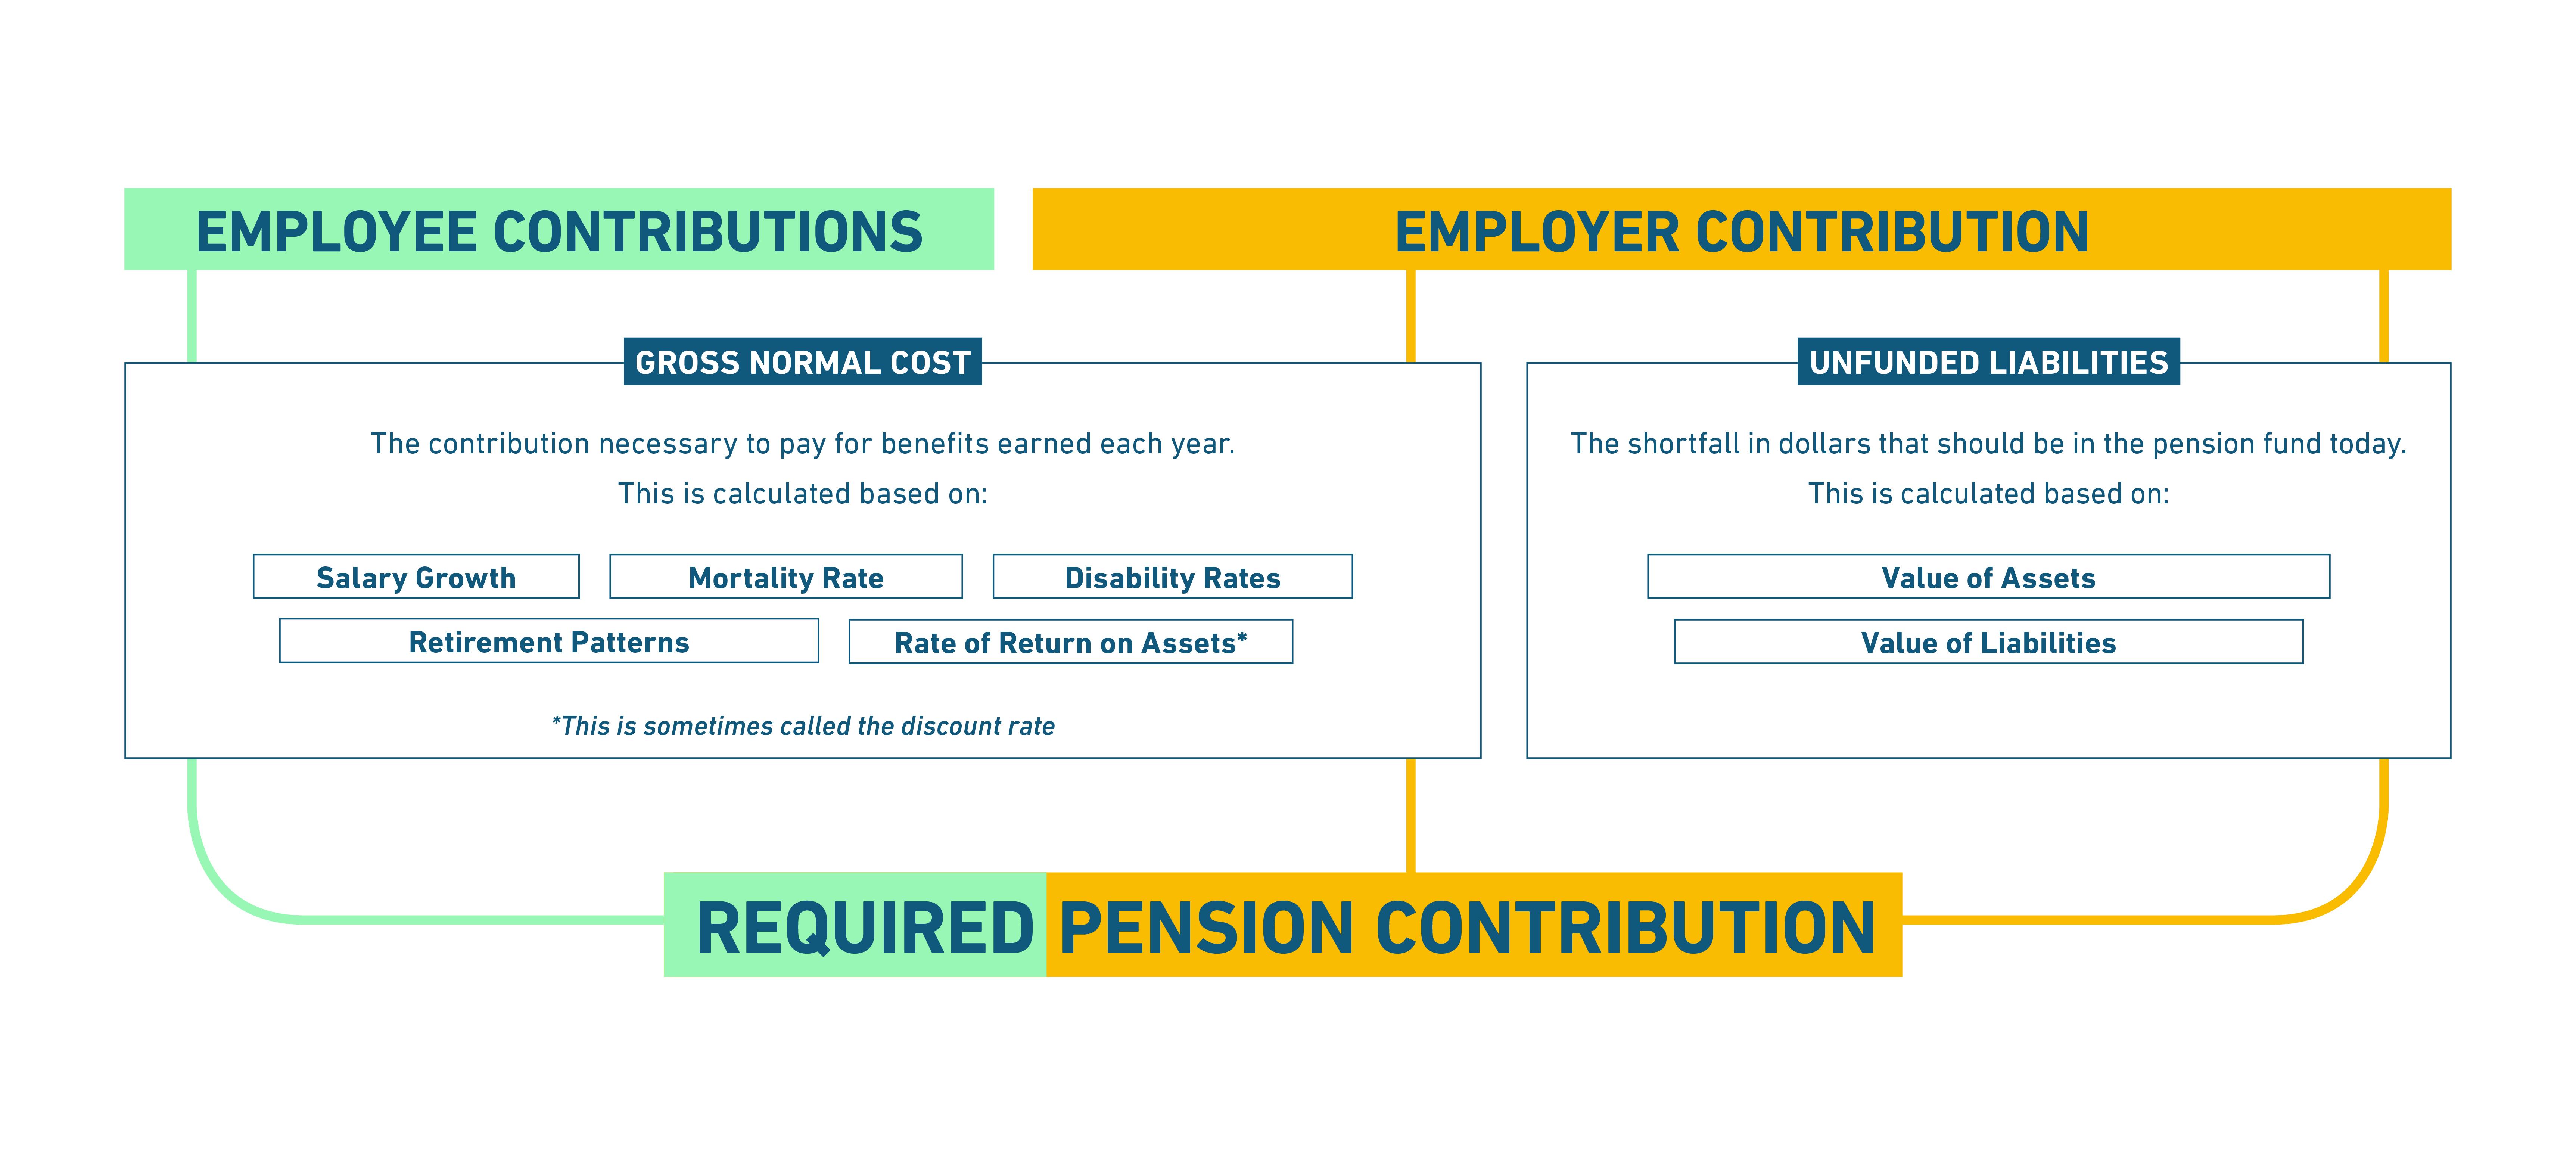
Maximize Employer Contributions and Tax Benefits
To fully leverage the benefits offered by your employer, it’s crucial to first understand your company’s retirement plan options. Many employers offer a 401(k) plan with matching contributions. These matches are essentially free money that boosts your savings without impacting your take-home pay. Make it a priority to contribute enough to get the full match—it’s an easy win for your future financial security.
Additionally, take advantage of the tax benefits associated with these contributions. By contributing to a traditional 401(k), you reduce your taxable income, which can result in significant tax savings each year. For those who are self-employed or whose employer doesn’t offer a retirement plan, consider options like a SEP IRA or Solo 401(k), both of which offer generous contribution limits and similar tax advantages. Keep these strategies in mind to ensure you are maximizing both employer contributions and tax benefits effectively.
Diversify Investments to Balance Risk and Growth
For families in their 40s, striking the right balance between risk and growth is crucial to building a robust retirement portfolio. The key to achieving this balance lies in diversifying your investments across various asset classes. By spreading your investments, you reduce the impact of a poor-performing asset on your overall portfolio. Consider including a mix of:
- Stocks: While they can be volatile, stocks offer the potential for higher returns, which are essential for long-term growth.
- Bonds: These provide a more stable income and can help cushion your portfolio against market fluctuations.
- Real Estate: Investing in property can offer both income and capital appreciation, acting as a hedge against inflation.
- Mutual Funds or ETFs: These are excellent options for those looking to invest in a diversified portfolio with professional management.
It’s important to regularly review and adjust your portfolio as you get closer to retirement, ensuring that your investment strategy aligns with your evolving risk tolerance and financial goals. Embrace diversification not just as a strategy, but as a financial philosophy that can safeguard your future.
Prioritize Emergency Funds for Financial Security
At this stage in life, families should emphasize the importance of having a robust safety net to shield against unforeseen circumstances. An emergency fund serves as a financial cushion, ensuring that unexpected expenses do not derail your long-term savings goals. Ideally, aim to save at least three to six months’ worth of living expenses. This might sound daunting, but breaking it down into smaller, manageable goals can make the task less overwhelming. Consider the following steps to build your emergency fund:
- Automate savings: Set up automatic transfers from your checking account to a dedicated savings account to ensure consistency.
- Cut unnecessary expenses: Review your monthly expenses and identify areas where you can cut back, redirecting those savings to your emergency fund.
- Prioritize windfalls: Whenever you receive unexpected money, such as tax refunds or bonuses, allocate a portion to bolster your fund.
- Reassess regularly: As your family grows and expenses change, regularly reassess your fund’s adequacy to ensure it still meets your needs.
By building and maintaining a solid emergency fund, you secure a critical layer of financial protection, allowing you to focus more confidently on your retirement savings strategies.
Leverage Technology for Streamlined Savings Management
Embracing the digital age can significantly enhance how families in their 40s manage their retirement savings. Utilizing financial management apps and online platforms offers a centralized approach to track, adjust, and optimize your savings strategies. Automated savings tools can be particularly beneficial, ensuring consistent contributions without manual oversight, while real-time analytics provide insights into spending habits and investment growth, helping you make informed decisions.
- Budgeting Apps: Tools like Mint or YNAB help you allocate funds efficiently, ensuring savings goals are met.
- Robo-Advisors: These platforms offer automated, algorithm-driven financial planning services, often with lower fees than traditional advisors.
- Online Investment Platforms: Use platforms like Vanguard or Fidelity to diversify your portfolio with ease.
- Retirement Calculators: Regularly use these to assess if you’re on track to meet your retirement goals.
By integrating these technologies, you can create a dynamic and responsive savings plan that adapts to life’s changes, providing peace of mind as you approach retirement.