Friday, November 20, 2026
9.8 C
London

How to Plan for Big Purchases Without Draining Your Savings

Making a significant purchase, whether it’s a new car, a dream vacation, or a home renovation, is an exciting milestone. However, the thrill of acquiring something new can quickly turn into financial stress if not approached with a strategic plan. The key to making big purchases without depleting your savings lies in careful planning and smart financial management. This guide will equip you with practical strategies to achieve your purchasing goals while maintaining a healthy savings balance. By the end of this article, you’ll be confident in your ability to manage your finances effectively, ensuring that your big purchase is a stepping stone to greater financial stability, not a stumbling block. Let’s delve into the steps you need to take to prepare for your next major expenditure without compromising your financial future.

Establish a Realistic Budget and Timeline

To make your big purchase dreams a reality without emptying your savings account, it’s crucial to craft a budget and timeline that are both achievable and well-structured. Start by evaluating your current financial situation and identifying all potential sources of income. This will give you a clear picture of how much you can comfortably allocate towards your purchase each month. Create a detailed list of all expenses, including fixed costs like rent and utilities, as well as variable ones like groceries and entertainment. This will help you determine the discretionary income available for your big purchase fund.

Once you’ve established your financial baseline, set a specific savings goal and a realistic timeframe to reach it. Break down your goal into manageable monthly or weekly savings targets. This will make the process less daunting and help you stay on track. Consider using a budgeting app or spreadsheet to monitor your progress and adjust as needed. Additionally, build in a buffer for unexpected expenses to avoid derailing your plan. Keep your eye on the prize, and remember that every small step forward brings you closer to your big purchase without sacrificing your financial stability.

  • Evaluate your income and expenses: Know your financial standing.
  • Set a specific savings goal: Define what you need and by when.
  • Break down your goal: Manageable chunks make it achievable.
  • Monitor your progress: Use tools to stay on track.
  • Include a buffer: Prepare for unexpected costs.
Identify and Prioritize Your Financial Goals

Identify and Prioritize Your Financial Goals

To effectively plan for major purchases without depleting your savings, it’s essential to first clarify what you truly value financially. Begin by listing all potential goals and then categorize them into short-term, medium-term, and long-term objectives. Ask yourself: What do I want to achieve in the next year? In five years? In a decade? Prioritize these goals based on urgency and importance. This process will give you a clear roadmap and help you allocate resources efficiently.

  • Short-term goals: These could include saving for a vacation or buying a new gadget. These are typically achievable within a year.
  • Medium-term goals: Consider goals like purchasing a new car or saving for a down payment on a house. These might take a few years to accomplish.
  • Long-term goals: Focus on retirement savings or building a college fund for your children. These require a more extended time horizon and consistent effort.

By distinguishing between these different categories, you can allocate your savings in a way that supports immediate needs while still making progress towards larger aspirations. Remember, the key is to maintain a balance that allows you to enjoy life today while planning for tomorrow.
Explore Financing Options and Alternatives
Explore Financing Options and Alternatives

When planning for significant purchases, it’s essential to explore a variety of financing options to ensure you make a choice that aligns with your financial goals. Start by evaluating your eligibility for traditional loans from banks or credit unions, which often offer competitive interest rates. If you prefer more flexibility, consider personal loans or lines of credit that can provide the funds you need with more lenient terms.

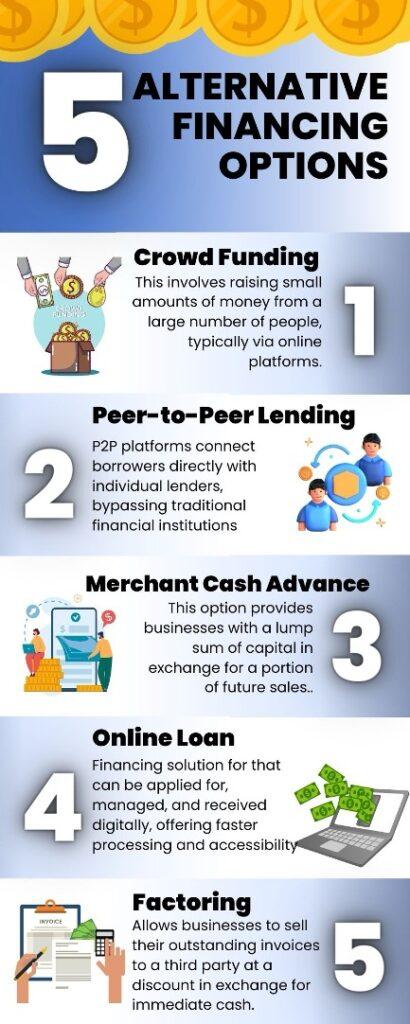
Beyond conventional loans, there are several alternative financing methods that might better suit your needs. These include:

  • Peer-to-Peer Lending: Online platforms that connect you directly with individual lenders, often with lower rates than traditional banks.
  • Credit Cards with 0% APR: Some credit cards offer introductory periods of no interest, allowing you to spread out payments without incurring extra costs.
  • Home Equity Loans: If you own property, tapping into your home’s equity can provide a substantial amount of money at lower interest rates.

Remember to thoroughly research and compare each option’s terms and fees to find the best fit for your financial situation, ensuring you maintain a healthy balance in your savings.

Implement a Strategic Savings Plan

Implement a Strategic Savings Plan

To effectively manage your finances and ensure you’re prepared for substantial expenditures, it’s essential to create a strategic savings plan. This approach not only helps in accumulating the necessary funds but also prevents the depletion of your existing savings. Here’s how to get started:

  • Set Clear Goals: Identify what you are saving for and determine the exact amount needed. Whether it’s a new car, a dream vacation, or a home renovation, having a precise target will keep you focused.
  • Create a Realistic Timeline: Decide when you plan to make the purchase. A realistic timeline will help you calculate how much you need to save each month, making it easier to incorporate into your budget.
  • Automate Your Savings: Set up automatic transfers to your savings account. This ensures that you consistently set aside money without the temptation to spend it elsewhere.
  • Track Your Progress: Regularly review your savings plan to ensure you are on track. Adjust as necessary to accommodate any changes in your financial situation.

By following these steps, you can confidently save for major purchases while maintaining a healthy financial cushion.


Hot this week

Family budgeting strategies for large families

Mastering family budgeting for large households involves prioritizing expenses, tracking spending, and leveraging bulk purchases. Set clear financial goals, involve all family members, and use apps to streamline and monitor the budget effectively.

How to create a family financial roadmap with clear milestones

Start by assessing your current financial situation and setting specific, achievable goals. Break these into short-term, medium-term, and long-term milestones. Regularly review and adjust your plan to stay on track and ensure family financial stability.

How to balance short term and long term financial goals as a family

Balancing short-term and long-term financial goals as a family requires clear communication, prioritizing needs, and setting realistic timelines. Start with a budget that allocates funds for immediate expenses while saving for future aspirations.

Pros and Cons of Debt Management Programs vs Debt Settlement

Debt management programs offer structured repayment plans to help manage debt, promoting financial discipline and often reducing interest rates. In contrast, debt settlement negotiates debt reductions but may harm credit scores and incur fees.

The Benefits of Debt Management Plans for Families

Debt Management Plans (DMPs) offer families a structured path to financial stability by consolidating debts into manageable payments. They reduce interest rates and monthly burdens, empowering families to regain control over their financial future.

Topics

Family budgeting strategies for large families

Mastering family budgeting for large households involves prioritizing expenses, tracking spending, and leveraging bulk purchases. Set clear financial goals, involve all family members, and use apps to streamline and monitor the budget effectively.

How to create a family financial roadmap with clear milestones

Start by assessing your current financial situation and setting specific, achievable goals. Break these into short-term, medium-term, and long-term milestones. Regularly review and adjust your plan to stay on track and ensure family financial stability.

How to balance short term and long term financial goals as a family

Balancing short-term and long-term financial goals as a family requires clear communication, prioritizing needs, and setting realistic timelines. Start with a budget that allocates funds for immediate expenses while saving for future aspirations.

Pros and Cons of Debt Management Programs vs Debt Settlement

Debt management programs offer structured repayment plans to help manage debt, promoting financial discipline and often reducing interest rates. In contrast, debt settlement negotiates debt reductions but may harm credit scores and incur fees.

The Benefits of Debt Management Plans for Families

Debt Management Plans (DMPs) offer families a structured path to financial stability by consolidating debts into manageable payments. They reduce interest rates and monthly burdens, empowering families to regain control over their financial future.

How to Plan for Rising Costs During Retirement

To tackle rising costs in retirement, start by creating a detailed budget that accounts for inflation. Diversify your investment portfolio to hedge against market volatility, and consider healthcare savings plans to cover medical expenses.

Top Tips for Saving Money on Groceries Every Month

Cut costs with a meal plan: Plan weekly meals to avoid impulse buys. Buy in bulk for non-perishables, and choose generic brands. Use loyalty programs and coupons for extra savings. Shop with a list to stay focused and on budget.

How to Set Financial Goals That Work for Your Family

Setting financial goals for your family begins with open communication. Identify priorities, set realistic timelines, and track progress regularly. By aligning goals with family values, you create a plan that’s both motivating and achievable.
spot_img

Related Articles

Popular Categories

spot_imgspot_img