
Managing high-interest debt can feel like navigating a stormy sea, but with the right strategies, you can chart a course toward financial stability and peace of mind. This article is designed to equip you with practical, effective techniques to tackle high-interest debt head-on. By understanding your financial landscape, prioritizing your obligations, and implementing targeted repayment methods, you can regain control over your finances and work towards a debt-free future. Whether you’re dealing with credit card balances, personal loans, or other high-interest obligations, these expert tips will empower you to manage your debt efficiently and confidently. Let’s embark on this journey to financial freedom together, armed with the knowledge and tools to succeed.
Understanding the Impact of High Interest Debt
High interest debt can significantly affect your financial well-being, often more than people initially realize. When you have debt with high interest rates, a large portion of your payments goes toward interest rather than reducing the principal balance. This can make it feel like you’re running on a financial treadmill, where you pay and pay but never seem to get ahead. Understanding the implications is crucial for developing an effective management strategy. Consider the following impacts:
- Increased Financial Burden: High interest rates can lead to exponentially growing debt, which can quickly become overwhelming.
- Limited Cash Flow: More of your income is tied up in debt payments, leaving less for savings and other expenses.
- Credit Score Damage: Struggling to keep up with payments can negatively impact your credit score, affecting future borrowing opportunities.
- Emotional Stress: The constant pressure of high debt can lead to anxiety and stress, impacting overall well-being.
By recognizing these impacts, you can prioritize actions that minimize the negative effects, such as consolidating debt or negotiating lower interest rates. Taking proactive steps can help you regain control over your finances and work towards a debt-free future.
Strategizing Debt Repayment with Proven Methods
When tackling high interest debt, it’s crucial to employ methods that have stood the test of time. Start by embracing the Debt Avalanche Method, which focuses on paying off debts with the highest interest rates first. This approach minimizes the amount of interest you pay over time, allowing you to gain financial momentum faster. Alternatively, consider the Debt Snowball Method, which emphasizes paying off the smallest debts first. This strategy can be psychologically rewarding, providing quick wins that keep you motivated throughout the repayment process.
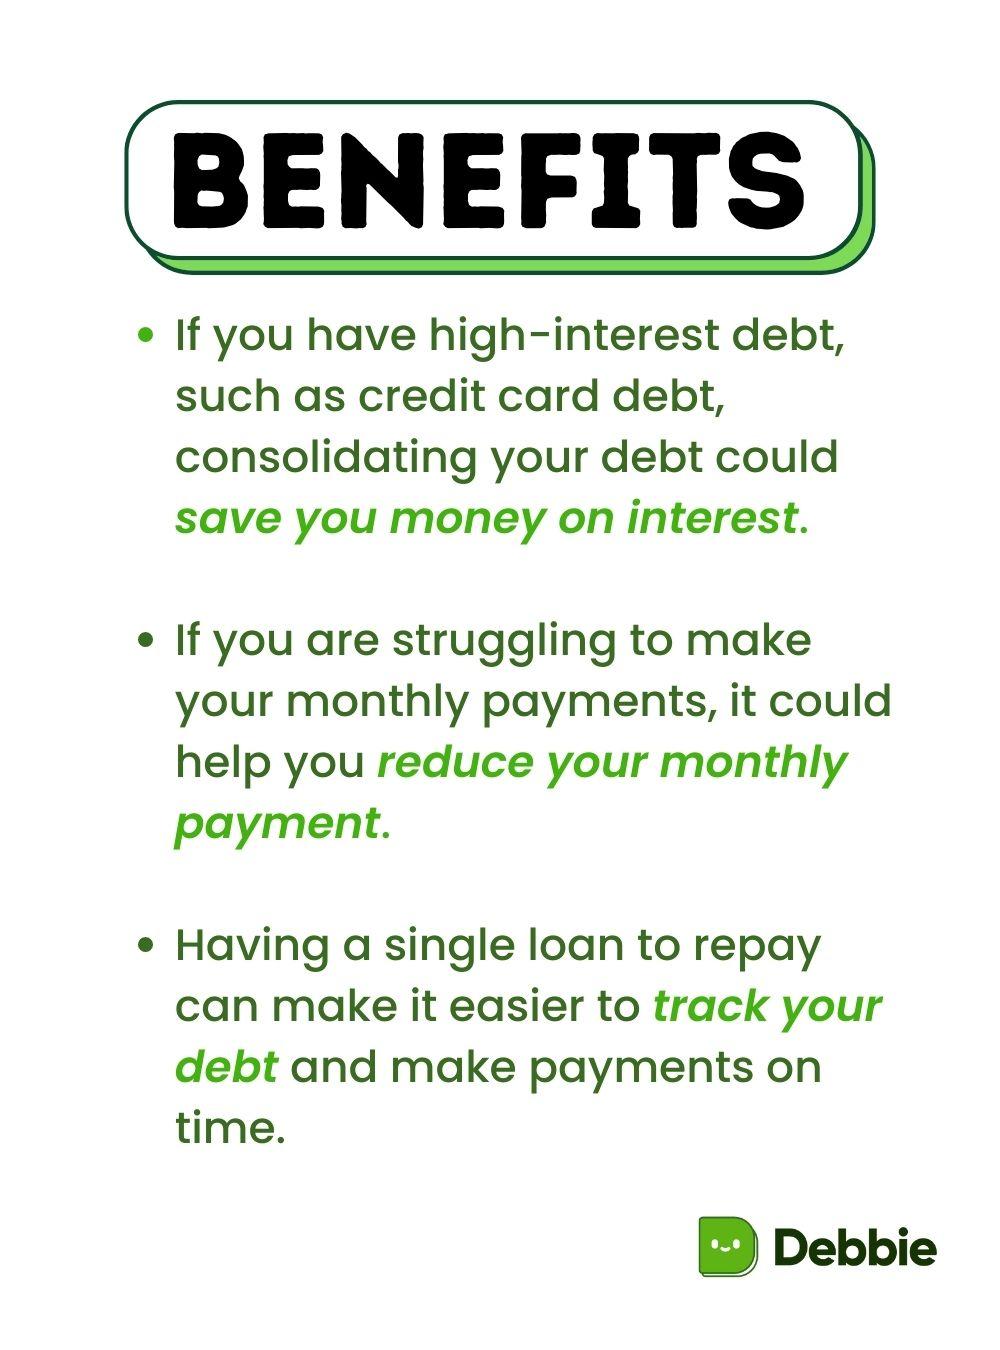
- Consolidate Debt: Merging multiple debts into a single payment can simplify your financial obligations and often comes with a lower interest rate.
- Negotiate Interest Rates: Don’t hesitate to contact your creditors to negotiate lower interest rates. A simple call can sometimes lead to significant savings.
- Automate Payments: Set up automatic payments to ensure you never miss a due date, avoiding late fees and additional interest.
- Increase Income Streams: Consider side gigs or freelance opportunities to boost your income, channeling the extra funds directly towards debt repayment.
Leveraging Financial Tools to Lower Interest Rates
In the realm of personal finance, the strategic use of financial tools can be a game-changer for reducing the burden of high-interest debt. One effective approach is to explore balance transfer credit cards, which often offer a low or even 0% introductory interest rate for a specific period. This allows you to consolidate high-interest debts and focus on paying down the principal amount more aggressively during the promotional period. However, it’s crucial to be mindful of transfer fees and the duration of the introductory rate to ensure that this option provides a net benefit.
Another powerful tool is debt consolidation loans, which can streamline multiple debts into a single loan with a potentially lower interest rate. This not only simplifies monthly payments but can also reduce the overall interest paid over time. Consider the following financial instruments:
- Home Equity Loans: Tap into the equity of your home to secure a lower interest rate.
- Personal Loans: Unsecured loans with competitive rates, often lower than credit cards.
- Credit Union Loans: Often offer lower rates and more flexible terms compared to traditional banks.
By understanding and utilizing these tools effectively, you can take significant strides toward minimizing interest expenses and managing your debt more efficiently.
Building Long-term Financial Habits for Sustained Debt Management
Establishing enduring financial habits is crucial for managing high-interest debt effectively. One of the most effective strategies is creating a realistic budget that prioritizes debt repayment. Begin by identifying essential expenses and cutting down on non-essentials. Allocate a specific portion of your income towards debt payments every month. Consistency is key; even small, regular payments can significantly reduce debt over time.
Another vital habit is maintaining a debt repayment plan. Keep track of all debts, interest rates, and due dates to avoid late fees and additional charges. Consider consolidating debts or negotiating with creditors for better terms. Moreover, building an emergency fund can prevent the need for further borrowing in unexpected situations. Remember, it’s not just about paying off debt but also about cultivating a financial mindset that promotes long-term stability. Adopting these habits can transform your approach to debt management, ensuring you remain on a path to financial health.
- Develop a realistic budget and stick to it.
- Prioritize debt payments in your financial planning.
- Track all debts and payment schedules diligently.
- Consider debt consolidation for better interest rates.
- Build an emergency fund to avoid future debt.