
In an ever-evolving financial landscape, securing a prosperous future for your family requires not only strategic foresight but also a measured approach to investment. While high-risk ventures often promise substantial returns, they are accompanied by significant uncertainty and potential loss. For families seeking to build wealth with stability and peace of mind, low-risk investments present a viable pathway. This article delves into the art of cultivating financial growth through prudent, low-risk investment strategies. By analyzing market trends, assessing reliable investment vehicles, and understanding the principles of risk management, we aim to equip you with the knowledge to make informed decisions that safeguard and enhance your family’s financial legacy. Whether you are a seasoned investor or a newcomer to the financial world, this guide offers insights and practical advice to help you achieve steady, long-term wealth accumulation with confidence.
Understanding Low Risk Investment Options
When it comes to securing a financial future for your family, opting for low-risk investment options can be a wise strategy. These investment avenues typically offer modest returns but are less volatile compared to their high-risk counterparts. Government bonds are a popular choice, as they are backed by the full faith and credit of the issuing country, ensuring reliability and a steady income stream. Another stable option is fixed deposits, which guarantee a fixed rate of interest over a specified period, providing predictability and security.
For those seeking to diversify, money market funds present a viable option. These funds invest in short-term debt securities and offer liquidity with minimal risk. Additionally, index funds can be considered, as they track market indices and spread risk across a wide array of stocks, making them less susceptible to market fluctuations. Consider these low-risk options to build a solid financial foundation for your family while minimizing exposure to market uncertainties.
Strategies for Diversifying Family Wealth
Building a resilient financial portfolio for your family requires a strategic approach to minimizing risks while maximizing potential returns. One effective method is to incorporate a variety of asset classes into your investment plan. Diversification is key to safeguarding wealth against market volatility. Consider including the following in your portfolio:
- Index Funds and ETFs: These provide broad market exposure, reducing the impact of poor performance from individual stocks.
- Real Estate Investment Trusts (REITs): Offering regular income and potential for appreciation, REITs allow investment in real estate without the complexities of direct property ownership.
- Bonds: A stable income source, bonds can counterbalance the volatility of equities, providing security during economic downturns.
- Dividend Stocks: Investing in companies with a strong track record of paying dividends can offer both growth and income.
In addition to diversifying asset types, consider geographical diversification to protect against localized economic disruptions. By investing in international markets, you can tap into growth opportunities that may not be available domestically, further enhancing your family’s financial stability.
Maximizing Returns with Minimal Risk
Building wealth while keeping risks at bay requires a strategic approach that balances growth potential with financial security. One effective method is to diversify your investment portfolio across a variety of low-risk assets. Consider integrating the following options into your financial strategy:
- High-Yield Savings Accounts: These accounts offer a secure way to grow your funds with interest rates higher than traditional savings accounts, providing steady returns with minimal risk.
- Government Bonds: Often considered safe investments, these bonds offer fixed interest rates and are backed by the full faith and credit of the issuing government.
- Dividend-Paying Stocks: While stocks typically carry higher risk, focusing on established companies that consistently pay dividends can offer a reliable income stream and potential for capital appreciation.
- Real Estate Investment Trusts (REITs): REITs allow you to invest in real estate without the complexities of property management, often providing stable dividends and portfolio diversification.
By carefully selecting a mix of these low-risk investment vehicles, you can create a robust financial foundation that prioritizes the preservation of capital while still achieving meaningful growth over time.
Implementing a Long-term Wealth Building Plan
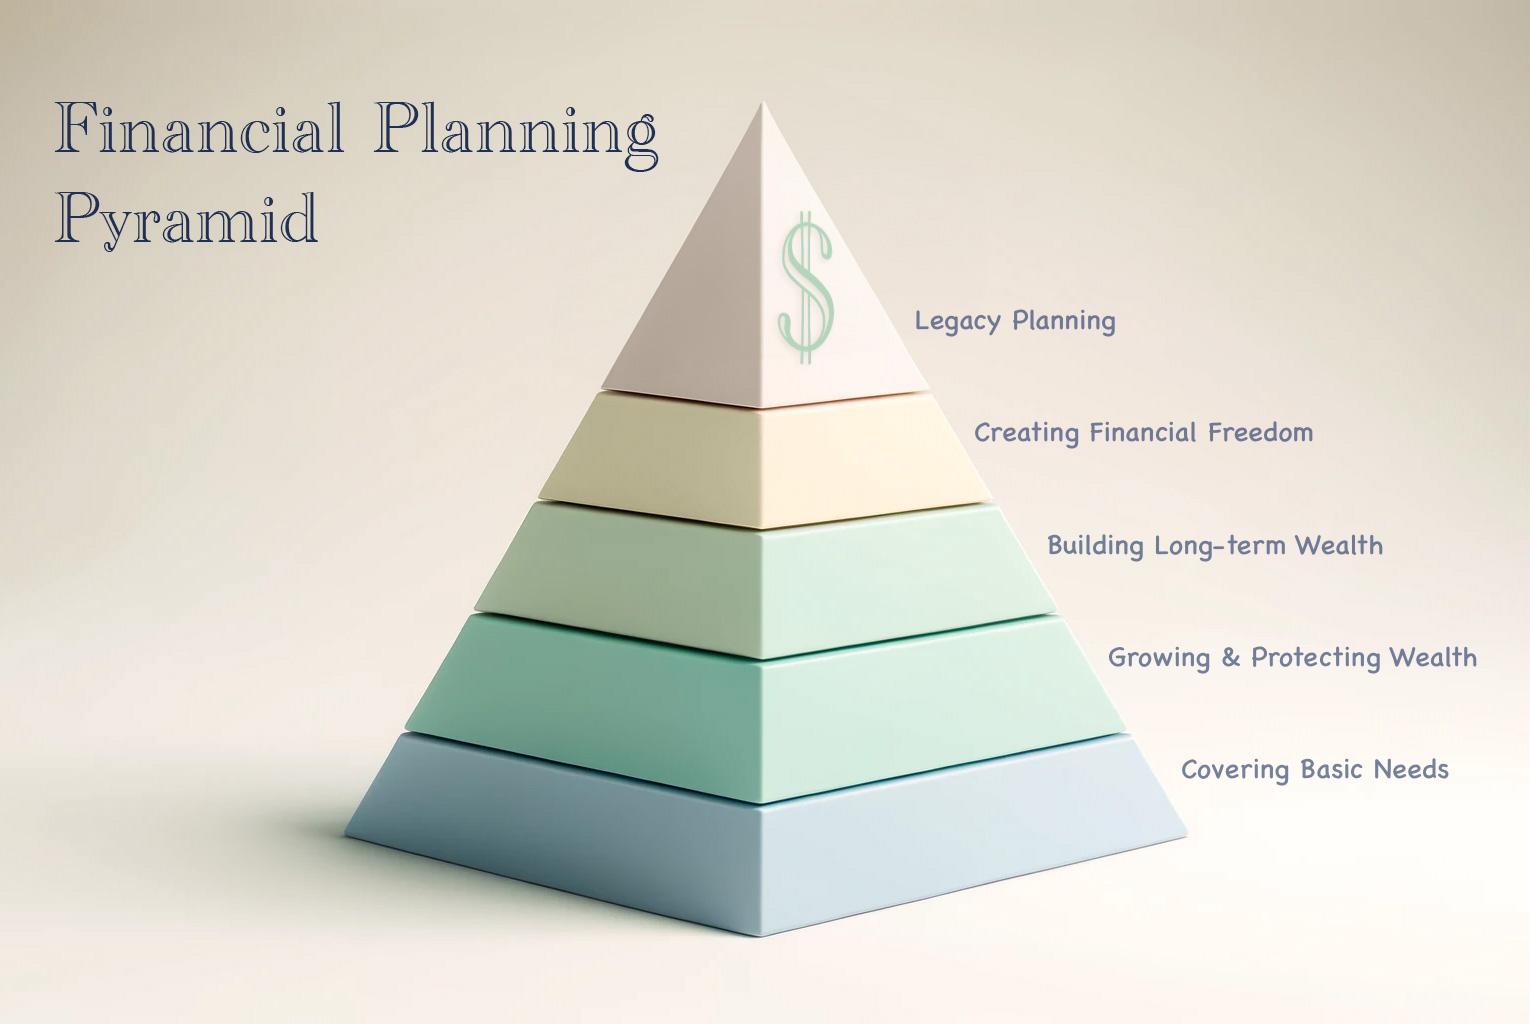
Building a wealth plan that stands the test of time involves a careful selection of low-risk investments, ensuring that the family’s financial future remains secure. Diversification is key, as it spreads potential risks across various asset classes. Consider integrating these elements into your strategy:
- High-quality bonds: These provide a stable income stream and are less volatile compared to stocks, making them a solid foundation for any wealth-building plan.
- Dividend-paying stocks: While they carry more risk than bonds, selecting companies with a strong history of paying dividends can offer both income and potential growth.
- Real estate investment trusts (REITs): REITs offer exposure to real estate markets with the added benefit of liquidity, allowing for a diversified portfolio without the need to manage physical properties.
- Index funds: By investing in index funds, you can achieve broad market exposure at a low cost, which is ideal for long-term growth with minimal management.
Regularly reviewing and adjusting your portfolio ensures that it remains aligned with your family’s evolving goals and risk tolerance. Staying informed and flexible allows you to navigate the complexities of financial markets with confidence, ultimately fostering a sustainable path to wealth accumulation.