
Navigating the labyrinth of state and federal aid for college can be daunting, yet understanding how to effectively maximize these resources is crucial for reducing the financial burden of higher education. With the rising costs of tuition and the increasing importance of a college degree, it’s more important than ever to make the most of available financial aid opportunities. This guide will equip you with the essential strategies and insights needed to unlock the full potential of state and federal aid, empowering you to make informed decisions and secure the funding necessary to achieve your academic goals. Whether you’re a prospective student or a parent planning for your child’s future, this article will provide you with the confidence and knowledge to navigate the financial aid landscape with ease and success.
Understanding Eligibility Requirements for Maximum Aid
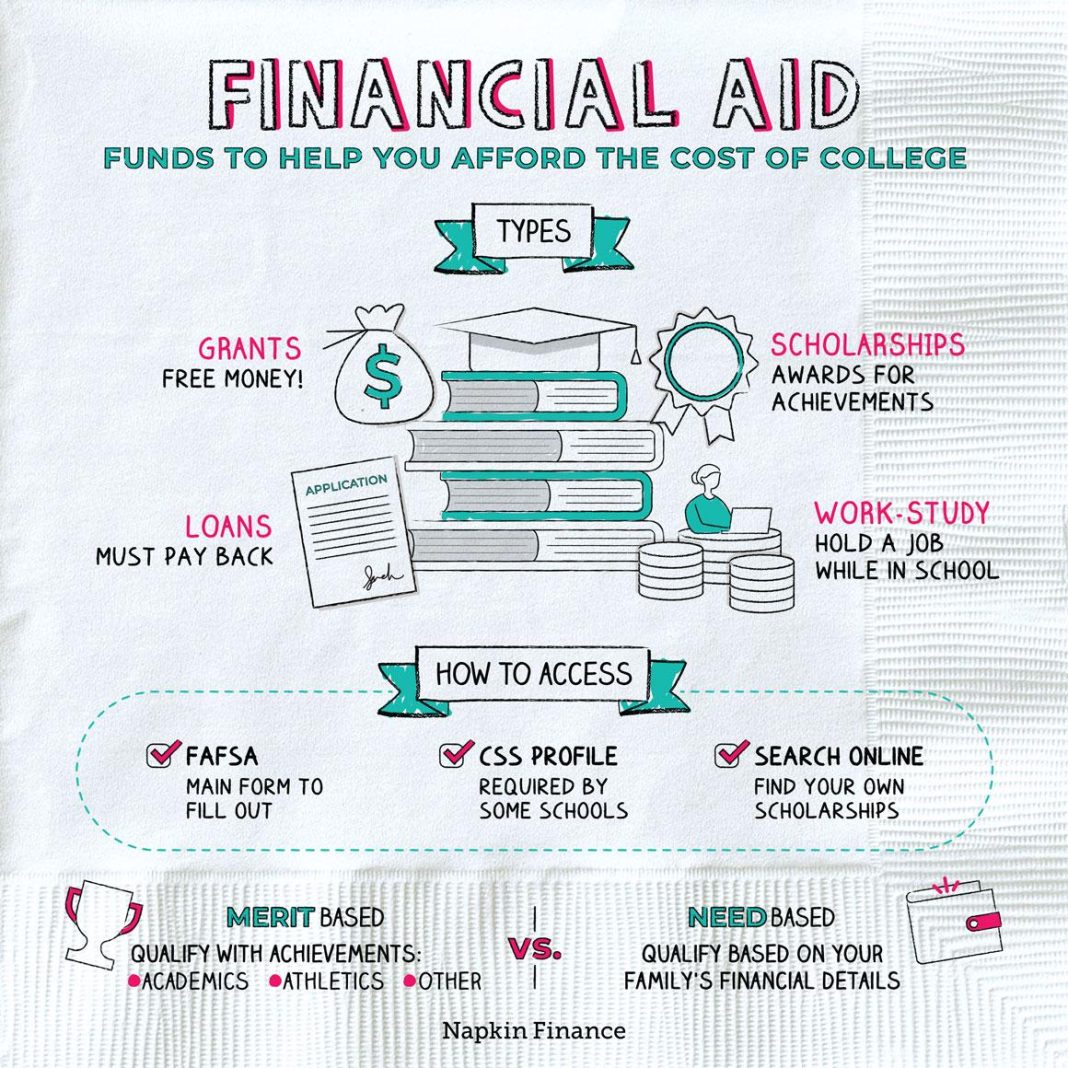
To secure the highest amount of state and federal aid, it’s essential to first comprehend the specific eligibility criteria set by each program. Federal aid, such as the Pell Grant, typically requires students to demonstrate financial need, maintain satisfactory academic progress, and be enrolled in an eligible degree or certificate program. Additionally, applicants must be U.S. citizens or eligible non-citizens and possess a valid Social Security number. State aid requirements can vary significantly from one state to another, often including residency criteria, enrollment in an in-state institution, and sometimes even maintaining a certain GPA. It’s crucial to thoroughly research the specific guidelines applicable to your state to avoid missing out on potential opportunities.
- Complete the FAFSA: This is the gateway to accessing most federal and state aid. Ensure all information is accurate and submitted before the deadline.
- Verify State-Specific Requirements: Each state may have unique programs with different criteria. Consult your state’s education department website for detailed information.
- Maintain Eligibility: Once aid is awarded, continue to meet all academic and enrollment requirements to avoid losing financial support.
Strategically Timing Your FAFSA and CSS Profile Submissions
Submitting your FAFSA and CSS Profile at the right time can significantly boost your chances of securing maximum state and federal aid. The FAFSA opens on October 1st each year, and while federal deadlines are more lenient, many states and colleges have their own early deadlines. To ensure you’re first in line for limited funds, aim to complete your FAFSA as soon as possible after October 1st. This not only secures your eligibility for federal grants and loans but also positions you favorably for state-specific aid that may be distributed on a first-come, first-served basis.
- Check State Deadlines: Each state has its own deadline for state aid. Prioritize these dates and submit well in advance.
- Be Aware of Priority Deadlines: Colleges often have priority deadlines for institutional aid. Submitting your FAFSA and CSS Profile before these dates can make a big difference.
- Prepare Early: Gather necessary documents such as tax returns and financial statements ahead of time to avoid last-minute stress.
Meanwhile, the CSS Profile, required by many private colleges for institutional aid, also opens on October 1st. Unlike the FAFSA, which is free to submit, the CSS Profile requires a fee, but fee waivers are available for eligible students. Prioritize schools with the earliest deadlines to ensure you’re considered for the maximum possible aid. By strategically timing your submissions and staying organized, you can maximize your financial aid package and reduce your college expenses significantly.
Leveraging State-Specific Grants and Scholarships
Every state offers a variety of grants and scholarships designed to support local students in pursuing higher education. These state-specific financial aids can be a game-changer in minimizing college expenses. Begin by researching the Higher Education Agency of your state, as they often provide detailed information on available opportunities and eligibility criteria. Make sure to check the application deadlines and required documents well in advance, as these vary from state to state.
- Merit-Based Scholarships: Many states offer scholarships based on academic achievements, so maintaining a strong GPA and engaging in extracurricular activities can increase your chances.
- Need-Based Grants: If your family’s financial situation qualifies, these grants can significantly reduce your tuition costs.
- Field-Specific Programs: Some states offer scholarships for students pursuing degrees in high-demand fields like STEM, education, or healthcare.
- Community College Transfer Grants: For students planning to transfer from a community college to a four-year institution, certain states provide additional financial support.
By strategically leveraging these state-specific resources, you can complement federal aid and maximize your overall financial package, making college more affordable and accessible.
Utilizing Tax Credits and Deductions to Supplement Financial Aid
When planning for college expenses, leveraging tax credits and deductions can significantly enhance your financial aid package. By understanding and utilizing these tools, families can effectively reduce their out-of-pocket costs. The American Opportunity Tax Credit (AOTC) and the Lifetime Learning Credit (LLC) are two powerful resources. The AOTC offers up to $2,500 per eligible student, focusing on the first four years of higher education. Meanwhile, the LLC provides up to $2,000 per tax return for those enrolled in eligible educational institutions. Both credits are designed to alleviate the financial burden of tuition and related expenses.
- American Opportunity Tax Credit (AOTC): Covers tuition, required fees, and course materials for the first four years of post-secondary education.
- Lifetime Learning Credit (LLC): Ideal for part-time students or those pursuing higher education beyond the first four years, including graduate school.
In addition to credits, families should explore tax deductions such as the Student Loan Interest Deduction, which allows you to deduct up to $2,500 of interest paid on student loans. It’s crucial to stay informed about eligibility criteria and income thresholds, as these can affect the availability and amount of aid. Coordinating these tax benefits with other financial aid elements, like scholarships and grants, ensures a comprehensive strategy to minimize college costs.