
In today’s rapidly evolving financial landscape, securing a stable future for one’s family has never been more crucial. As the complexities of global markets deepen and the unpredictability of economic shifts become the norm, families must prioritize not just saving, but strategically investing their hard-earned money. This article delves into the top investment accounts that every family should consider, providing a comprehensive analysis of their benefits, potential risks, and long-term advantages. By exploring these investment vehicles, families can make informed decisions that align with their financial goals, ensuring growth, security, and peace of mind for generations to come. Whether you’re a seasoned investor or just beginning to explore the world of finance, understanding these options is a vital step towards building a robust financial foundation.
Understanding Investment Account Types for Families
When planning for your family’s financial future, choosing the right investment accounts is crucial. There are various options designed to meet diverse needs, each with its own benefits and considerations. Understanding these options can empower you to make informed decisions that align with your family’s goals and financial situation.
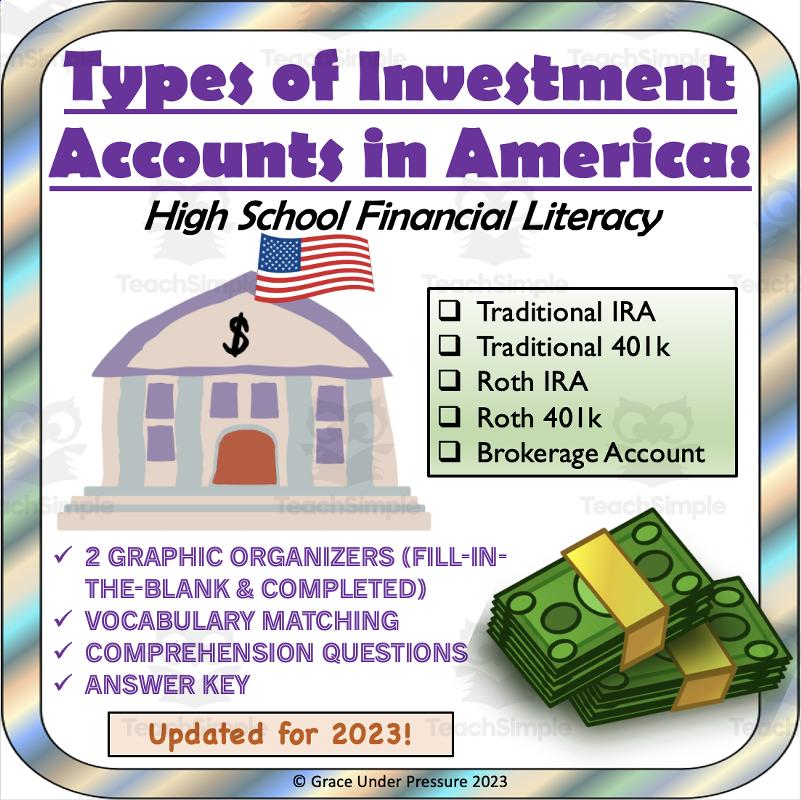
- Individual Retirement Accounts (IRAs): These are essential for long-term savings, offering tax advantages that can significantly impact your family’s future. Consider both Traditional and Roth IRAs, each with distinct tax implications.
- 529 College Savings Plans: Ideal for families prioritizing education, these accounts provide tax-free growth and withdrawals for qualified educational expenses.
- Brokerage Accounts: While not tax-advantaged, these accounts offer flexibility and access to a broad range of investment options, allowing for both short-term and long-term strategies.
Assessing your family’s unique financial situation will help determine which accounts offer the most strategic benefits. Whether you’re focusing on retirement, education, or general wealth building, aligning your choices with your goals is key to securing a prosperous future.
Key Features of Family-Friendly Investment Accounts
When evaluating investment accounts tailored for families, several distinctive features stand out, ensuring that both short-term needs and long-term goals are met. Flexibility is a key aspect, allowing families to adjust contributions and withdrawals as life circumstances evolve. This ensures that families can maintain a dynamic approach to saving and investing without facing prohibitive penalties.
Additionally, family-friendly investment accounts often come with educational resources that help both parents and children understand financial planning. These resources might include interactive tools, webinars, and even personalized advice from financial advisors. Moreover, many of these accounts offer tax advantages, such as tax-deferred growth or tax-free withdrawals for qualified expenses, which can significantly enhance the family’s overall financial strategy. Emphasizing these features can empower families to make informed decisions that align with their unique financial goals.
- Flexibility in contributions and withdrawals
- Access to educational resources
- Potential tax advantages
Maximizing Returns with Family Investment Strategies
Families looking to bolster their financial future can benefit significantly from strategic investment accounts tailored to their unique needs. By leveraging a mix of diverse options, families can ensure a balanced and robust portfolio. Here are some key investment accounts to consider:
- 529 College Savings Plans: These tax-advantaged accounts are specifically designed to help families save for future educational expenses. Contributions grow tax-free, and withdrawals for qualified education costs are not taxed, making them a powerful tool for securing a child’s educational future.
- Roth IRAs: Ideal for families wanting to secure their retirement, Roth IRAs offer tax-free growth and withdrawals. Since contributions can be withdrawn at any time without penalties, they also provide a flexible option for unforeseen family expenses.
- Health Savings Accounts (HSAs): An excellent choice for families with high-deductible health plans, HSAs offer triple tax benefits: contributions are tax-deductible, growth is tax-free, and withdrawals for qualified medical expenses are tax-exempt. This makes HSAs a strategic addition to any family’s investment plan.
By integrating these accounts into their financial strategy, families can not only maximize their returns but also safeguard their financial well-being against life’s uncertainties.
Expert Recommendations for Family Investment Portfolios
Crafting a robust family investment portfolio requires a strategic blend of account types that cater to both short-term needs and long-term goals. Financial experts emphasize the importance of diversification, recommending families to consider a variety of account options to maximize growth potential while minimizing risk. Here are some top picks:
- 529 College Savings Plans: These accounts offer tax advantages and are specifically designed for education expenses, making them a smart choice for families planning for their children’s future educational needs.
- Roth IRAs: Known for their tax-free growth and withdrawal benefits, Roth IRAs are ideal for long-term savings and can be a versatile tool in a family’s retirement planning strategy.
- Health Savings Accounts (HSAs): Offering triple tax advantages, HSAs are not only a great way to cover current medical expenses but also serve as a supplementary retirement savings account.
- Brokerage Accounts: For families looking to invest beyond retirement accounts, brokerage accounts provide the flexibility to invest in a wide range of assets, including stocks, bonds, and mutual funds.
By incorporating these accounts into their financial strategy, families can build a resilient investment portfolio that supports both immediate and future financial objectives.