
Creating a retirement budget that stands the test of time is a crucial step towards ensuring a secure and fulfilling post-work life. As you transition from a regular paycheck to drawing from your savings, having a well-structured financial plan becomes essential to maintaining your desired lifestyle and achieving peace of mind. In this guide, we will walk you through the process of crafting a retirement budget that not only meets your immediate needs but also adapts to future changes. With confidence and clarity, we will explore strategies to accurately assess your expenses, optimize your income sources, and safeguard your financial well-being against unforeseen challenges. By the end of this article, you’ll be equipped with the knowledge and tools to create a sustainable budget that supports your retirement dreams.
Identifying Essential and Discretionary Expenses for a Balanced Budget
In crafting a retirement budget that stands the test of time, it’s crucial to distinguish between essential and discretionary expenses. Essential expenses are those non-negotiable costs that ensure your basic needs are met, such as:
- Housing: Mortgage or rent, property taxes, and maintenance costs.
- Utilities: Electricity, water, gas, and internet services.
- Healthcare: Insurance premiums, medications, and regular medical check-ups.
- Groceries: Basic food and household supplies.
- Transportation: Car payments, fuel, and maintenance or public transport costs.
On the other hand, discretionary expenses are those that can be adjusted or eliminated based on your financial situation. These might include:
- Dining out: Restaurants and take-out meals.
- Entertainment: Movies, concerts, and recreational activities.
- Travel: Vacations and trips.
- Hobbies: Leisure activities and personal interests.
- Gifts and Donations: Charitable contributions and presents for family and friends.
By clearly identifying and separating these two categories, you can prioritize your spending, ensuring that essential needs are covered while still enjoying the flexibility to indulge in life’s pleasures when your budget allows.
Strategies for Maximizing Income Sources in Retirement
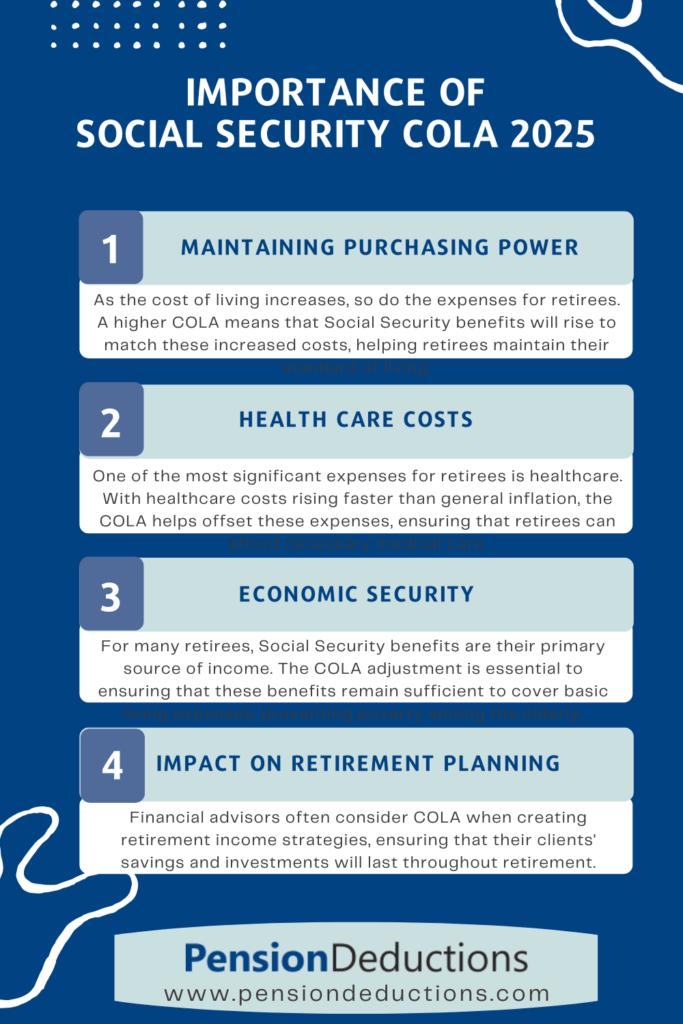
To effectively enhance your income streams during retirement, diversification is key. Begin by evaluating your current assets and identifying opportunities to generate additional revenue. Consider renting out a portion of your home or investing in dividend-paying stocks. It’s also wise to explore part-time work or consulting roles in your field of expertise, which not only supplements income but keeps you engaged and active. Additionally, look into creating passive income through options like peer-to-peer lending or real estate investment trusts (REITs).
- Utilize Tax-Advantaged Accounts: Leverage accounts like IRAs and 401(k)s to minimize tax liabilities while maximizing withdrawals.
- Optimize Social Security Benefits: Delay claiming benefits until full retirement age or later to increase your monthly payouts.
- Consider Annuities: These can provide a steady income stream, ensuring financial stability.
- Capitalize on Skills and Hobbies: Transform hobbies into profitable ventures, whether it’s crafting, writing, or teaching.
By implementing a combination of these strategies, you can create a robust and resilient financial plan that not only meets your needs but also adapts to the evolving economic landscape.
Anticipating Healthcare Costs and Inflation in Your Budget Plan
When planning for retirement, it’s crucial to incorporate the potential impacts of healthcare expenses and inflation into your budget strategy. Healthcare costs are notoriously unpredictable and tend to rise faster than general inflation rates. Therefore, a proactive approach is essential. Consider setting aside a specific portion of your savings to cover these future expenses. Health Savings Accounts (HSAs) and long-term care insurance are excellent tools to help mitigate these costs, providing both tax advantages and peace of mind.
- Estimate Future Healthcare Costs: Utilize available online calculators to project healthcare expenses based on your age, health status, and retirement location.
- Adjust for Inflation: Factor in an average inflation rate of 3-4% when estimating your future living expenses. This will help maintain your purchasing power over the years.
- Regularly Review and Adjust: Your budget should be a living document. Schedule regular reviews to adjust for any changes in your health status or inflation trends.
By taking these steps, you can build a robust retirement budget that anticipates the financial demands of healthcare and inflation, ensuring your savings last throughout your retirement years.
Adjusting Your Budget Over Time to Ensure Long-Term Sustainability
As you navigate the years of retirement, it’s crucial to periodically reassess your financial plan to maintain its longevity. Life circumstances and market conditions can change, so adapting your budget is a key strategy for ensuring financial security. Here are some considerations to keep your retirement plan on track:
- Review and Adjust: At least annually, take a close look at your expenses and income. Has there been a significant change in your cost of living, or have your spending habits evolved? Make adjustments where necessary to align with your financial goals.
- Factor in Inflation: Don’t overlook the impact of inflation on your purchasing power. It’s wise to incorporate a modest annual increase in your budget to accommodate rising prices.
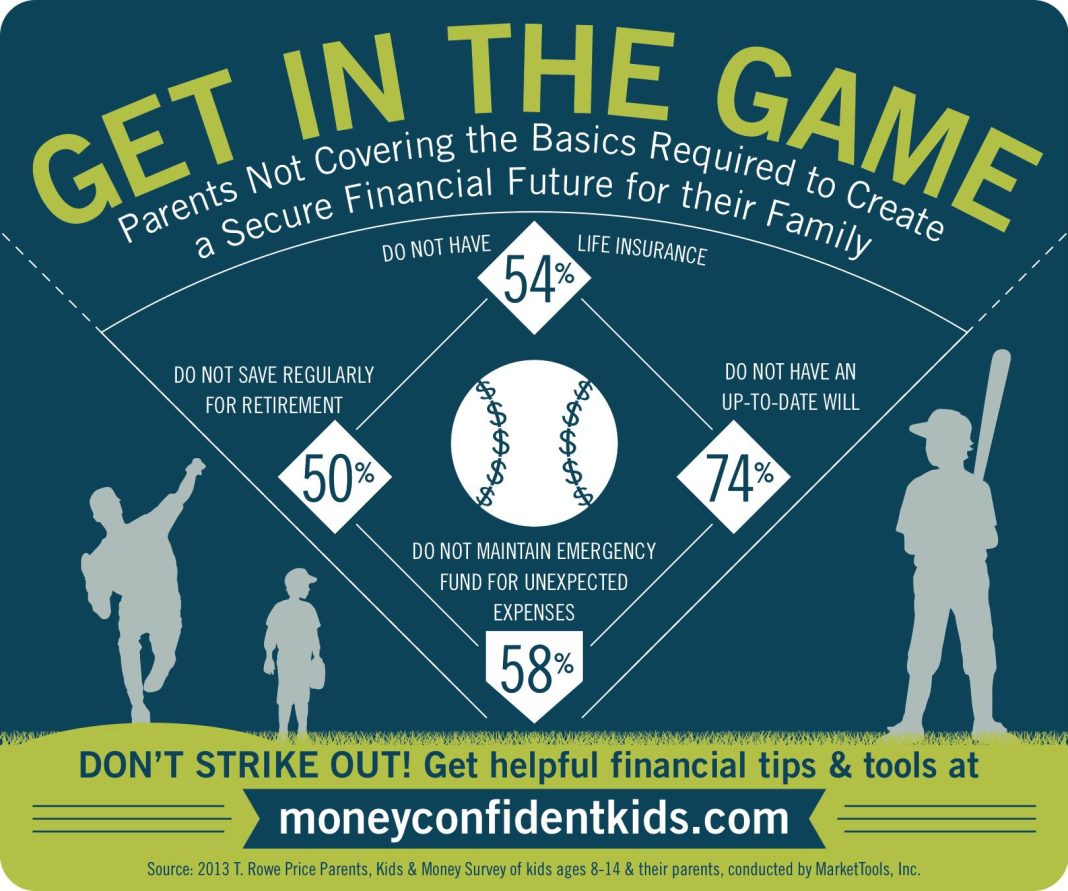
- Emergency Fund: Ensure you have a robust emergency fund in place. This will cushion you against unexpected expenses without derailing your financial plan.
- Reevaluate Investment Strategy: Consider shifting your investment portfolio as you age. Balancing growth and security is essential to protect your nest egg while still allowing for some potential growth.
By regularly evaluating your budget and making thoughtful adjustments, you can enjoy peace of mind knowing that your financial resources are being managed wisely for the long haul.