
Building a college fund is a crucial step in ensuring a bright future for your child, but it often feels like a daunting task, especially when you’re trying to balance your current savings goals. The good news is that it’s entirely possible to prepare for your child’s education without compromising your financial security. In this guide, we’ll explore practical strategies and smart financial planning techniques to help you build a robust college fund while keeping your savings intact. With confidence and clarity, we’ll navigate the path to achieving your educational savings goals, empowering you to make informed decisions that benefit both your family and your financial well-being. Whether you’re just starting out or looking to optimize your current plan, this article will equip you with the tools you need to succeed.
Maximize Your Savings Potential with Strategic Budgeting
Strategic budgeting is the cornerstone of building a robust college fund without compromising your existing savings. To start, it’s crucial to assess your current financial landscape. Analyze your income streams and expenses meticulously. Identify areas where you can trim unnecessary costs and redirect those funds into a dedicated college savings account. Creating a budget tailored to this goal can make a significant difference. Begin by setting realistic savings goals and timelines. This will help you stay focused and motivated, even when financial pressures arise.
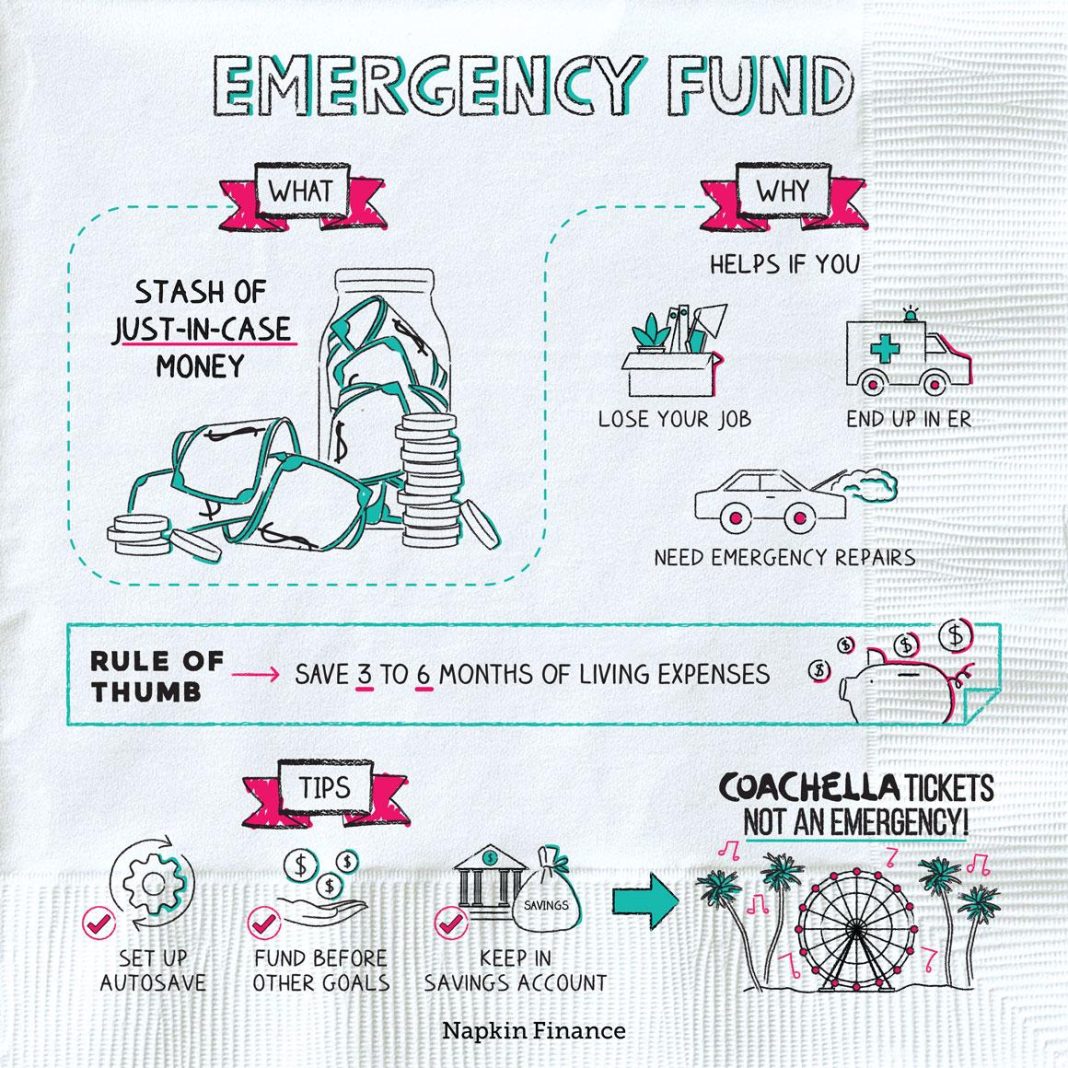
- Automate Your Savings: Set up automatic transfers to your college fund. This ensures consistency and minimizes the temptation to spend the money elsewhere.
- Utilize Tax-Advantaged Accounts: Explore options like 529 plans or Coverdell ESAs, which offer tax benefits and can boost your savings over time.
- Review and Adjust: Regularly revisit your budget to accommodate changes in income or expenses. This flexibility will help maintain your savings trajectory.
By incorporating these strategies, you can effectively grow your college fund while safeguarding your savings. It’s about making deliberate choices that align with your long-term financial goals.
Leverage Tax-Advantaged Accounts for College Savings
Maximizing your college savings potential often means making the most of tax-advantaged accounts. These accounts offer unique benefits that can significantly enhance your savings strategy. 529 Plans are among the most popular options, allowing your contributions to grow tax-free, and withdrawals are also tax-free when used for qualified education expenses. Additionally, consider Coverdell Education Savings Accounts (ESAs), which offer similar tax advantages and can be used for a broader range of educational expenses, including K-12 costs.
- 529 Plans: Flexible state-sponsored plans with high contribution limits.
- Coverdell ESAs: Offer investment flexibility and can be used for various educational expenses.
- Roth IRAs: Though primarily for retirement, they can be tapped into for education without penalty under certain conditions.
Each of these accounts has its own set of rules and benefits, so it’s crucial to evaluate which aligns best with your financial goals and timeline. By strategically utilizing these accounts, you can build a robust college fund without derailing your overall savings plan.
Diversify Investment Options to Secure Growth
To ensure robust growth in your college fund, consider diversifying your investment portfolio. This approach not only mitigates risks but also maximizes potential returns over time. Here are some investment options to explore:
- 529 College Savings Plans: These are tax-advantaged accounts specifically designed for education expenses. With a variety of investment choices, they offer flexibility and potential growth.
- Exchange-Traded Funds (ETFs): ETFs provide exposure to a wide array of assets, including stocks and bonds, with lower fees compared to mutual funds. Their diversity can help balance risk and reward.
- Dividend Stocks: Investing in companies that regularly pay dividends can generate a steady income stream, which can be reinvested to boost your college fund.
- Government Bonds: Known for their stability, these bonds can be a safer component of your investment strategy, offering guaranteed returns over a set period.
- Real Estate Investment Trusts (REITs): For those looking to diversify beyond traditional stocks and bonds, REITs offer exposure to the real estate market without the need to directly own property.
By strategically allocating your resources across these diverse options, you can build a college fund that grows steadily while safeguarding your overall savings.
Utilize Scholarships and Grants to Supplement Your Fund
One of the most effective ways to enhance your college fund without dipping into your savings is by taking advantage of scholarships and grants. These financial aids are often overlooked but can significantly reduce the burden of tuition fees. Unlike loans, scholarships and grants do not need to be repaid, making them an excellent resource for cost-effective education funding. Here’s how you can maximize these opportunities:
- Research Extensively: Start by exploring various scholarship databases and websites that compile lists of available scholarships. Be sure to check both national and local opportunities, as well as those specific to your field of study or demographic.
- Apply Early and Often: Deadlines can be tight, and competition is fierce. Applying early not only shows initiative but also ensures you don’t miss out on any potential funds.
- Tailor Your Applications: Customize your applications to highlight how you meet the specific criteria of each scholarship or grant. A personalized approach can make your application stand out.
- Utilize School Resources: Many educational institutions have dedicated financial aid offices that can provide information on available scholarships and grants. Don’t hesitate to reach out for guidance and support.
By strategically applying for scholarships and grants, you can significantly bolster your college fund, ensuring a smoother financial journey through your academic pursuits.