
Balancing debt repayment and savings is a financial tightrope that many individuals find challenging to navigate. Yet, mastering this balance is crucial for achieving long-term financial stability and peace of mind. This article will guide you through effective goal-setting strategies designed to help you manage debt while building a robust savings plan. By employing these strategies, you can create a personalized financial roadmap that aligns with your unique circumstances and aspirations. With a confident approach and a clear plan, you can take control of your financial future, ensuring that your debt decreases while your savings grow. Dive in to discover how you can transform your financial habits and set yourself on the path to prosperity.
Prioritize and Analyze Your Financial Situation
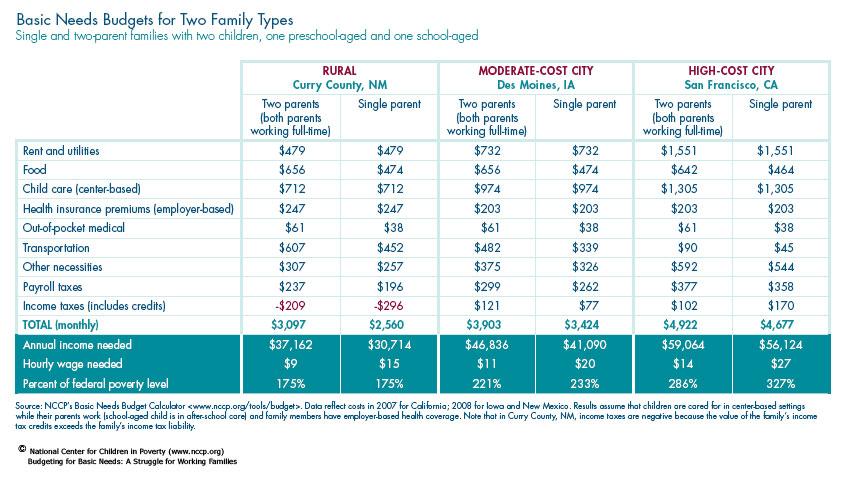
In the journey to achieve a harmonious balance between paying off debt and building savings, it’s crucial to first gain a clear understanding of your current financial standing. Begin by evaluating your income, expenses, and outstanding debts. Create a detailed budget that outlines all your financial commitments and categorize them into essentials and non-essentials. This will help you identify areas where you can cut back and redirect funds towards your financial goals.
Next, assess your debts to determine which ones should be prioritized based on interest rates and terms. High-interest debts, like credit cards, typically require immediate attention. Meanwhile, consider setting aside a small, manageable amount for savings each month, even if it’s modest. This dual approach ensures that while you’re reducing debt, you’re also fostering a savings habit. Use tools like spreadsheets or budgeting apps to keep track of your progress. By regularly reviewing your financial situation, you can make informed decisions and adjust your strategies as needed.
Establish Clear and Achievable Financial Goals
Setting financial objectives that are both clear and attainable is crucial for effectively managing debt while simultaneously building savings. Begin by identifying your short-term and long-term goals. Short-term goals might include paying off high-interest credit card debt, while long-term goals could focus on building an emergency fund or saving for retirement. It’s important to prioritize these goals based on urgency and impact.
- Define specific amounts: Determine the exact amount you aim to save or pay off each month. This precision helps in creating a focused plan.
- Set realistic deadlines: Assign a timeline to each goal to maintain motivation and track progress effectively.
- Balance is key: Allocate your resources wisely between debt repayment and savings to ensure neither is neglected.
By crafting a balanced plan with precise targets and timelines, you empower yourself to tackle financial challenges with confidence and clarity.
Implement a Balanced Budgeting Approach
Adopting a balanced budgeting approach is essential for effectively managing your finances while working towards both debt repayment and savings goals. Begin by assessing your current financial situation, which includes listing all income sources and expenses. With this information, categorize your expenses into fixed and variable costs, and identify areas where you can make adjustments. Prioritize your debt by interest rate, focusing on paying off high-interest debts first to minimize long-term costs.
Once your debts are prioritized, allocate a specific percentage of your income to savings. Consider using the 50/30/20 rule as a guideline, where 50% of your income goes to necessities, 30% to discretionary spending, and 20% to savings and debt repayment. Adjust these percentages based on your personal goals and financial situation. Regularly review and adjust your budget to reflect changes in income or expenses. By maintaining a clear and organized budget, you can confidently work towards a debt-free future while building a solid savings foundation.
- List all income and expenses
- Categorize expenses into fixed and variable costs
- Prioritize debt by interest rate
- Allocate a percentage of income to savings
- Regularly review and adjust your budget
Utilize Automated Systems for Consistent Progress
Harnessing the power of automation can be a game-changer in your journey to balance debt repayment and savings. By setting up automated systems, you ensure that your financial goals are consistently prioritized without the need for constant manual intervention. This approach not only helps in maintaining discipline but also in minimizing the temptation to divert funds elsewhere. Consider implementing the following strategies:
- Automated Transfers: Set up recurring transfers from your checking account to your savings account. This ensures that a portion of your income is consistently allocated towards savings, making it a non-negotiable part of your financial routine.
- Debt Repayment Scheduling: Use automated payments to manage your debt obligations. This guarantees timely payments, helping you avoid late fees and reducing the mental load of remembering due dates.
- Progress Tracking Tools: Leverage apps or software that track your progress automatically. These tools provide real-time updates and visual representations of how close you are to reaching your goals, offering motivation and clarity.
By integrating these automated solutions, you create a robust framework that supports consistent financial progress, allowing you to focus on other aspects of your life with peace of mind.